• Skip to main content
  • Skip to header right navigation
  • Skip to after header navigation
  • Skip to site footer
MyZA

MyZA

News, Directory, Events and Other Stuff

  • Social Media
  • Sport
  • World News
  • Home
  • Submit News
  • Directory
  • Events
  • Stratlec
  • TFSA
  • News
    • APO
    • Today’s Sport News
    • Todays Social Media and Tech Headlines
    • Today’s World News
    • Today’s SA Financial News
  • Contact
You are here: Home / Archives for Short-Term Insurance

Short-Term Insurance

4 December 2025

TransUnion South Africa Busts Three Short-Term Insurance Industry Myths

Location: Business

Every industry has its myths, and the short-term insurance environment is no exception: leading industry players plan their growth strategies around perceptions of a limited pool of customers, focusing mostly on pricing strategies to attract new business, and finding ways to avoid consumers perceived as too risky.

The best way to confirm or ‘bust’ industry myths is to test them through experiments and data analysis to reveal the truth – and that’s exactly what TransUnion South Africa did with data it holds in the short-term insurance sector.

“South African consumers remain under pressure despite recent interest rate cuts, making this an opportune moment for insurers to rethink their customer acquisition and retention strategies – and to challenge the truisms they’ve relied on in recent years,” said Schalk Fischer, insurance lead at TransUnion South Africa. “To drive better outcomes, insurers must evolve and adapt their strategies to respond to changing market conditions, drawing on risk-management solutions that feature unique data and advanced analytics.”

Myth 1: With stagnant total policy volumes, the only way for an insurer to grow is to win customers from other insurers.

In assessing all new short-term insurance policies taken out between April 2024 and March 2025, TransUnion found that only 17% of new policies were opened by consumers moving to another insurer. Another 37% involved ‘policy splitting’, where consumers moved cover of one of their assets to a new provider, but did not move their whole portfolio.

This means that roughly 54% of new policies are opened due to churn – a significant portion, but certainly not the overwhelming portion that many insurers believe it to be.

“This data shows key growth opportunities for insurers lie among consumers who are new to insurance. In fact, 33% of new policies opened during the time of the study were taken out by consumers who had not had an insurance premium in the previous 24 months,” Fischer said. “While the short-term industry will always be very competitive, there are growth opportunities outside of working aggressively to attract customers from other insurers.”

Myth 2: Loyalty in short-term insurance is dead. Price is the primary variable.

With many consumers scrambling for cost savings, price is perceived to be the most important differentiator between insurers, along with being seen as the main reason that consumers leave one insurer for another.

TransUnion’s analysis showed that 13% of insured consumers who cancel their insurance eventually return to their original insurance provider over time, without switching to another insurer in the interim.

This brand loyalty is fairly consistent between different distribution channels: 9% for banks’ insurance offerings, 11% for brokers, and 14% for direct insurers.

“These findings highlight that, while insurance pricing is certainly a leading consideration among consumers, it is evident that brand loyalty is still a driving factor,” Fischer said. “Marketing and acquisition strategies clearly focus on price, but there’s a greater than expected opportunity to build loyalty that will either retain customers or encourage them to return to brands they have trusted before.”

Myth 3: The new-to-insurance segment is small and only includes risky younger consumers.

TransUnion’s analysis revealed that one in three (33%) consumers who took out policies between April 2024 and March 2025 were new to insurance – they did not have short-term insurance payments linked to their identity number in the previous 24 months.

However, this doesn’t necessarily mean that all newly insured consumers were uninsured before. Some may have previously been covered under their partner or spouse, and later separated their insurance portfolios, or they could have been young adults who sought their own cover after being included in their parents’ policies.

“These findings show that insurers need to expand the scope of how they segment their target audiences, as new-to-insurance consumers are not always who they’re perceived to be,” Fischer adds.

The analysis revealed additional insights into consumers taking out a policy for the first time. Only 6% were aged 18 to 24 years – perceived to be the riskiest consumers – while the greatest portion of these consumers (36%) were aged 25 to 35 years, followed by 36 to 45 year olds, who took out 25% of new policies. It’s clear, then, that consumers aged 25 to 45 present the greatest opportunity for insurers.

In overlaying loyalty data with these findings, it emerged that only 1% of 18 to 24 year olds shopped around for a better deal once they were granted cover, while less than a quarter (24%) of 25 to 35 year olds shopped around. However, consumers aged 36 to 45 showed the greatest propensity to shop around for a better deal, with 29% taking on that challenge.

The myth is officially busted: opportunities for growth lie well beyond young consumers who have only just reached eligibility to apply for their own short-term insurance policies.

“While the short-term insurance market is perhaps not growing at the rate that many insurers would like, our analysis shows that it’s far from stagnant. Clear segmentation along with careful risk management and profitability assessments can help providers acquire lower-risk, higher-value customers across diverse groups of potential customers,” Fischer said. “While price remains a significant driver among consumers, other variables continue to play a meaningful role in building customer loyalty.”
Read moreTransUnion South Africa Busts Three Short-Term Insurance Industry Myths
17 October 2025

How to Get out of the Debt Trap

Location: News

There are institutions which can help if you’re in debt

Read moreHow to Get out of the Debt Trap
25 February 2025

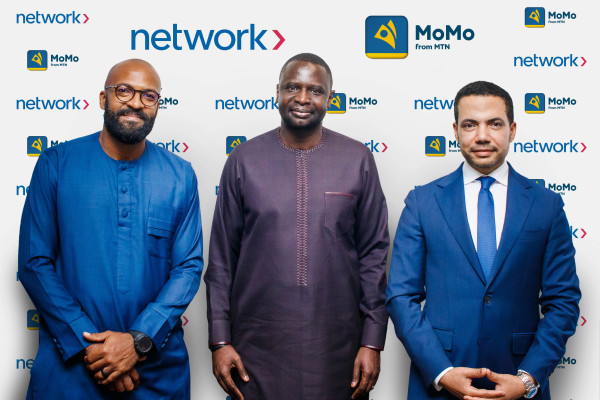
Network International appointed as Payment Processing Partner by MTN Group Fintech

Location: News
Network International

Network International (Network) (www.Network.ae), a leading enabler of digital commerce across the Middle East and Africa (MEA), has been appointed as a Payment Processor – Issuing partner for MTN Group Fintech, Africa's leading mobile financial services provider. This partnership marks a significant extension of Network's portfolio of issuer processing collaborations throughout the African continent. 

With a footprint spanning over 50 countries and serving over 250 financial institutions, Network International brings its expertise to this partnership which will enhance MTN Fintech's cutting-edge mobile services and provide even greater value to stakeholders and customers across Africa. 

The partnership will focus on rolling out card issuance products across key MTN Fintech markets, starting with Rwanda which is already operational. Soon   Uganda, Ivory Coast, and Nigeria will also be covered under this collaboration.  Network International will provide a comprehensive range of services, including transaction processing, card management and online fraud prevention. MTN Fintech users will benefit from a seamless experience accessing both traditional mobile services and innovative digital payment solutions. 

Dr. Reda Helal, Group Managing Director – Processing, Africa and Co-Head Group Processing at Network International commented: “Our collaboration with MTN Group Fintech marks a major milestone for our outsourced payments services in Africa. It demonstrates our ability to successfully serve Mobile Network Operators (MNOs) via our fully-fledged processing solutions and our continued dedication and commitment to the African region. We are excited to support MTN Group Fintech's growth strategy, and its business development plans across the continent.”  

Cedric N'guessan, Executive for Payment and E-commerce at MTN Group Fintech added, "This collaboration with Network International is pivotal in enhancing financial inclusion across Africa and beyond. It enables our customers to actively engage in the global economy, aligning perfectly with our strategic goals alongside Mastercard to broaden access to digital financial services across the continent." Read More (https://apo-opa.co/43aKuII) 

MTN Group provides voice, data, fintech, enterprise wholesale and API services to more than 288 million customers in 14 African markets.   

Distributed by APO Group on behalf of Network International.

For more information, please contact:  
MTN Group Press Office
MTNGroup.PressOffice@mtn.com 

MTN Group Fintech (Proprietary) Limited: 
Head Office: 216-14th Avenue Fairland 2195, Private Bag 9955 Cresta 2118 South Africa 
Tel +2711 912 3000 
Fax +2711 912 4093 
Website www.MTN.com

Corporate Communications: 
Network International 
Dubai, UAE 
Tel: +971 4 303 2431 
lambert.espedido@network.global   

Follow us:
X: https://apo-opa.co/3QwQZht
Linkedin: https://apo-opa.co/4khrvCr

About MTN Group Fintech:
MTN Fintech, the platform business of MTN Group, is dedicated to revolutionising global financial services through innovative digital technology solutions. Leveraging MTN's extensive reach and expertise in telecommunications, MTN Fintech is committed to advancing financial inclusion for all and empowering communities in Africa. With a primary focus on pioneering mobile financial services, digital payments, e-commerce, short-term insurance, and remittance capabilities, MTN Fintech strives to establish seamless, accessible, and secure financial ecosystems that shape the future of digital finance. 

About Network International:
Network International is the Middle East and Africa's largest and leading digital payments company. Our purpose is to help businesses and economies grow by simplifying payments and commerce. We operate in 50+ countries serving governments, banks, fintechs, merchants and public sector companies. We have 2,000+ employees based in our markets serving over 250 financial institutions and 130,000+ merchants.  

Media files
Network International
Download logo
Read moreNetwork International appointed as Payment Processing Partner by MTN Group Fintech
26 June 2024

Complainants Get R386-milllion Back In Insurance Payouts

Location: MyPR

The Ombudsman for Long-term Insurance (OLTI) and the Ombudsman for Short-term Insurance (OSTI) have published their last joint annual report for 2023, as they have now been incorporated into the National Financial Ombud Scheme South Africa (NFO). From 1 March 2024, the NFO, an industry ombud scheme, commenced operations with the merger of four separate …

Read moreComplainants Get R386-milllion Back In Insurance Payouts
19 March 2024

Gap Cover vs. Medical Aid: Understanding the Differences and Complementary Nature

Location: MyPR

In today’s complex healthcare landscape, understanding the nuances between various insurance products is crucial for ensuring comprehensive coverage and financial protection. Two key options available to members of medical schemes are Gap Cover and Medical Aid. While they serve distinct purposes, they also complement each other in providing holistic healthcare coverage. Let’s delve into the …

Read moreGap Cover vs. Medical Aid: Understanding the Differences and Complementary Nature
5 March 2024

Consumers Come Out Tops With Formation Of New One-Stop Ombud Scheme

Location: MyPR

1 March 2024, Johannesburg, South Africa –  The newly-formed National Financial Ombud Scheme (NFO) today announced the commencement of operations as a single, one-stop, all-in-one dispute resolution service made up of the four (4) former existing services – the Ombudsman for Banking Services (OBS); the Credit Ombud (CO); the Ombudsman for Long-Term Insurance (OLTI); and the Ombudsman …

Read moreConsumers Come Out Tops With Formation Of New One-Stop Ombud Scheme
29 February 2024

National Treasury publishes Policy Position Statement on financial ombud system

Location: News

National Treasury publishes Policy Position Statement on financial ombud system

National Treasury has published its Policy Position Statement titled, 'A Simpler, Stronger Financial Sector Ombud System', which outlines proposed reforms to the ombud system.

The Policy Position Statement follows the publication of a World Bank Diagnostic Study in 2021 titled, 'South Africa - Financial Ombud System Diagnostic'.

“The study provided an independent review of South Africa’s financial ombud system and recommended reforms to enhance consumer protection and encourage good quality outcomes in the financial services sector,” National Treasury said on Thursday.

Prior to the diagnostic study, an earlier discussion document titled, 'A Known and Trusted Ombud System for All (2017)', had proposed initial reforms to the ombud system, which were later included in the Financial Sector Regulation (FSR) Act (Act 9 of 2017), as part of the Twin Peaks financial sector regulatory reform.

National Treasury said the publication of the policy position is a necessary step to communicate and publish its Policy Position Statement and accompanying detailed feedback statement, including an implementation plan.

“This publication also provides a response to consultation comments, and enables ombud schemes and the Ombud Council to work towards implementing a reformed structure,” National Treasury said.

Key elements of the proposed reform that National Treasury supports include:

  1. Structural reform of the ombud system, that will reduce the seven ombud schemes to two:
  • A new, consolidated ombud scheme: National Financial Ombud (NFO) – a new body, independent of industry and government, replacing 6 of the current 7 schemes (all the industry schemes plus the FAIS Ombud).
  • A Retirement Funds Ombud (RFO) – a renamed and reformed Pension Funds Adjudicator, with a board to underpin its independence and oversee its efficiency and effectiveness. National Treasury considers that it would be too complex a transition for the NFO to absorb the work of the RFO at this stage. However, this is likely to happen in the medium term, once the NFO has been up and running for a while.
  1. A modified Ombud Council – modifications to the title and appointment of its chief executive and (later) a review of its powers in the light of the simplification of the ombud system.
  2. Improved consistency across the ombud system on visibility and accessibility, eligibility of complainants, processes, powers and enforceability of decisions, and improved coverage to significantly reduce jurisdictional gaps and overlaps

“Full implementation of the above reforms will require legislative amendments. In the interim, National Treasury notes and welcomes the voluntary amalgamation, in consultation with the Ombud Council, of four of the current industry schemes (Credit, Banking, Long-term Insurance and Short-term Insurance) to form a new, streamlined industry scheme, the National Financial Ombud Scheme South Africa (NFO).

“The NFO is expected to commence operations on 1 March 2024, after recognition by the Ombud Council. This is an important step towards the broader reforms outlined in the policy position and will simplify their implementation,” National Treasury said.

The following documents are available on the website of the National Treasury at www.treasury.gov.za:

  • Annexure A: A Simpler, Stronger Financial Sector Ombud System: Policy Position Statement.
  • Annexure B: A Simpler, Stronger Financial Sector Ombud System: Feedback Statement.

- SAnews.gov.za

nosihle
Thu, 02/29/2024 - 13:25

201 views
Read moreNational Treasury publishes Policy Position Statement on financial ombud system
27 February 2024

Smart Money Moves: A Simple Guide to Budget-Friendly Insurance in South Africa

Location: MyPR

It’s time to think smart about our finances, especially when it comes to budgeting. Let’s break down some easy-to-understand tips for managing your money wisely, focusing on insurance in South Africa. Keep Your Insurance Going Money gets tight, we know. However, cancelling your insurance might not be such a smart move. Apart from exposing yourself …

Read moreSmart Money Moves: A Simple Guide to Budget-Friendly Insurance in South Africa

Copyright © 2026 · MyZA · All Rights Reserved · Powered by Stratlec Online