How an Arms Company Tried to Block Your Right to Know – And Failed
Integrated Convoy Protection misled the court

MyZA
News, Directory, Events and Other Stuff
Integrated Convoy Protection misled the court
Internet shutdown affects millions of Africans more and more often and are most prominent during elections or protests.
South African consumers continue to adapt to a fluctuating economic environment, with TransUnion’s Q1 2025 Consumer Pulse study[1] revealing key trends in household financial management, credit activity and vehicle financing. Amid ongoing financial pressures, a significant increase in intended hybrid vehicle financing highlights evolving consumer preferences.
“Despite the challenges posed by inflation and economic uncertainty, South Africans continue to show resilience in managing their finances,” said Ayesha Hatea, Director of Research and Consulting at TransUnion. “We are seeing notable shifts toward more purposeful financial planning, credit management and strategic spending. While economic pressures remain, consumers are finding ways to balance credit usage, savings, and debt repayments more effectively.”
Economic Concerns and Credit Usage Trends
The report highlights consumers’ ongoing financial concerns, with 42% of respondents stating that their household income is not keeping up with inflation, despite inflation being at the lower end of the Reserve Bank’s target range[2]. These ongoing concerns could be because 40% of consumers said their income stayed the same in the past three months, while 22% reported it decreased.
“With more than six in ten South Africans reporting no increase in their income, it’s clear to see why consumers are trying to find new ways to manage their financial commitments, including taking on more credit, and different types of credit, for key purchases,” said Hatea.
The survey data reveals that 37% of respondents plan to apply for new or refinance existing credit within the next year, with 52% of all those surveyed saying they’ve used Buy Now, Pay Later services in the past 12 months.
Amid ongoing concerns about a recession, consumers indicated that they are actively taking steps to prepare. Among those who said they think South Africa is currently in a recession or will be in one by the end of Q1, the most respondents (59%) said they’re preparing for a possible recession by reducing spending followed by 58% building up their savings and 35% prioritising paying down debt.
Debt Repayments and Savings Trends
The data also reveals shifting trends in debt repayments and savings. A worrying trend is that 38% of respondents in Q1 2025 said they’ll be unable to pay at least one of their current bills and loans in full, up from 35% in Q4 2024.
Among those who said they’ll be unable to pay, 34% reported they plan on paying partial amounts they can afford but not the whole balance, while 25% said they’ll dip into their savings to help pay their current bills and loans. A further 20% of consumers aim to borrow money from friends or family members to meet their payment commitments. Additionally, 35% of those surveyed are looking to take on temporary or gig work.
“Managing debt effectively while maintaining savings is a key challenge for many South Africans,” said Hatea. “Consumers who are struggling to meet their payment commitments should engage with their lenders to potentially renegotiate current payment terms. Lenders do not want consumers to default on their debts, and they are often willing to discuss available options with the intention of creating prudent, sustainable financial solutions.”
Hybrid Vehicle Financing Expected to Increase
Of particular interest in the Q1 2025 study is the finding that 36% of consumers planning a new vehicle loan or lease within the next year would consider hybrid vehicles, while 25% would consider an electric vehicle. In comparison, 32% preferred traditional internal combustion engine vehicles, making hybrid cars the top consideration for new vehicle loans or leases among those surveyed.
The latest TransUnion Vehicle Pricing Index (VPI) reflects this trend, with the anticipated introduction of more affordable EVs priced under R1 million expected to accelerate their adoption in 2025, thanks to broadening consumer options in the hybrid and EV market.
“This trend highlights how consumers are adapting to broader economic and environmental changes,” said Hatea. “Hybrid vehicles are becoming more accessible, and their appeal extends beyond cost savings to include long-term benefits such as reduced environmental impact and lower running costs. As this market continues to evolve, we anticipate sustained growth in consumer interest and adoption.”
Fraud Concerns
The study highlights that nearly one in three respondents (31%) check their credit reports monthly, with 54% of those who said they monitor their credit doing so to try and improve their credit score. This indicates an awareness of the importance of credit health management.
A smaller 34% of credit monitoring consumers said they check their credit reports to protect against fraudulent activity. More than half (51%) of all those surveyed reported being targeted by email, online, phone call or text messaging fraud in the last three months but not falling victim, emphasising the importance of heightened security awareness.
Among the most common fraud schemes reported by those who said they were targeted were money/ gift card scam (33%), smishing (33%), phishing (32%) and third-party seller scams on legitimate online retail websites (31%), emphasising the urgency for consumers to remain vigilant.
“With digital transactions and online banking becoming standard, financial institutions are urged to implement stronger fraud prevention measures, while consumers are encouraged to monitor their credit activity and adopt safer financial practices,” said Hatea.
Adapting to Improve Credit Health
In response to ongoing financial pressures, South African consumers are making strategic adjustments to their household budgets. In the past three months, 52% said they have cut back on discretionary spending such as dining out, travel and entertainment, with 43% of them reporting scaling back on large purchases like furniture, appliances and cars. This cautious approach highlights a continued emphasis on financial resilience and long-term stability.
“Our findings show that South Africans are taking a more proactive approach to managing their finances amid economic uncertainty,” said Hatea. “While financial pressures persist, consumers are prioritising essential spending, reducing discretionary expenses, and making thoughtful financial decisions to maintain stability. Providing them with the right tools, education and financial products will be crucial in supporting their financial well-being in the months ahead.”
The Reserve Bank’s decision to reduce the repo rate by 0.25% to 7.5% this January, with no change in March[3], aims to support economic growth and ease borrowing costs for consumers. This adjustment, coupled with improved inflation expectations, is expected to provide further relief to consumers and stimulate economic activity.
As economic conditions evolve, businesses, financial institutions, and policymakers will need to align with these shifting behaviours, offering solutions that promote financial inclusion, long-term stability, and economic growth.
Consumers can get their free annual credit report from TransUnion here.
[1] Q1 2025 South African Consumer Pulse Study was a survey of 950 South African adults from Feb. 10 to 24, 2025.
[2] Inflation Targeting Framework
[3]: repo rate by 0.25% in January to 7.5%: Current Market Rates
Museveni’s iron grip on the Ugandan military makes it difficult to imagine a peaceful transfer of power.
Two interventions show what can and what can’t be done
“Karate is not only about kicking and punching but also building the character of the individual”
The kidnapping industry fuels insurgencies in Africa’s Sahel region.
The latest TransUnion South Africa Mobility Insights Report (formerly the Vehicle Pricing Index) for Q1 2025 highlights a strong rebound in the country’s automotive market. This recovery has been driven by improved consumer sentiment, declining interest rates, access to retirement savings through two-pot withdrawals, and rising real wages. According to naamsa data, new passenger vehicle sales continued their upward trajectory in the first quarter, with monthly volumes averaging over 34,000 units, the highest levels seen since Q3 2015.
Affordability remains a key driver of vehicle purchasing and financing decisions. Creative financing options, longer ownership cycles, and the growing availability of value-oriented models are significantly reshaping consumer behaviour, particularly among younger and first-time buyers. The Q1 2025 TransUnion South Africa Mobility Insights report highlights that several emerging brands offering competitively priced vehicles have recorded strong year-over-year growth, contributing to the overall surge in new vehicle sales.
“South African consumers are returning to the vehicle market with a clear focus on value and flexibility,” says Lee Naik, CEO TransUnion Africa. “We’re seeing a continued shift away from traditional premium segments in favour of more accessible alternatives that meet evolving needs and budgets.”
Insurance Trends Reveal Shifting Landscape and Rising Risk
The Q1 2025 report introduces new data on insurance-linked vehicle asset finance (VAF). As of early 2025, only 39% of insured vehicle owners had financed vehicles, down from 44% in 2020. This signals a rise in alternative financing or lapses in insurance post-purchase, especially concerning as TransUnion’s 2024 Insurance Survey found that 25% of vehicle users had driven uninsured in the past six months.
This trend has implications for lenders, who face greater asset risk in the event of write-offs without insurance recovery, and for insurers, whose portfolios may now carry increased exposure. To mitigate these risks, strategies such as bundled insurance, usage-based coverage and low-cost flexible insurance models are growing in relevance.
Used Vehicle Momentum Slows as New Sales Lead Recovery
While used vehicles have dominated financing trends in recent years, Q1 2025 marked a notable shift back toward new vehicle purchases, driven by easing interest rates, improved entry-level model availability, and aggressive manufacturer incentives. Notably, the influx of competitively priced Chinese models has attracted budget-conscious buyers away from the used market, fuelling fresh growth in new vehicle registrations.
“Consumers are holding onto their cars for an average of six to eight years, compared to the previous five years, a trend that reflects affordability constraints and a more cautious approach to ownership,” says Naik.
Affordability and Flexibility Drive Change
The report reveals that shifting consumer preferences are reshaping the competitive landscape, with some established manufacturers experiencing year-over-year sales declines while more affordable and value-driven entrants continue to gain market share.
“The definition of value is changing,” says Naik. “It’s no longer just about the price tag, it’s about financing flexibility, long-term ownership costs, and trust in the product. That’s what’s driving consumer decisions today.”
Social Media's Growing Influence on South African Car Buyers
Generation Z’s1 rising influence, with a 27.9% year-on-year increase in vehicle finance volumes, highlights why social media has become essential for automotive brands aiming to attract younger buyers. As South Africans spend over 3.5 hours daily on platforms like TikTok, Instagram, and YouTube, 76% of users now turn to social media for product research, pushing automotive brands toward digital-first strategies with influencer campaigns, short-form videos, and interactive content, yet South Africa’s low social media ad spend signals a major untapped growth opportunity for marketers.
Social platforms are reshaping how South African consumers research, engage with, and purchase vehicles, particularly among Gen Z and Millennials1 who expect personalised, digital-first experiences. To stay competitive, brands are adopting influencer collaborations, platform-specific strategies, AI-enabled targeting, and immersive tools like augmented reality and virtual reality. Social commerce is gaining ground as buyers look for seamless, in-app journeys from browsing to booking.
Economic Outlook: Growth with Caution
The broader economic outlook for South Africa in 2025 remains cautiously optimistic, with GDP expected to grow by 1.4%, driven primarily by household consumption. While industrial output remains under pressure, consumer-driven sectors, particularly retail and vehicle sales, continue to show resilience. Vehicle export activity rose modestly by 0.4% year-over-year in Q1 2025, signalling a gradual recovery following the sharp decline in the previous quarter.
“The strong recovery in new vehicle sales is a positive sign,” says Naik. “But sustaining this growth will require policy certainty, infrastructure investment, and structural reforms. Without these, the economy remains vulnerable.”
“The South African automotive sector is adapting to new consumer behaviours and market forces. The insurance gap, affordability options, credit access and rising Gen Z1 participation will shape the road ahead. Collaboration across industry players is vital for long-term growth,” concludes Naik.
Read the full TransUnion South Africa Mobility Insights Report here.
1 Generation X (Gen X): Born 1965–1980; Millennials (Gen Y): Born 1981–1996; Gen Z (Generation Z) Born 1997–2012
ENDS
Sixty-eight percent of South Africans TransUnion surveyed from 21 November to 9 December 2024 indicated that they had been targeted by email, online, phone call or text messaging fraud in the last three months, with 13% saying that they had become victims. Among those who said they were targeted, the most common reported schemes were phishing, where fraudulent emails, websites, social posts or QR codes are meant to steal personal data (33%), smishing where fraudulent text messages try to trick the user into sharing data (31%), and third-party scams on legitimate online retail sites (28%).
In a separate question in that same survey, one third (33%) said that they had lost money to email, online, phone call or text messaging fraud in the last year. Nearly one third (32%) of those who said they lost money reported it happening via third-party seller scams on legitimate online retail sites. This was followed by 26% who lost money via money mule scams where users are solicited to transfer or move illegally acquired money on behalf of someone else, and 23% who lost money via stolen credit card or fraudulent charges.
These and other findings came from research used for building the newly released TransUnion (NYSE: TRU) H1 2025 Update to the State of Omnichannel Fraud Report, which shows how South African consumers continue to be targeted by fraudsters through a wide range of channels.
“With South Africa having the second greatest number of smartphone connections in Sub-Saharan Africa, with people using mobile phones to conduct their everyday business, connect with friends, or keep in touch with family, it’s easy to understand why digital fraud would be such a common tactic among fraudsters targeting this region,” said Amritha Reddy, senior director of fraud solutions at TransUnion Africa. "While cybercriminals will attack at any time using any channel, they appear to focus on channels most popular in the regions they are targeting.”
Nearly one third (31%) South African respondents indicated that they were not aware of being targeted by email, online, phone call or text messaging fraud at all, which raises questions as to whether these respondents were in fact targeted, yet simply unaware of the threat.
Based on the TransUnion study, South Africa had the greatest percentage of respondents among countries surveyed in Africa who said they fell victim to email, online, phone call or text messaging fraud in the second half of 2024. In contrast, Zambia had the lowest percentage of consumers who said they fell victim to fraud in the countries surveyed in Sub-Saharan Africa.
Table 1: Fraud Types Most Frequently Used to Target Consumers in Sub-Saharan Africa in the Last Three Months
| Country | Targeted and fell victim | Targeted but didn’t fall victim | Not targeted | Most reported fraud scheme |
| South Africa | 13% | 55% | 31% | Phishing |
| Kenya | 11% | 71% | 19% | Smishing |
| Namibia | 11% | 52% | 37% | Vishing |
| Rwanda | 10% | 57% | 33% | Money mule |
| Zambia | 9% | 70% | 21% | Smishing |
Source: TransUnion Consumer Pulse Survey of 1,000 people in South Africans in December 2024
Communities and Video Gaming Among Top Industries Targeted by Suspected Digital Fraud
Globally, TransUnion determined that communities (online forums and dating sites) experienced the highest rate of suspected digital fraud[1] attempts in 2024. Nearly 12% of all attempted transactions within communities last year were suspected to be digital fraud. This was closely followed by video gaming (11%), with gaming (including online betting, poker, etc.) at 8% and retail (8%) rounding out the top four.
The logistics industry, which has seen growth in shipping fraud (often perpetrated by organised crime rings), saw the greatest suspected digital fraud volume growth globally in 2024, up more than 100% over 2023. That being said, the fraud rate remains at a relatively modest 3%. Gaming also saw a significant year-over-year (YoY) volume change, up 20%. Telecommunications (-79%), insurance (-29%) and video gaming (-23%) saw the greatest decreases in suspected digital fraud volume YoY.
“Digital fraud on community platforms is by no means a new phenomenon. In 2024, it appears that fraudsters targeted these areas with a renewed vigour,” said Reddy. “Cybercriminals take advantage of the trust inherent on community-based platforms, and target members with a wide range of scammer solicitations, the most reported type of digital fraud in communities.”
For attempted transactions where the consumer or fraudster was located in South Africa, gaming experienced the highest suspected digital fraud rate in 2024 at 6.3% with an 8.1% decrease in the volume of suspected digital fraud from 2023. The only South African industries in which suspected digital fraud increased YoY were insurance and communities.
“It is encouraging to see that attempts at digital fraud have decreased across all but two of the surveyed industries in South Africa,” Reddy says. “Organisations that draw on identity, device and behavioural insights to help them interact with legitimate consumers while mitigating fraud risk are more likely to protect themselves and their customers from the scourge of digital fraud.”
Table 2: Highest Digital Fraud Rates Across Leading Industries in South Africa
| Industry |
Suspected digital fraud attempt rate 2024 |
Change in volume of suspected digital fraud attempts from 2023 to 2024 |
| Gaming |
6.3% |
-8.1% |
| Telecommunications |
6.2% |
-58.5% |
| Financial services |
6.1% |
-29.6% |
| Video gaming |
6.0% |
-67.2% |
| Insurance |
5.6% |
166.5% |
| Communities |
5.0% |
4.0% |
| Retail |
2.9% |
-8.9% |
| Travel & leisure |
0.5% |
-87.0% |
Source: TransUnion TruValidate™
Fraud Comes with a Heavy Cost to Consumers
Consumers faced significant losses due to fraud. Among consumers TransUnion surveyed in 18 countries and regions in November and December 2024, 29% said they lost money due to email, online, phone call or text messaging fraud in the last year. The survey determined that the median amount those consumers said they lost due to fraud in the past year was R32,447. For those who said they lost money due to fraud in South Africa, the median stated amount lost was R12,518[2].
TransUnion came to its conclusions about digital fraud based on intelligence from TransUnion TruValidate.
Specific country and regional data in the report includes South Africa, Botswana, Brazil, Canada, Chile, Colombia, the Dominican Republic, Guatemala, Hong Kong, India, Kenya, Mexico, Namibia, the Philippines, Puerto Rico, Rwanda, Spain, the United Kingdom, the United States and Zambia. Download the TransUnion H1 2025 Update to the State of Omnichannel Fraud Report for more information and insights about the global fraud trends.
[1] The rate or percentage of suspected digital fraud attempts reflects those which TransUnion customers determined met one of the following conditions: 1) denial in real time due to fraudulent indicators, 2) denial in real time for corporate policy violations, 3) fraudulent upon customer investigation, or 4) a corporate policy violation upon customer investigation — compared to all transactions assessed. The country and regional analyses examined transactions in which the consumer or suspected fraudster was located in a select country or region when conducting a transaction. Global statistics represents every country worldwide and not just the select countries and regions.
[2] Based on the exchange rate on 6 Jan. 2025
TransUnion Africa, in partnership with MTN and Chenosis, has launched CreditVision® Telco Data Score, a first-of-its-kind credit scoring solution that uses mobile phone call data records to help millions of South Africans with limited or no formal credit history gain access to financial services.
This alternative data scoring model leverages Call Data Records (CDR), which reflect patterns in mobile phone network usage behaviour and correlates it to an individual’s financial behaviour. By using telco data as a proxy for financial reliability, the CreditVision Telco Data Score enables lenders to accurately assess New-to-Credit (NTC) consumers and expand access to safe, affordable credit.
Helping the Financially Excluded
According to TransUnion estimates, over 1.4 million credit-invisible South Africans open new credit accounts each year, contributing to more than four million new accounts over the past three years. Yet traditional scoring models often fail to assess this segment accurately, leaving more than 16 million adults outside the formal credit system.
Approximately 35% of New-to-Credit consumers are under the age of 25, many of whom are new to the workforce and often use credit to buy clothing for work, highlighting the need for innovative tools that support younger, digitally active individuals who may lack a conventional credit footprint. Successfully integrating these and other excluded consumers into the economy could add approximately R173 billion1 to South Africa's GDP.
“With over 500 million2 people across the continent excluded from formal financial systems, the scale of the challenge is undeniable. Traditional data models fail to reflect the realities of African consumers, leaving millions without access to credit and the opportunities it enables. Financial inclusion isn’t just part of our mission, it’s our mandate,” said Lee Naik, CEO of TransUnion Africa. “That’s why we believe the only way forward is to think differently, to lead with bold, African-born solutions. Innovations like CreditVision Telco Data Score, designed for Africa, by Africa, are helping us responsibly harness mobile data at scale. In doing so, we’re not only expanding access to credit, but we’re also unlocking economic potential, accelerating inclusive growth, and reshaping the future of finance across the continent.”
Creating Opportunity with Consent and Compliance
The use of CDR data is subject to explicit consumer consent and is managed in compliance with South Africa’s Protection of Personal Information Act (POPIA). MTN is responsible for consent management and will ensure that Chenosis, MTN’s API marketplace, facilitates the connection between MTN’s data ecosystem and partners like TransUnion in a secure and scalable manner.
“This partnership demonstrates how mobile technology and secure data sharing can support positive change in the financial sector and unlock new opportunities for millions of South Africans,” said Selorm Adadevoh, Group Chief Commercial Officer, MTN Group. “We are committed to ensuring that data is used responsibly, with the customer’s interests at the forefront. This is a model of what responsible innovation can look like.”
Empowering Lenders and Growing the Economy
For lenders, the CreditVision Telco Data Score has demonstrated a 25–35% improvement in predictive performance over previous alternative data models, based on recent pre-launch validations across the retail and banking sectors.
By adopting CreditVision Telco Data Score, lenders can better predict user behaviour and support responsible lending by ensuring that credit users at risk of default are not overexposed and can be effectively supported throughout their credit journey.
Importantly, the product also helps New-to-Credit consumers establish and build their credit footprint over time. According to TransUnion data, low-risk individuals significantly increase their credit exposure within 18 months of becoming credit active, underscoring the long-term benefits of responsible financial inclusion strategies.
“With Chenosis, we enable collaboration between mobile operators and solution providers while maintaining high security and compliance standards,” said Waseem Amra, Head of Products and Platforms, Chenosis. “This partnership highlights how secure data access can support innovation in financial services that can transform lives.”
This partnership between TransUnion Africa, MTN, and Chenosis reflects the growing trend of using diverse data sources to create more accurate and inclusive financial access. Integrating mobile network insights into credit scoring provides a practical and scalable way to reach more individuals, while maintaining high standards of privacy and compliance.
“With this inclusive innovation, TransUnion has taken the lead in creating an impactful solution to one of the continent’s most pressing challenges – finding responsible pathways to greater financial inclusion that will unlock opportunities for individual and national growth. By turning mobile data into meaningful opportunity, we have set the standard in making transformation possible by showing how technology can be used in groundbreaking alternative ways. Together with MTN and Chenosis, we are building a future where every South African, regardless of their financial history, has the chance to be seen, to be trusted, and to thrive,” Naik concluded. “When financial institutions can measure risk more effectively, they can lend more confidently, and more consumers can access opportunity, and that’s a win for everyone.”
1. Based on TransUnion’s modelling and interpretation of economic market dynamics. 2. Source: The Global Findex Database 2021
SANCO accused of threats and intimidation at MyCiTI bus depot; denies any link to extortion
There were 1.9-million unsolved cases by the end of the 2024 financial year
Trust, care and belonging are the foundation for families thriving.
Amendments to the Companies Act will oblige companies to disclose the gap between the lowest paid worker and the top executive
“I saw the corrugated iron roof blowing off”
According to TransUnion’s (NYSE:TRU) Q1 2025 South Africa Industry Insights Report, the growth in originations of new credit cards, at 30.7% year-over-year (YoY), far outstripped growth for other consumer credit products during the first quarter of the year.
Strong growth in credit cards was driven, in part, by lenders extending cards to more below prime[1] borrowers than they did one year ago – up 33.1% YoY. Subprime and near prime borrowers accounted for 69.3% of credit card originations, up from 64.3% one year earlier. At the same time, lenders looked to actively manage the increased risk profile of borrowers by limiting the average credit limit on new credit cards – down 13.1% YoY.
Growth is likely to remain buoyant in the South African credit card market, with 33% of respondents to TransUnion’s recent Q1 2024 Consumer Pulse Survey saying that they planned to apply for a new credit card in the next 12 months.
Credit card average account balances increased by 7.1% YoY, although lenders’ default concerns may have been eased by the 20-basis point (bps) decrease in account-level delinquencies* over the same period, standing at 12.3% in Q1 2025.
“While inflation has dropped to the low end of the South African Reserve Bank’s target range during Q1 at close to 3%, South Africans are still experiencing financial pressures from prior price increases, turning to credit to help them make ends meet,” says Ayesha Hatea, director of research and consulting at TransUnion. “Despite these strains, consumers have increasingly prioritised keeping their credit cards in good standing, as they likely want to ensure access to the ongoing liquidity that this credit product provides.”
Vehicle loans grew at double-digit rate
The vehicle loans market continued to show encouraging signs of continued growth, as origination volumes increased by 11.6% YoY in Q1 2025. The average value of new loans also rose by 3.0% over the same period.
The highest growth rate continued to be among Gen Z[2] consumers, up 28.5% YoY. Within the Gen Z cohort, 62% of new vehicle loans were opened by consumers in the oldest subgroup in this generation, aged 26 to 29 years. This trend suggests that older Gen Z consumers are becoming increasingly active in the vehicle finance market, likely as they reach key life stages such as career stability and household formation. While this group is not necessarily New-to-Credit, their growing share of originations highlights a valuable opportunity for lenders to engage younger, upwardly mobile consumers.
In contrast, the share of vehicle loans declined across all other generations, with the exception of Gen X, where volumes remained relatively stable. This reinforces the importance of targeting older Gen Z consumers as a key growth segment in the vehicle finance space.
With a 0.25% repo rate cut announced by the South African Reserve Bank (SARB) in January followed by another in May, demand for vehicle loans is likely to remain buoyant, with more than one fifth (22%) of South Africans surveyed in the TransUnion Q1 Consumer Pulse Survey indicating that they intend to take out a new car loan or lease in the next 12 months.
“With vehicle ownership is a priority due to limited public transport offerings, buying a vehicle is often a first step into secured credit for young professionals,” said Hatea. “Vehicle finance often requires relatively small deposits, and flexible financing options can be negotiated to make monthly repayments more affordable. Borrowers don’t need as extensive a credit history to purchase a vehicle as they do to buy a home. Successfully managing a vehicle loan demonstrates financial responsibility, which can strengthen future home loan applications.”
Personal loans leveraged for meeting monthly expenses
During the first quarter of the year, consumers also increasingly turned to personal loans as strategic tools to achieve their financial objectives, with originations growing for both bank and non-bank personal loan lenders – up 2.7% and 11.5% YoY, respectively. Demand for personal loans will likely continue, with 35% of surveyed South Africans saying that they intend to apply for a personal loan in the next 12 months.
However, non-bank lenders may yet have to refocus their risk management strategies in the coming months as more than two in five (41.3%) of South Africans who hold one of these loans – 83.9% of whom are below prime borrowers – being three months or more in arrears during Q1 2025. This is a 520-basis point (bps) YoY increase and is the highest delinquency rate for this product since the previous high of 39.1% in Q2 2021.
The delinquency rate among non-bank personal loans was 15 percentage points higher than delinquencies on bank personal loans, where below prime borrowers comprise 71.8% of the bank personal loans book.
“South Africans are increasingly turning to low-value personal loans with shorter repayment terms to manage their monthly expenses. However, persistently high delinquency rates — particularly among non-bank personal loans — indicate that many consumers are under significant financial pressure and struggling to meet their loan commitments,” says Hatea. “As lenders respond to growing demand for this type of credit, it’s essential they align their growth strategies with prudent risk management to ensure long-term sustainability.”
Home loans remain under pressure
Home loans were the only sector to experience a decline in originations in Q1 2025, down 10.8% YoY. Although originations fell across all risk tiers, loans to prime and above consumers saw a particularly sharp decline, down 21.1% YoY. This continues the downward trend in home loan growth observed since Q1 2020, with exception of a moderate YoY increase between Q1 2022 and Q1 2023.
“The fact that even prime consumers are pulling back from the housing market is a clear signal that affordability remains a significant barrier,” said Hatea. “This trend has implications not only for the credit market, but also for broader economic activity tied to home ownership and property development.”
As the housing finance sector continues to soften, lenders may need to reassess their strategies. This includes rethinking product design and pricing, as well as how they connect with younger consumers and first-time buyers, in order to reignite demand in a segment that has traditionally served as a foundation of secured lending.
Table 1: Key South African Credit Market Metrics (Q1 2025 vs Q1 2024)
|
Product |
YoY origination growth |
Serious account-level delinquency rate* |
YoY basis points (bps) change in delinquency rate |
| Credit card |
30.7% |
12.3% |
-20 bps |
| Bank personal loan |
2.7% |
26.3% |
14 bps |
| Non-bank personal loan |
11.5% |
41.3% |
520 bps |
| Clothing accounts |
7.6% |
25.9% |
-294 bps |
| Retail instalment |
16.0% |
27.1% |
-138 bps |
| Retail revolving |
5.4% |
14.9% |
-350 bps |
| Home loans |
-10.8% |
7.4% |
19 bps |
| Vehicle finance |
11.7% |
5.4% |
-1 bps |
*Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears
[1] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).
[2] TransUnion age distribution: Gen Z (Born 1995 – 2010); Millennials (Born 1980-1994); Gen X (Born 1965-1979); Baby Boomers (Born 1946-1964
While millions of South Africans are unemployed and have to pinch every penny to survive, they are generously contributing to keeping the doors of the Embassy of the State of Palestine in Pretoria open. The reply to a parliamentary question from the Freedom Front Plus (VF Plus) to the Minister of International Relations and Cooperation […]
The post South African taxpayers shell out nearly R10 million over last five years to maintain Palestine Embassy appeared first on Freedom Front Plus.
West Coast small-scale fishers demand answers from fisheries department
Africa’s ‘new consumer class’ isn’t new; in the 1800s the continent called the tune for European factories.
While the economy is slowing down and South Africans look forward to spending the festive season with family, livestock farmers face a bleak festive season as foot-and-mouth disease causes massive financial losses. The Department of Agriculture is dragging its feet with enforcing legislation while more and more farmers are struggling to keep their heads above […]
The post Foot-and-mouth disease out of control: Dark times ahead for livestock farmers appeared first on Freedom Front Plus.
Popular disappointment in elected governments was a prominent trigger for coup makers.
The vigil also marks International Day of Commemoration and Dignity of the Victims of the Crime of Genocide
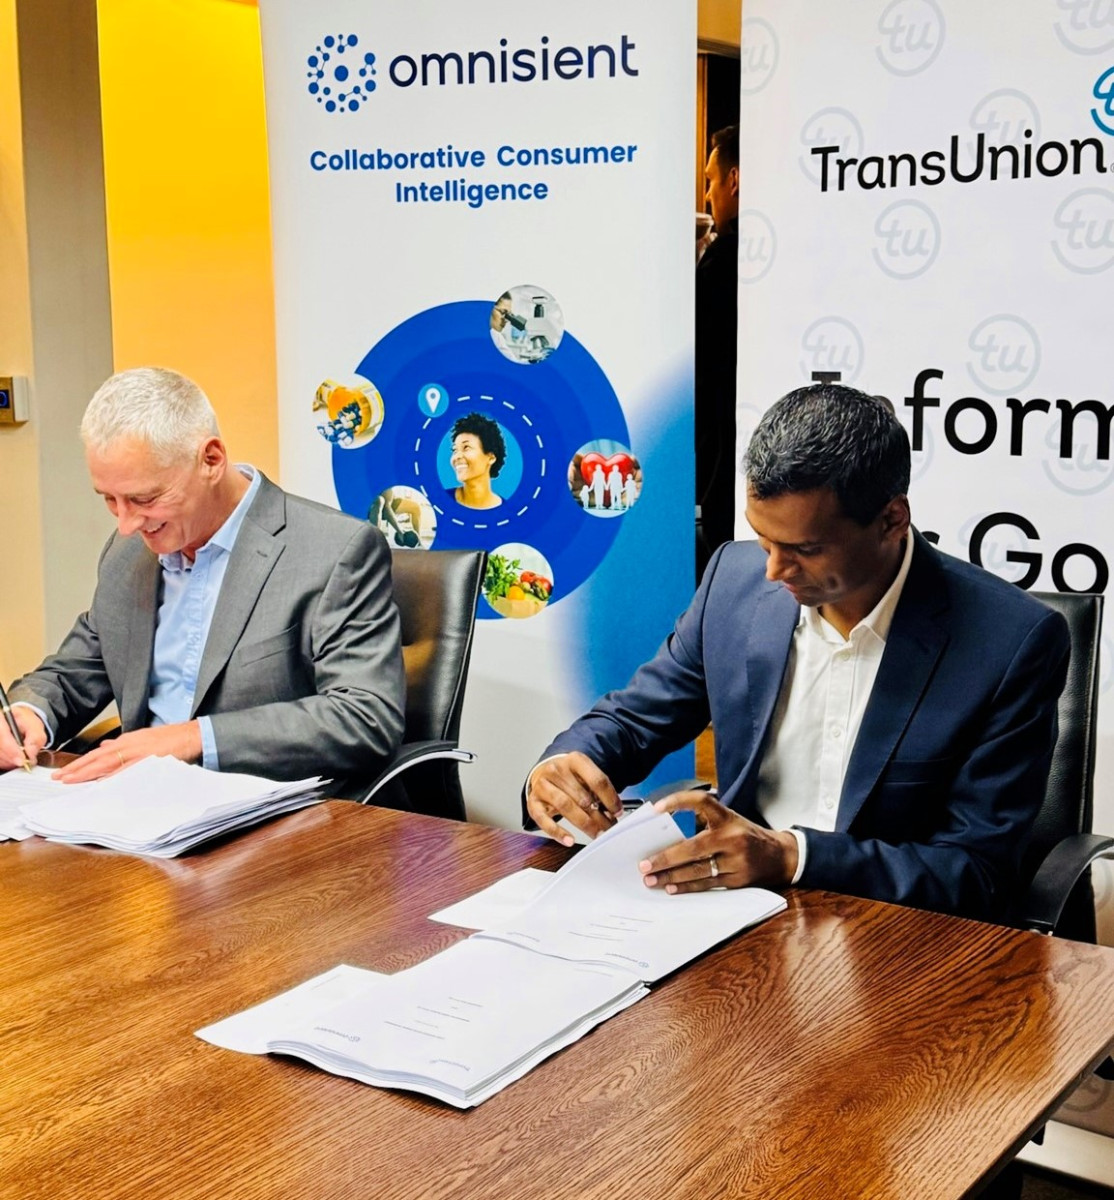
TransUnion today announced a minority investment and broader strategic partnership with Omnisient, a South Africa-founded FinTech operating internationally that offers a privacy-preserving data collaboration and advanced analytics platform. The Omnisient platform empowers businesses to safely access high-value consumer data ecosystems and rapidly integrate alternative data sets to drive intelligent decision-making. As part of the investment, a TransUnion representative will join Omnisient’s board of directors.
“The Omnisient platform allows multiple clients to use built-in advanced analytical tools to simultaneously evaluate the utility of diverse data sets, identifying those that deliver measurable value. Through this collaboration, TransUnion expects to gain access to a broader range of alternative data sources and privacy preservation capabilities. By accelerating the integration of high-impact data into our ecosystem, we intend to enhance existing solutions and develop new, market-relevant products that better meet the evolving needs of our customers,” said Lee Naik, Regional President/ CEO of TransUnion Africa.
“Traditional data models often fail to reflect the lived realities of African consumers, leaving millions without access to credit and the opportunities it enables,” said Naik. “Financial inclusion is central to unlocking economic growth across the continent. That’s why we’re committed to leading with bold, African-born solutions designed to see the unseen and serve the credit invisible by integrating alternative data sets alongside traditional credit data in ways that reflect uniquely African contexts and realities. By incorporating non-traditional indicators of financial behaviour, this approach broadens access to credit and helps us reach more underserved communities. We believe accelerating the adoption of alternative data is critical to closing the credit gap at scale, enabling faster, fairer and more inclusive access to financial services for millions across the continent."
“Our privacy-preserving data collaboration platform brings financial services and consumer brands together, allowing them to discover, validate and commercialise new alternative sources of consumer behavioural and transactional data without having to exchange sensitive personal information,” said Jon Jacobson, co-founder and group CEO of Omnisient. “This data allows financial institutions to make better risk decisions with more confidence and security, unlocking the potential to grow financial inclusion for hundreds of millions of people around the world.”
This collaboration marks a natural progression in TransUnion’s strategy to expand financial inclusion across Africa. By leveraging privacy-enabled alternative data sets through Omnisient’s platform, TransUnion intends to strengthen its ability to help address the challenge of bringing an estimated 500 million* financially excluded Africans into the formal financial ecosystem. By responsibly harnessing alternative data at scale, TransUnion sees the opportunity to bring millions of new-to-credit and credit-underserved consumers across Africa into the financial mainstream. This enables individuals to begin building a credit profile, many for the first time, laying the foundation for long-term economic empowerment. It’s a powerful demonstration of TransUnion’s commitment to using Information for Good® to drive measurable impact at scale: expanding access to credit, unlocking economic potential and reshaping the future of finance across Africa.
Global demand is rising for alternative data solutions that protect privacy, build trust and unlock value. Omnisient’s platform meets this need with technology that enables secure, privacy-preserving data collaboration. Instead of transferring raw data, Omnisient uses tokenised keys to represent personal information in the data set, ensuring privacy is maintained throughout the process. As a leading provider in Africa of secure, many-to-many data connectivity between banks, financial institutions and third-party sources, Omnisient is driving innovation in data collaboration.
*Source: The Global Findex Database 2021
Policy to close small schools forces children to walk far to get to school