Zimbabwe Wants Digital Payments to Build Trust in Its Newest Currency. Why Technology Alone Won’t Be Enough to Save the Zig
Zimbabwe’s goal should be to promote wider adoption of the local currency, not to use technology to force it.

MyZA
News, Directory, Events and Other Stuff
Zimbabwe’s goal should be to promote wider adoption of the local currency, not to use technology to force it.
National Small Business Chamber (NSBC) Africa and TransUnion Africa today officially launched Access to Finance™, a national Small Medium Enterprise (SME) funding initiative created and powered by NSBC Africa to help South African SMEs better understand their funding requirements and connect qualifying businesses with participating funders aligned to their funding needs.
Mike Anderson, Founder & CEO of NSBC Africa launched Access to Finance™ at the opening of The Business Show: Africa 2026 at the Sandton Convention Centre in Johannesburg, where thousands of entrepreneurs, business owners, executives, funders, leading brands and business decision makers are gathering for two days of business growth and opportunity.
Access to Finance™ forms part of NSBC Africa’s broader national business growth ecosystem and its longstanding mission to help entrepreneurs and SMEs access the opportunities, resources, funding and connections they need to build sustainable and successful businesses.
At its core, the initiative seeks to address one of the most persistent challenges facing South African entrepreneurs and growing businesses: accessing the right finance, at the right stage, from the right funding provider. For many SMEs, the funding landscape can be complex and difficult to navigate. Businesses may not know whether they are funding-ready, what type of finance best suits their needs or which funding providers are most relevant to their circumstances.
FUNDING. FAST. SIMPLE.
Through a structured digital journey, Access to Finance™ helps SMEs better understand their funding requirements and, where qualifying criteria are met, connects them with participating funders whose solutions are aligned to their business and funding needs. The goal is to create a simpler pathway to business finance, while supporting greater participation by qualified SMEs within the broader finance ecosystem.
Rather than simply providing businesses with a list of funders, Access to Finance™ is designed to improve alignment between SME funding needs and appropriate funding opportunities, helping entrepreneurs take a more informed and targeted approach to accessing finance.
TransUnion is the exclusive Credit Bureau Partner to Access to Finance™, working alongside NSBC Africa in support of the shared vision of strengthening SME participation within South Africa’s finance ecosystem.
CREATING GREATER VISIBILITY AND CONNECTIVITY
A central part of the Access to Finance™ vision is improving the connection between South African SMEs and the organisations that finance business growth. By helping businesses better understand their readiness for finance, before engaging participating funders, the initiative aims to create a more efficient journey for both SMEs and funding providers.
Speaking at the official opening of The Business Show: Africa and the launch of Access to Finance™, Lee Naik, CEO & Regional President of TransUnion Africa, addressed the importance of strengthening the environment in which South African SMEs can better understand their financial position, become more visible within the finance ecosystem and connect with appropriate opportunities for growth.
“Small businesses are one of South Africa’s most important engines of growth and job creation, yet too many still struggle to access the funding they need to start, sustain and scale their operations. At TransUnion Africa, we see data visibility and access to information as powerful enablers of financial inclusion and business growth. By helping businesses establish a stronger, more transparent financial profiles, we can support lenders in making more informed decisions and expand access to credit for viable enterprises,” says Naik.
A NEW ERA OF ACCESS TO FINANCE
According to Anderson, improving the connection between SMEs and appropriate finance has the potential to unlock significant business growth. “South Africa does not lack entrepreneurial ambition. What many businesses lack is a simpler, more effective way to navigate the funding landscape and connect with the right finance opportunities.
Access to Finance™ has been created to help change that. We want to make the journey smarter, simpler and more connected, helping funding-ready SMEs get closer to the finance they need to grow. When more viable businesses can access appropriate funding, they can invest, expand, create jobs and build stronger, more sustainable businesses. That is the bigger vision behind Access to Finance™.”
CREATED AND POWERED BY NSBC AFRICA
Access to Finance™ is created and powered by NSBC Africa, a non-profit organisation that has championed entrepreneurship and SME growth for more than 18 years. Through its national ecosystem of initiatives, platforms, partnerships and events, NSBC Africa works to connect entrepreneurs and small businesses with the opportunities, knowledge, solutions, funding and connections they need to build sustainable and successful businesses.
Adds Naik, “We are proud to partner with NSBC Africa on Access to Finance™ and see this as an important platform for connecting entrepreneurs with funding opportunities and help them realise their growth potential.”
The initiative represents an important next step in that mission, bringing together NSBC Africa’s SME ecosystem, technology, partnerships and funding relationships to create a smarter and more connected pathway between entrepreneurs seeking finance and participating funding providers.
The vision is clear: help more SMEs become finance-ready, connect with relevant funding opportunities and take the meaningful steps towards sustainable business growth.
It is disappointing and unacceptable that the Bitou Municipality dragged its feet in appointing a new tourism service provider. Consequently, the Plett Arts Festival cannot take place this year. The mandate of the Plettenberg Bay Tourism Association lapsed on 30 June 2026. The Municipality undertook to award the new tourism services tender by 1 July, […]
The post Bitou’s administrative foot-dragging robs Plettenberg Bay of its Arts Festival appeared first on Freedom Front Plus.
Healthcare teamwork is taught through western models. Ubuntu offers an African approach that could improve collaboration and patient care worldwide.
The commission said mismanagement, infrastructure neglect and systemic corruption to blame
With immediate effect the CircumQ device may not be used on boys aged ten to 14
Eskom’s plans to cut power to 14 indebted municipalities expose a deepening crisis in South Africa’s state-owned electricity provider.
About 600,000 beneficiaries are still without the new card
When a child has a disability, especially an intellectual one, a father’s involvement often shifts in complex ways.
The Freedom Front Plus (VF Plus) urged the Finance Department of the Mogale City Local Municipality (Krugersdorp, Magaliesburg, Muldersdrift), which is responsible for issuing utility bills, to ensure that the information reflected on the bills is correct and complete. The bills for March do not reflect VAT nor the billing period. Consequently, these bills are […]
The post Mogale City’s utility bills riddled with errors yet again appeared first on Freedom Front Plus.
Residents have struggled to access water for almost two months
South Africa’s largest gold producer went to court to win the right to use its own solar power.
About 80 learners from the Enon farming community have been without scholar transport this year
Villagers and livestock have been drinking from rancid river water
Residents of the Emakhazeni Local Municipality (Belfast, Machadodorp, Dullstroom, Waterval Boven) are experiencing serious financial and other hardships due to the flawed roll-out of new smart electricity meters. The Freedom Front Plus (VF Plus) is aware of numerous complaints about prepaid units running out too fast, and power being disconnected suddenly and without any warning. […]
The post Emakhazeni should explain smart meter chaos appeared first on Freedom Front Plus.
Mahikeng judge ruled that nine non-profit organisations providing child protection services must have their funding restored within ten days
The Tshwane Metro has to take decisive action to make the Tjaart van Vuuren municipal swimming pool in Villieria functional and accessible again as soon as possible. The swimming pool has been closed for the past three weeks, because the Metro’s chlorine supplier failed to deliver the necessary chemicals. The closure comes at the most […]
The post Tjaart van Vuuren swimming pool closes due to lack of chlorine appeared first on Freedom Front Plus.
Treating the White Army as synonymous with South Sudan’s opposition serves a political purpose.
ProEthics and its director Dr Janette Minnaar tried to stop us publishing this article
The safety and track record of the CircumQ devices has been questioned
SANCO accused of threats and intimidation at MyCiTI bus depot; denies any link to extortion
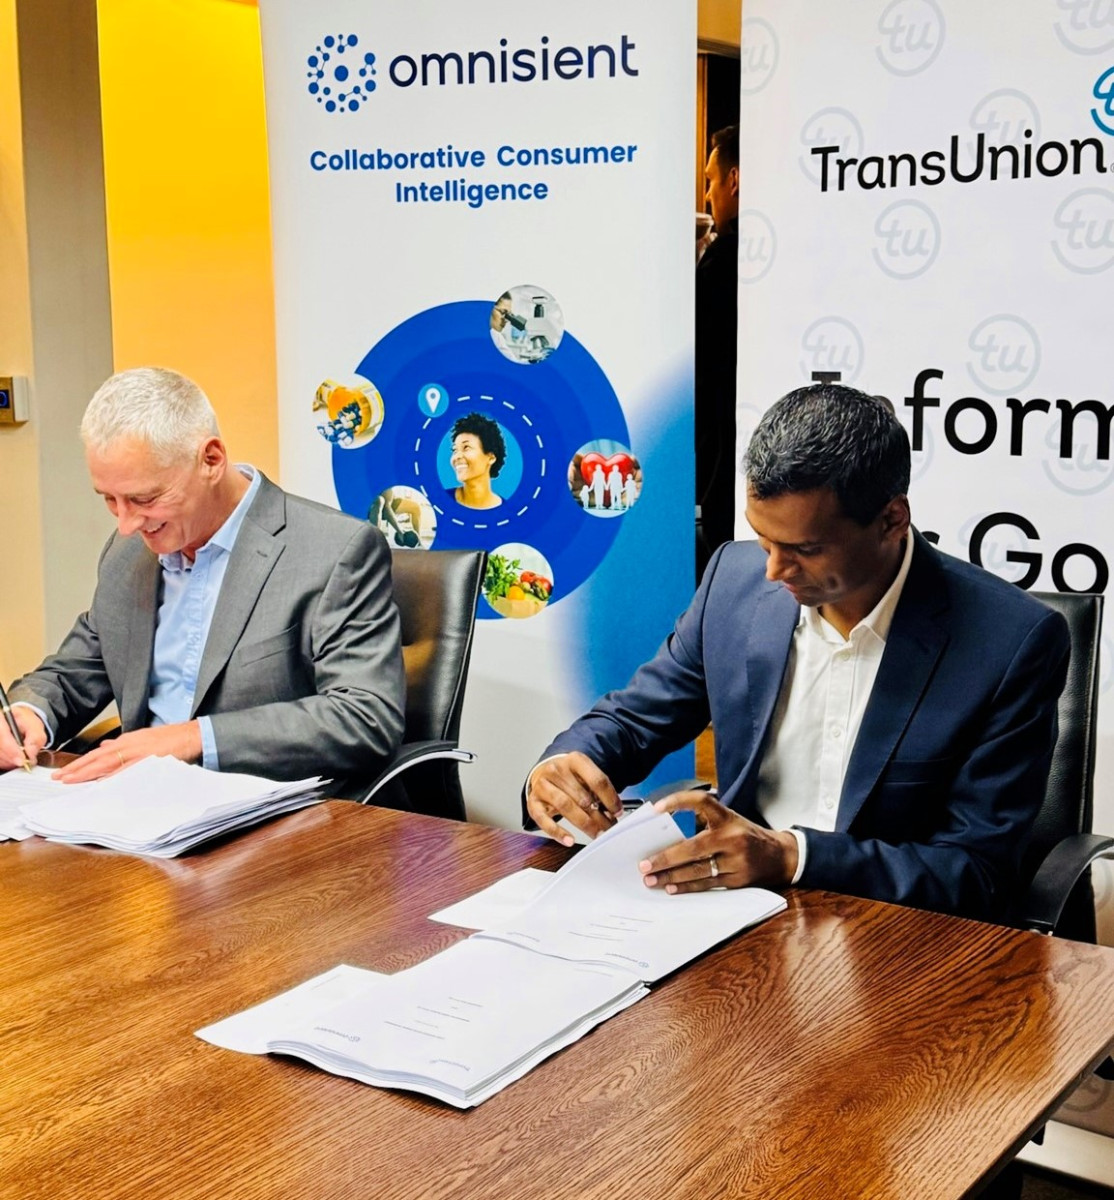
TransUnion today announced a minority investment and broader strategic partnership with Omnisient, a South Africa-founded FinTech operating internationally that offers a privacy-preserving data collaboration and advanced analytics platform. The Omnisient platform empowers businesses to safely access high-value consumer data ecosystems and rapidly integrate alternative data sets to drive intelligent decision-making. As part of the investment, a TransUnion representative will join Omnisient’s board of directors.
“The Omnisient platform allows multiple clients to use built-in advanced analytical tools to simultaneously evaluate the utility of diverse data sets, identifying those that deliver measurable value. Through this collaboration, TransUnion expects to gain access to a broader range of alternative data sources and privacy preservation capabilities. By accelerating the integration of high-impact data into our ecosystem, we intend to enhance existing solutions and develop new, market-relevant products that better meet the evolving needs of our customers,” said Lee Naik, Regional President/ CEO of TransUnion Africa.
“Traditional data models often fail to reflect the lived realities of African consumers, leaving millions without access to credit and the opportunities it enables,” said Naik. “Financial inclusion is central to unlocking economic growth across the continent. That’s why we’re committed to leading with bold, African-born solutions designed to see the unseen and serve the credit invisible by integrating alternative data sets alongside traditional credit data in ways that reflect uniquely African contexts and realities. By incorporating non-traditional indicators of financial behaviour, this approach broadens access to credit and helps us reach more underserved communities. We believe accelerating the adoption of alternative data is critical to closing the credit gap at scale, enabling faster, fairer and more inclusive access to financial services for millions across the continent."
“Our privacy-preserving data collaboration platform brings financial services and consumer brands together, allowing them to discover, validate and commercialise new alternative sources of consumer behavioural and transactional data without having to exchange sensitive personal information,” said Jon Jacobson, co-founder and group CEO of Omnisient. “This data allows financial institutions to make better risk decisions with more confidence and security, unlocking the potential to grow financial inclusion for hundreds of millions of people around the world.”
This collaboration marks a natural progression in TransUnion’s strategy to expand financial inclusion across Africa. By leveraging privacy-enabled alternative data sets through Omnisient’s platform, TransUnion intends to strengthen its ability to help address the challenge of bringing an estimated 500 million* financially excluded Africans into the formal financial ecosystem. By responsibly harnessing alternative data at scale, TransUnion sees the opportunity to bring millions of new-to-credit and credit-underserved consumers across Africa into the financial mainstream. This enables individuals to begin building a credit profile, many for the first time, laying the foundation for long-term economic empowerment. It’s a powerful demonstration of TransUnion’s commitment to using Information for Good® to drive measurable impact at scale: expanding access to credit, unlocking economic potential and reshaping the future of finance across Africa.
Global demand is rising for alternative data solutions that protect privacy, build trust and unlock value. Omnisient’s platform meets this need with technology that enables secure, privacy-preserving data collaboration. Instead of transferring raw data, Omnisient uses tokenised keys to represent personal information in the data set, ensuring privacy is maintained throughout the process. As a leading provider in Africa of secure, many-to-many data connectivity between banks, financial institutions and third-party sources, Omnisient is driving innovation in data collaboration.
*Source: The Global Findex Database 2021
Every industry has its myths, and the short-term insurance environment is no exception: leading industry players plan their growth strategies around perceptions of a limited pool of customers, focusing mostly on pricing strategies to attract new business, and finding ways to avoid consumers perceived as too risky.
The best way to confirm or ‘bust’ industry myths is to test them through experiments and data analysis to reveal the truth – and that’s exactly what TransUnion South Africa did with data it holds in the short-term insurance sector.
“South African consumers remain under pressure despite recent interest rate cuts, making this an opportune moment for insurers to rethink their customer acquisition and retention strategies – and to challenge the truisms they’ve relied on in recent years,” said Schalk Fischer, insurance lead at TransUnion South Africa. “To drive better outcomes, insurers must evolve and adapt their strategies to respond to changing market conditions, drawing on risk-management solutions that feature unique data and advanced analytics.”
Myth 1: With stagnant total policy volumes, the only way for an insurer to grow is to win customers from other insurers.
In assessing all new short-term insurance policies taken out between April 2024 and March 2025, TransUnion found that only 17% of new policies were opened by consumers moving to another insurer. Another 37% involved ‘policy splitting’, where consumers moved cover of one of their assets to a new provider, but did not move their whole portfolio.
This means that roughly 54% of new policies are opened due to churn – a significant portion, but certainly not the overwhelming portion that many insurers believe it to be.
“This data shows key growth opportunities for insurers lie among consumers who are new to insurance. In fact, 33% of new policies opened during the time of the study were taken out by consumers who had not had an insurance premium in the previous 24 months,” Fischer said. “While the short-term industry will always be very competitive, there are growth opportunities outside of working aggressively to attract customers from other insurers.”
Myth 2: Loyalty in short-term insurance is dead. Price is the primary variable.
With many consumers scrambling for cost savings, price is perceived to be the most important differentiator between insurers, along with being seen as the main reason that consumers leave one insurer for another.
TransUnion’s analysis showed that 13% of insured consumers who cancel their insurance eventually return to their original insurance provider over time, without switching to another insurer in the interim.
This brand loyalty is fairly consistent between different distribution channels: 9% for banks’ insurance offerings, 11% for brokers, and 14% for direct insurers.
“These findings highlight that, while insurance pricing is certainly a leading consideration among consumers, it is evident that brand loyalty is still a driving factor,” Fischer said. “Marketing and acquisition strategies clearly focus on price, but there’s a greater than expected opportunity to build loyalty that will either retain customers or encourage them to return to brands they have trusted before.”
Myth 3: The new-to-insurance segment is small and only includes risky younger consumers.
TransUnion’s analysis revealed that one in three (33%) consumers who took out policies between April 2024 and March 2025 were new to insurance – they did not have short-term insurance payments linked to their identity number in the previous 24 months.
However, this doesn’t necessarily mean that all newly insured consumers were uninsured before. Some may have previously been covered under their partner or spouse, and later separated their insurance portfolios, or they could have been young adults who sought their own cover after being included in their parents’ policies.
“These findings show that insurers need to expand the scope of how they segment their target audiences, as new-to-insurance consumers are not always who they’re perceived to be,” Fischer adds.
The analysis revealed additional insights into consumers taking out a policy for the first time. Only 6% were aged 18 to 24 years – perceived to be the riskiest consumers – while the greatest portion of these consumers (36%) were aged 25 to 35 years, followed by 36 to 45 year olds, who took out 25% of new policies. It’s clear, then, that consumers aged 25 to 45 present the greatest opportunity for insurers.
In overlaying loyalty data with these findings, it emerged that only 1% of 18 to 24 year olds shopped around for a better deal once they were granted cover, while less than a quarter (24%) of 25 to 35 year olds shopped around. However, consumers aged 36 to 45 showed the greatest propensity to shop around for a better deal, with 29% taking on that challenge.
The myth is officially busted: opportunities for growth lie well beyond young consumers who have only just reached eligibility to apply for their own short-term insurance policies.
“While the short-term insurance market is perhaps not growing at the rate that many insurers would like, our analysis shows that it’s far from stagnant. Clear segmentation along with careful risk management and profitability assessments can help providers acquire lower-risk, higher-value customers across diverse groups of potential customers,” Fischer said. “While price remains a significant driver among consumers, other variables continue to play a meaningful role in building customer loyalty.”
Content producers get away with fake news and clickbait