• Skip to main content
  • Skip to header right navigation
  • Skip to after header navigation
  • Skip to site footer
MyZA

MyZA

News, Directory, Events and Other Stuff

  • Social Media
  • Sport
  • World News
  • Home
  • Submit News
  • Directory
  • Events
  • Stratlec
  • TFSA
  • News
    • APO
    • Today’s Sport News
    • Todays Social Media and Tech Headlines
    • Today’s World News
    • Today’s SA Financial News
  • Contact
You are here: Home / Archives for demand

demand

18 December 2025

South Africa’s Auto Market Shows Signs of Recovery as Used Vehicle Demand Rises

Location: Business
  • Used vehicle financing outpaces new car financing, with a ratio of 1.56 to 1 as affordability remains a key driver
  • New vehicle finance agreements grow by 12.7% YoY, despite economic uncertainty
  • South Africa reaches a milestone of 1,000+ battery electric vehicle (BEV) sales in 2024, with PHEV and HEV sales growing over 60% YoY

The latest TransUnion South Africa Vehicle Pricing Index (VPI) for Q4 2024 reveals a cautiously optimistic outlook for the country’s automotive sector, with improving economic conditions encouraging consumer confidence while affordability challenges continue to shape purchasing decisions.

Key insights from the report indicate a continued shift towards used vehicles, with financing for pre-owned vehicles outpacing new car financing at a ratio of 1.56 to 1, up from 1.23 in Q4 2023. Meanwhile, new vehicle prices increased by 1.7% due to supply chain constraints and production costs, while used vehicle prices declined by 2.8%, making them a more attractive option for cost-conscious buyers.

Despite these challenges, new vehicle finance agreements grew by 12.7% year-over-year (YoY), with Gen X and Millennials accounting for 67% of new agreements*.

“South Africa’s automotive sector is navigating a complex landscape, balancing economic improvements with persistent affordability challenges,” says Marcia Mayaba, Sales Vice President, Auto Information Services at TransUnion South Africa. “The demand for used vehicles continues to grow, while we’re also seeing an increasing shift towards alternative financing and ownership models, such as leasing and car subscriptions, particularly among younger consumers.”

Used Vehicles Dominate, While New Car Market Seeks Stability

The Q4 2024 VPI report highlights a strong preference for used vehicles, with financing activity significantly outpacing new vehicle sales. This shift is largely driven by affordability concerns, as inflationary pressures and high vehicle prices continue to impact consumer purchasing decisions.

The used-to-new financing ratio increased to 1.56 in Q4 2024, reflecting a clear trend toward more budget-friendly alternatives. At the same time, new vehicle registrations grew by 14.4% YoY, supported by improved economic conditions and rising consumer confidence.

The Future of South Africa’s Auto Market: EV Growth and Digital Financing

Looking ahead, the report highlights the rising potential of electric vehicles (EVs) in South Africa, signalling a significant shift in consumer interest and market dynamics. The country reached a milestone of over 1,000 battery electric vehicle (BEV) sales in 2024, a small but significant step in a market still dominated by petrol and diesel vehicles. While EVs represent a fraction of total sales, the 60% year-over-year growth in hybrid (HEV) and plug-in hybrid (PHEV) sales signals a gradual shift in consumer interest toward more sustainable options.

The introduction of more affordable EV models priced under R1 million, such as the BYD Dolphin and Seal, is expected to accelerate adoption in 2025, making EV ownership more accessible to a broader segment of the market. However, affordability remains a key barrier, with high upfront costs and concerns around charging infrastructure limiting mainstream adoption.

“EV adoption in South Africa is gaining momentum, but for this growth to be sustained, industry players must collaborate to make ownership more accessible," says Mayaba. "With the right financial products, infrastructure expansion, and increased consumer awareness, EVs have the potential to reshape South Africa’s automotive landscape in the years to come.”

Financing Trends and Alternative Ownership Models Gain Momentum

The report also reveals an evolving vehicle financing landscape, with leasing, subscriptions, and rent-to-buy agreements gaining traction as consumers seek more flexible and cost-effective solutions.

For the first time, the Q4 2024 VPI report explores the impact of e-Hailing, leasing, and car subscriptions on the South African auto market. While outright vehicle ownership remains dominant, alternative mobility solutions are becoming increasingly relevant. The report indicates that leasing and subscription-based models are particularly appealing to Millennials and Gen Z consumers, who prioritise affordability and flexibility over long-term ownership commitments.

Additionally, e-Hailing continues to serve as a supplementary transport solution rather than a direct competitor to vehicle ownership. According to recent data from inDrive, an international ride-hailing service, 21.1% of South Africans make us of e-hailing services, reflecting the growing popularity of these transportation alternatives. However, the majority of users still aspire to own a vehicle in the long term. To address affordability constraints and credit access challenges, leasing and rent-to-buy options are emerging as viable alternatives, offering consumers flexible solutions that align with their financial situations.

While lower-value finance agreements (under R250,000) declined, a growing share of financed vehicles now falls within the R250,000 to R750,000 range. This shift suggests that while affordability remains a concern, consumers are prioritising flexible financing solutions and adjusting their purchasing behaviour to align with available credit and economic conditions

“The traditional model of vehicle ownership is evolving,” adds Mayaba. “While outright ownership remains a key aspiration, younger generations are increasingly exploring flexible mobility solutions that align with their financial realities and lifestyle preferences.”

As South Africa’s automotive sector continues to evolve, the interplay between affordability, alternative financing models, and emerging technologies like EVs will shape its future. While used vehicles remain the preferred choice for many consumers, the growth in digital financing and the introduction of more accessible EV models signal an industry on the brink of transformation. Collaboration among industry players, financial institutions, and policymakers will be key to ensuring sustainable growth and greater accessibility for all consumers. With the right innovations and strategies, the sector is well-positioned to adapt to changing market dynamics and drive long-term success.

Read the latest TransUnion VPI Q4 2024 report here.

ENDS

Notes to Editors:

* Gen X (born 1965-1980), Millennials (born 1981-1996) and Gen Z (born 1997-2012)

The TransUnion South Africa Vehicle Pricing Index (VPI) tracks vehicle pricing trends across new and used markets, integrating data from SACRRA and industry-leading sources.

For more information, visit: www.transunion.co.za
Read moreSouth Africa’s Auto Market Shows Signs of Recovery as Used Vehicle Demand Rises
17 December 2025

South Africa’s Lenders Adopted Prudent Risk Strategies to Drive Growth in Q4 2024

Location: Business
  • Card issuers rewarded performing existing cardholders with credit limit increases, but offered lower credit limits to new cardholders
  • Consumers increasingly turned to non-bank lenders for personal loans
  • Vehicle loan originations increased for the second consecutive quarter, indicating optimism for the sector

According to TransUnion’s (NYSE:TRU) Q4 2024 South Africa Industry Insights Report, the country’s credit card issuers have adapted their acquisition strategies to enable prudent growth, while effective risk management has led to a decline in account-level delinquencies. During Q4 2024, credit card issuers reduced the average credit card limit on new accounts by 3.9% year-over-year (YoY), while at the same time they increased credit limits on existing credit cards[1] by 5.0%.

The limit increase observations were prominent among prime plus consumers (+4.1% average credit limit increase) and super prime[2] consumers (+1.8%). As a result of higher line access and consumers continuing to leverage credit cards to meet financial and transactional needs, total outstanding balances rose by 7.8% YoY. These insights are echoed in TransUnion South Africa’s Q4 2024 Consumer Pulse Report, where 13% of consumers responded that they had increased their usage of available credit.

An improving performance picture, as observed since Q2 2022, continued as delinquencies (measured as accounts 90 days or more past due) decreased by 34 basis points (bps) YoY during Q4 2024. This trend shows that South African consumers have been able to maintain their credit card payment obligations, while leveraging their cards to navigate the continued high cost of living that has put pressure on disposable income.

“Lenders who are sustaining growth and profitability are drawing on enhanced risk attributes to stimulate a greater share of spend and wallet by identifying consumers who are likely to use credit lines judiciously,” said Lee Naik, CEO of TransUnion Africa. “At a time when new account acquisition is costly, enabling lower-risk consumers to re-engage with their inactive cards, or to extend the use of existing cards, will encourage prudent growth and enable customer loyalty.”

Personal loan lenders target younger borrowers

While personal loan originations from traditional banks declined by 6.2% YoY in Q4 2024, personal loan originations from non-bank lenders increased by 13.9% YoY. Non-bank personal loan originations among Gen Z[3] consumers grew by 48.5% YoY, with this cohort accounting for 15.5% of all non-bank originations.

Non-bank personal loan originations increased YoY across all risk tiers (except for the super prime risk tier, where originations declined by a marginal 1.0% YoY), with the greatest increase seen among prime borrowers (16.1%). However, bank personal loans declined across all risk tiers YoY, except for subprime, where they increased by 6.0% YoY.

Banks are expanding their personal loan offerings to a greater proportion of subprime borrowers. Among bank personal loans, the share of subprime borrowers increased from 53% in Q4 2023 to 58% in Q4 2024, with the share of near prime borrowers remaining consistent across the year. There were minimal YoY fluctuations across the remaining risk tiers. In contrast, the distribution across risk tiers for non-bank personal loans remained consistent over the last two quarters of 2024.

The personal loans market continues to be dominated by younger borrowers, although the total share of originations by borrowers aged 45 and younger did decline marginally in 2024. Seventy-five percent of bank personal loans were granted to Gen X and Millennial customers during Q4 2024, down from 78% one year prior, while 70% of non-bank personal loans were granted to the same age group in Q4 2024, compared to 72% one year prior. At the same time, both lender types are growing their portfolio among the youngest Gen Z borrower group, with 19% of bank personal loans going to Gen Z borrowers in Q4 2024, up from 16% one year prior, and 16% of non-bank personal loans going to these consumers in Q4 2024, up from 12% one year prior.

With respect to credit performance, bank personal loan account-level delinquencies at 90+ days past due dropped by eight bps YoY to 26.6%, while non-bank personal loan delinquencies increased by 452 bps to 40.6%.

“Non-bank personal lenders have a more tolerant risk appetite than banks, and they are responding positively to market demand across age groups and risk tiers,” says Naik. “Lenders that maintain rigorous risk assessment practices that enable greater and earlier prediction of risk, offer education on how to use and manage credit, and empower younger consumers to build their credit profiles, will ensure the continued sustainability of the personal loan market.”

Vehicle loan market continued its recovery path

The vehicle loans market showed encouraging signs of continued growth, as origination volumes increased by 9.6% YoY, and average new loan amounts grew by 1.4%. The greatest growth in originations was observed among Gen Z consumers, where originations grew by 27.9%, although their share of total new finance agreements remains relatively low compared to older age groups. This is the second consecutive quarter in which total vehicle loan originations grew YoY, with the last increase in origination volumes before these two increases having been in Q3 2022. Given the 0.25 bps decrease in interest rates as of November 2024 and a positive outlook for consumer confidence, the vehicle loan market is expected to continue this recovery trend.

These positive trends were also evident in the Q4 2024 TransUnion South Africa Vehicle Pricing Index, that revealed a growing share of financed vehicles within the R250,000 to R750,000 price range. This shift suggests that, while affordability may still be a concern, consumers are prioritising flexible financing solutions and adjusting their purchasing behaviour to align with available credit and economic conditions.

“While the two recent interest rate decreases were just 25 basis points each, the significant increase in new vehicle loan originations indicates that South Africans are becoming more optimistic about their financial futures,” says Naik. “While vehicle ownership is aspirational for many individuals, it’s also the key to unlocking growth for entrepreneurs, and the owners of micro and small enterprises, all of whom are the engines of economic growth in South Africa.

“As part of our drive to expand financial inclusion, TransUnion has included a wide range of alternative data into our scoring solutions, so that more South Africans are more visible in our risk scoring models, in turn creating the platform for them to access finance for the first time.”

 Table 1: Key South African Credit Market Metrics (Q4 2024 vs Q4 2023)

Product

YoY origination growth

Serious account-level delinquency rate*

YoY basis points (bps) change in delinquency rate

Credit card

5.6%

12.0%

-33 bps

Bank personal loan

-6.2%

26.6%

-8 bps

Non-bank personal loan

13.9%

40.6%

452 bps

Clothing accounts

-4.0%

26.4%

-143 bps

Retail instalment

14.9%

27.5%

-204 bps

Retail revolving

11.9%

14.5%

-500 bps

Home loans

-13.2%

7.1%

26 bps

Vehicle finance

9.6%%

4.8%

13 bps

 *Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears


  • [1] Credit card accounts that are currently open and active in the portfolio.
  • [2] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).
  • [3] TransUnion age distribution: Gen Z (Born 1995 – 2010); Millennials (Born 1980-1994); Gen X (Born 1965-1979); Baby Boomers (Born 1946-1964
Read moreSouth Africa’s Lenders Adopted Prudent Risk Strategies to Drive Growth in Q4 2024
11 December 2025

South Africa’s Consumer Credit Market Sees Targeted Growth in Key Products, Despite New High in Personal Loans Delinquencies

Location: Business
  • Credit card originations rose by 30.7% as demand grew, with below prime originations up by one third year-over-year (YoY)
  • Vehicle finance originations grew significantly YoY, indicating growing momentum in the automotive industry
  • Non-bank personal loans saw highest delinquency rate since previous high point in Q2 2021

According to TransUnion’s (NYSE:TRU) Q1 2025 South Africa Industry Insights Report, the growth in originations of new credit cards, at 30.7% year-over-year (YoY), far outstripped growth for other consumer credit products during the first quarter of the year.

Strong growth in credit cards was driven, in part, by lenders extending cards to more below prime[1] borrowers than they did one year ago – up 33.1% YoY. Subprime and near prime borrowers accounted for 69.3% of credit card originations, up from 64.3% one year earlier. At the same time, lenders looked to actively manage the increased risk profile of borrowers by limiting the average credit limit on new credit cards – down 13.1% YoY.

Growth is likely to remain buoyant in the South African credit card market, with 33% of respondents to TransUnion’s recent Q1 2024 Consumer Pulse Survey saying that they planned to apply for a new credit card in the next 12 months.

Credit card average account balances increased by 7.1% YoY, although lenders’ default concerns may have been eased by the 20-basis point (bps) decrease in account-level delinquencies* over the same period, standing at 12.3% in Q1 2025.

“While inflation has dropped to the low end of the South African Reserve Bank’s target range during Q1 at close to 3%, South Africans are still experiencing financial pressures from prior price increases, turning to credit to help them make ends meet,” says Ayesha Hatea, director of research and consulting at TransUnion. “Despite these strains, consumers have increasingly prioritised keeping their credit cards in good standing, as they likely want to ensure access to the ongoing liquidity that this credit product provides.”

Vehicle loans grew at double-digit rate

The vehicle loans market continued to show encouraging signs of continued growth, as origination volumes increased by 11.6% YoY in Q1 2025. The average value of new loans also rose by 3.0% over the same period.

The highest growth rate continued to be among Gen Z[2] consumers, up 28.5% YoY. Within the Gen Z cohort, 62% of new vehicle loans were opened by consumers in the oldest subgroup in this generation, aged 26 to 29 years. This trend suggests that older Gen Z consumers are becoming increasingly active in the vehicle finance market, likely as they reach key life stages such as career stability and household formation. While this group is not necessarily New-to-Credit, their growing share of originations highlights a valuable opportunity for lenders to engage younger, upwardly mobile consumers.

In contrast, the share of vehicle loans declined across all other generations, with the exception of Gen X, where volumes remained relatively stable. This reinforces the importance of targeting older Gen Z consumers as a key growth segment in the vehicle finance space.

With a 0.25% repo rate cut announced by the South African Reserve Bank (SARB) in January followed by another in May, demand for vehicle loans is likely to remain buoyant, with more than one fifth (22%) of South Africans surveyed in the TransUnion Q1 Consumer Pulse Survey indicating that they intend to take out a new car loan or lease in the next 12 months.

“With vehicle ownership is a priority due to limited public transport offerings, buying a vehicle is often a first step into secured credit for young professionals,” said Hatea. “Vehicle finance often requires relatively small deposits, and flexible financing options can be negotiated to make monthly repayments more affordable. Borrowers don’t need as extensive a credit history to purchase a vehicle as they do to buy a home. Successfully managing a vehicle loan demonstrates financial responsibility, which can strengthen future home loan applications.”

Personal loans leveraged for meeting monthly expenses

During the first quarter of the year, consumers also increasingly turned to personal loans as strategic tools to achieve their financial objectives, with originations growing for both bank and non-bank personal loan lenders – up 2.7% and 11.5% YoY, respectively. Demand for personal loans will likely continue, with 35% of surveyed South Africans saying that they intend to apply for a personal loan in the next 12 months.

However, non-bank lenders may yet have to refocus their risk management strategies in the coming months as more than two in five (41.3%) of South Africans who hold one of these loans – 83.9% of whom are below prime borrowers – being three months or more in arrears during Q1 2025. This is a 520-basis point (bps) YoY increase and is the highest delinquency rate for this product since the previous high of 39.1% in Q2 2021.

The delinquency rate among non-bank personal loans was 15 percentage points higher than delinquencies on bank personal loans, where below prime borrowers comprise 71.8% of the bank personal loans book.

“South Africans are increasingly turning to low-value personal loans with shorter repayment terms to manage their monthly expenses. However, persistently high delinquency rates — particularly among non-bank personal loans — indicate that many consumers are under significant financial pressure and struggling to meet their loan commitments,” says Hatea. “As lenders respond to growing demand for this type of credit, it’s essential they align their growth strategies with prudent risk management to ensure long-term sustainability.”

Home loans remain under pressure

Home loans were the only sector to experience a decline in originations in Q1 2025, down 10.8% YoY. Although originations fell across all risk tiers, loans to prime and above consumers saw a particularly sharp decline, down 21.1% YoY. This continues the downward trend in home loan growth observed since Q1 2020, with exception of a moderate YoY increase between Q1 2022 and Q1 2023.

“The fact that even prime consumers are pulling back from the housing market is a clear signal that affordability remains a significant barrier,” said Hatea. “This trend has implications not only for the credit market, but also for broader economic activity tied to home ownership and property development.”

As the housing finance sector continues to soften, lenders may need to reassess their strategies. This includes rethinking product design and pricing, as well as how they connect with younger consumers and first-time buyers, in order to reignite demand in a segment that has traditionally served as a foundation of secured lending.

 Table 1: Key South African Credit Market Metrics (Q1 2025 vs Q1 2024)

Product

YoY origination growth

Serious account-level delinquency rate*

YoY basis points (bps) change in delinquency rate

Credit card

30.7%

12.3%

-20 bps

Bank personal loan

2.7%

26.3%

14 bps

Non-bank personal loan

11.5%

41.3%

520 bps

Clothing accounts

7.6%

25.9%

-294 bps

Retail instalment

16.0%

27.1%

-138 bps

Retail revolving

5.4%

14.9%

-350 bps

Home loans

-10.8%

7.4%

19 bps

Vehicle finance

11.7%

5.4%

-1 bps

 *Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears


[1] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).

[2] TransUnion age distribution: Gen Z (Born 1995 – 2010); Millennials (Born 1980-1994); Gen X (Born 1965-1979); Baby Boomers (Born 1946-1964

Read moreSouth Africa’s Consumer Credit Market Sees Targeted Growth in Key Products, Despite New High in Personal Loans Delinquencies
11 December 2025

Botched Permits Spoil Crayfish Season Start

Location: News

West Coast small-scale fishers demand answers from fisheries department

Read moreBotched Permits Spoil Crayfish Season Start
11 December 2025

How African Consumers Set Global Trade Trends in the 1800s

Location: News

Africa’s ‘new consumer class’ isn’t new; in the 1800s the continent called the tune for European factories.

Read moreHow African Consumers Set Global Trade Trends in the 1800s
10 December 2025

Foot-And-Mouth Disease Out of Control

Location: News

While the economy is slowing down and South Africans look forward to spending the festive season with family, livestock farmers face a bleak festive season as foot-and-mouth disease causes massive financial losses. The Department of Agriculture is dragging its feet with enforcing legislation while more and more farmers are struggling to keep their heads above […]

The post Foot-and-mouth disease out of control: Dark times ahead for livestock farmers appeared first on Freedom Front Plus.

Read moreFoot-And-Mouth Disease Out of Control
10 December 2025

Kimberley’s Big Hole of Municipal Failure

Location: News

Sol Plaatje municipality’s speaker and municipal manager were recently appointed despite tainted records

Read moreKimberley’s Big Hole of Municipal Failure
9 December 2025

Protesters Demand Cape Town Holocaust Centre Recognise Genocide in Gaza

Location: News

The vigil also marks International Day of Commemoration and Dignity of the Victims of the Crime of Genocide

Read moreProtesters Demand Cape Town Holocaust Centre Recognise Genocide in Gaza
9 December 2025

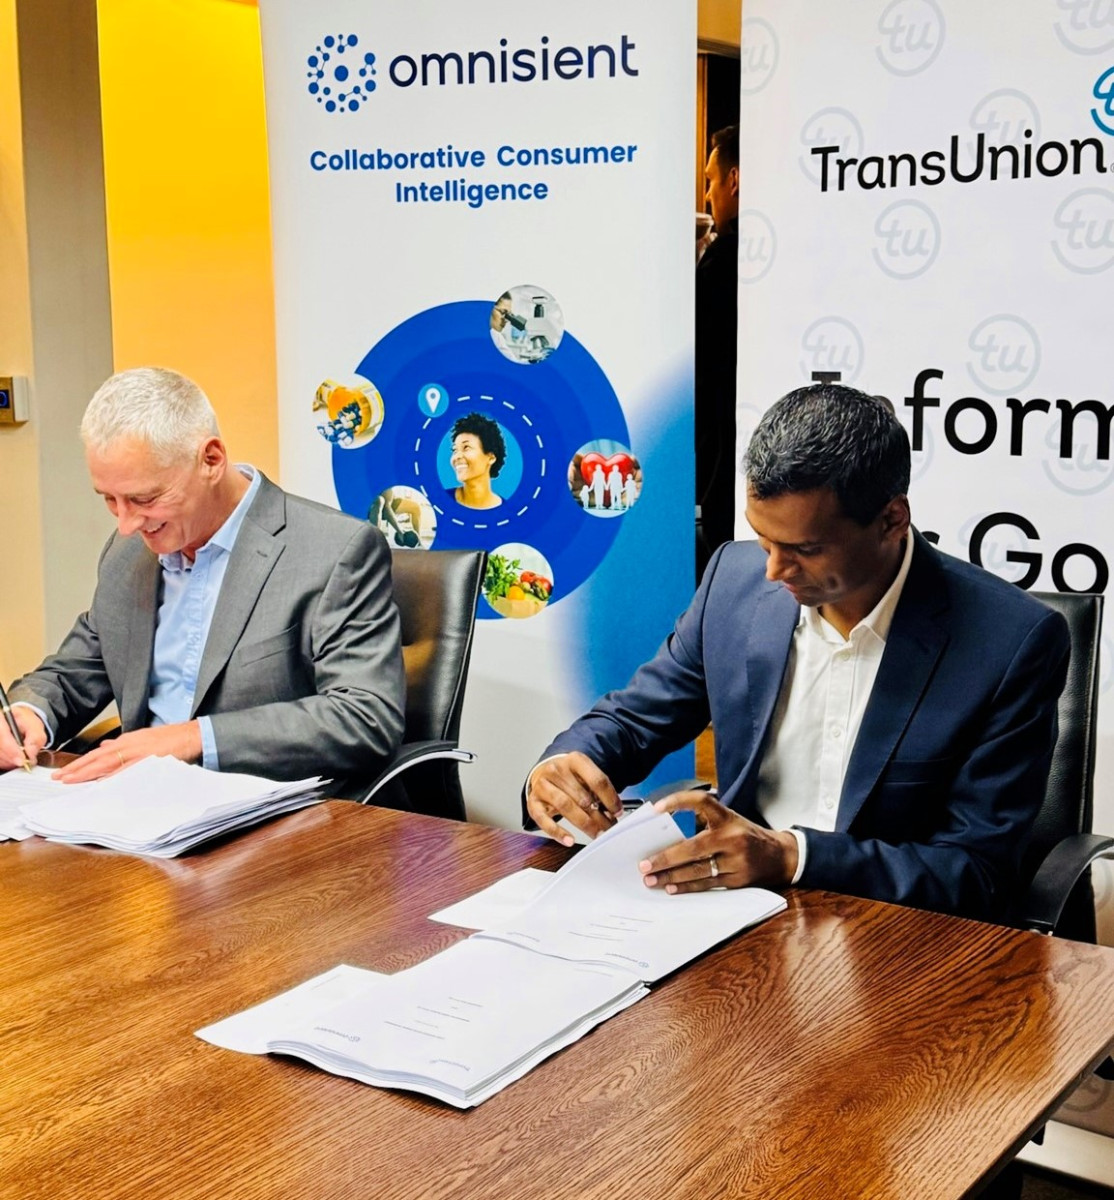
TransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption

Location: Business

TransUnion today announced a minority investment and broader strategic partnership with Omnisient, a South Africa-founded FinTech operating internationally that offers a privacy-preserving data collaboration and advanced analytics platform. The Omnisient platform empowers businesses to safely access high-value consumer data ecosystems and rapidly integrate alternative data sets to drive intelligent decision-making. As part of the investment, a TransUnion representative will join Omnisient’s board of directors.

“The Omnisient platform allows multiple clients to use built-in advanced analytical tools to simultaneously evaluate the utility of diverse data sets, identifying those that deliver measurable value. Through this collaboration, TransUnion expects to gain access to a broader range of alternative data sources and privacy preservation capabilities. By accelerating the integration of high-impact data into our ecosystem, we intend to enhance existing solutions and develop new, market-relevant products that better meet the evolving needs of our customers,” said Lee Naik, Regional President/ CEO of TransUnion Africa. 

“Traditional data models often fail to reflect the lived realities of African consumers, leaving millions without access to credit and the opportunities it enables,” said Naik. “Financial inclusion is central to unlocking economic growth across the continent. That’s why we’re committed to leading with bold, African-born solutions designed to see the unseen and serve the credit invisible by integrating alternative data sets alongside traditional credit data in ways that reflect uniquely African contexts and realities. By incorporating non-traditional indicators of financial behaviour, this approach broadens access to credit and helps us reach more underserved communities. We believe accelerating the adoption of alternative data is critical to closing the credit gap at scale, enabling faster, fairer and more inclusive access to financial services for millions across the continent."

“Our privacy-preserving data collaboration platform brings financial services and consumer brands together, allowing them to discover, validate and commercialise new alternative sources of consumer behavioural and transactional data without having to exchange sensitive personal information,” said Jon Jacobson, co-founder and group CEO of Omnisient. “This data allows financial institutions to make better risk decisions with more confidence and security, unlocking the potential to grow financial inclusion for hundreds of millions of people around the world.”

This collaboration marks a natural progression in TransUnion’s strategy to expand financial inclusion across Africa. By leveraging privacy-enabled alternative data sets through Omnisient’s platform, TransUnion intends to strengthen its ability to help address the challenge of bringing an estimated 500 million* financially excluded Africans into the formal financial ecosystem. By responsibly harnessing alternative data at scale, TransUnion sees the opportunity to bring millions of new-to-credit and credit-underserved consumers across Africa into the financial mainstream. This enables individuals to begin building a credit profile, many for the first time, laying the foundation for long-term economic empowerment. It’s a powerful demonstration of TransUnion’s commitment to using Information for Good® to drive measurable impact at scale: expanding access to credit, unlocking economic potential and reshaping the future of finance across Africa.

Global demand is rising for alternative data solutions that protect privacy, build trust and unlock value. Omnisient’s platform meets this need with technology that enables secure, privacy-preserving data collaboration. Instead of transferring raw data, Omnisient uses tokenised keys to represent personal information in the data set, ensuring privacy is maintained throughout the process. As a leading provider in Africa of secure, many-to-many data connectivity between banks, financial institutions and third-party sources, Omnisient is driving innovation in data collaboration.

*Source: The Global Findex Database 2021

Read moreTransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption
8 December 2025

South Africans Signal Cautious Confidence as Financial Habits Evolve

Location: Business
  • TransUnion’s Q2 2025 Consumer Pulse Study reveals strategic shifts in saving, borrowing, and fraud defence, with younger generations leading the way
  • 75% of South Africans expect their income to rise, but nearly 39% anticipate missing at least one bill or loan payment
  • 45% of Gen Z and 39% of Millennials plan to apply for credit, leading a shift toward more proactive financial habits
  • 58% of consumers were targeted by fraud in Q2, with many responding by strengthening their digital security

South African consumers are responding to ongoing financial pressures with increasing intent and vigilance. While inflation, high interest rates and job market uncertainty continue to weigh on household budgets, the latest TransUnion Consumer Pulse Study for Q2 2025* reveals a population adjusting not just defensively, but proactively. From rethinking spending and saving to becoming more discerning about credit and fraud, South Africans are adopting behaviours that suggest a shift toward long-term financial resilience, especially among younger generations.

“South Africans are showing resilience with purpose,” said Ayesha Hatea, director of research and consulting at TransUnion. “They’re not simply reacting to pressure, they’re taking charge, rebalancing their finances and protecting their future.”

Mixed Incomes, Bold Adjustments

While there are some positive signs, many households are still experiencing fluctuations in their income. In the second quarter, 21% of consumers said their household income had decreased, while 38% reported an increase. A majority of respondents (75%) are hopeful that their earnings will increase in the next year. However, this confidence exists alongside financial challenges, with nearly 39% of consumers reporting that they expect they might miss at least one bill or loan payment in the near future.

This financial pressure is driving noticeable changes in how people manage their money. More than half of consumers (54%) trimmed back on non-essential expenses like dining out, entertainment and travel. Many are also taking steps to strengthen their financial security; 31% paid down debt faster, 24% put more into emergency savings or stokvels and 37% planned to increase their retirement or investment savings.

Generational Differences Define the Shift

While overall behaviours are trending positive, the evolution is not uniform across age groups. Younger consumers, particularly Gen Z (ages 18-28) and Millennials (29-44) are emerging as drivers of this transformation. They are more likely to apply for credit, monitor their credit reports frequently and adopt security tools like multi-factor authentication.

Forty-five percent of Gen Z respondents and 39% of Millennials indicated they plan to apply for or refinance credit in the next year, compared to just 27% of Gen X (45-60) and 15% of Baby Boomers (61+). They are also the most engaged in monitoring their credit monthly and believe that access to alternative data, such as rental or Buy Now Pay Later (BNPL) payment histories, would improve their credit scores.

“Younger South Africans are embracing financial tools with growing confidence,” Hatea added. “They’re more comfortable with digital platforms, increasingly aware of how their financial choices affect their long-term goals, and, as a result, are more proactive about managing their credit.”

Cautious Credit Intent Amid Access Concerns

While 92% of consumers believe access to credit is important to achieving their financial goals, only 36% intend to apply for credit in the coming year, a figure that has remained stable since Q1. This cautious demand reflects continued uncertainty around employment, income and affordability.

Consumers favour unsecured lending, with credit cards (30%), personal loans (28%) and BNPL services (25%) attracting the most interest. Interest in secured lending remains comparatively low, with only 22% planning to apply for vehicle finance and 19% expressing interest in home loans.

Still, barriers remain. Nearly half (48%) of consumers said they had considered applying for credit but ultimately decided not to. The main reasons were income/ employment status (30%), high borrowing costs (29%) and concerns about their credit history (27%). Overall, 45% of consumers believed they would be approved if they applied for credit. While this figure reflects general sentiment, optimism tends to be higher among those who actively monitor their credit, suggesting a link between financial awareness and confidence.

Digital Fraud on the Rise, but So Is Awareness

As digital engagement grows, so does the threat of fraud. In Q2 2025, 58% of South Africans reported being targeted by fraud schemes, a decrease from the previous quarter (61%) with 13% confirming they had fallen victim. The most common scams included gift card or money transfer scams (33%), phishing (31%), smishing (30%) and third-party seller scams (28%).

Consumers are responding with heightened vigilance in response to cyber security concerns. A majority (59%) changed their passwords, 39% checked their credit reports and 25% added multi-factor authentication. Gen Z and Millennials were the most likely to take protective action, a likely result of both their greater exposure to digital platforms and higher awareness of evolving scam tactics. Alarmingly, 21% of consumers said they took no action at all, often citing uncertainty about what to do. This highlights the ongoing need for stronger cybersecurity and fraud education, and accessible protection tools.

“Consumers are trying to keep pace, but the threat landscape is evolving quickly,” said Hatea. “What we need now is a national conversation, one that gives all South Africans the knowledge and resources to protect their identities in a digital-first world.”

A Financial Turning Point

The Q2 2025 Consumer Pulse Study reveals a country making deliberate financial choices in the face of uncertainty. South Africans are shifting from survival mode to a more balanced, future-focused financial mindset. While challenges remain, the direction is clear; consumers are becoming more selective in how they spend, more strategic in how they borrow and more vigilant in how they protect themselves.

“At TransUnion, we believe these shifts represent not just resilience, but growth,” concluded Hatea. “South Africans are taking ownership of their financial journeys and in doing so, they’re laying the groundwork for lasting stability and inclusion.”

Consumers can get their free annual credit report from TransUnion here.

* This online survey of 922 adults was conducted May 5–25, 2025

Read moreSouth Africans Signal Cautious Confidence as Financial Habits Evolve
8 December 2025

Week of Terror Against Children in Cape Town

Location: News

The GOOD Party is heartbroken and outraged by the week of unprecedented violence that has claimed the lives of several children and left others wounded across Cape Town.

The post GOOD PARTY CONDEMNS WEEK OF TERROR AGAINST CHILDREN IN CAPE TOWN appeared first on For Good.

Read moreWeek of Terror Against Children in Cape Town
6 December 2025

Nkandla Villagers Demand a Police Station

Location: News

Mfongosi Satellite Police Station has been abandoned

Read moreNkandla Villagers Demand a Police Station
5 December 2025

5 Smart Strategies to Manage Debt and Interest Rates in 2025

Location: Business

South Africans are learning to live and thrive in a financially uncertain world. The latest TransUnion Consumer Pulse Study (Q2 2025) shows that while 39% of households expect they may miss at least one bill or loan payment, many are actively reshaping their habits to build financial resilience.

Encouragingly, 31% of consumers are paying down debt faster, 24% are boosting emergency savings, and 37% plan to increase their retirement or investment contributions. These trends suggest that South Africans are not only reacting to pressure, but they are also taking proactive steps to protect their financial futures.

Ayesha Hatea, director of research and consulting at TransUnion South Africa shares some tips and tricks to help you manage debt and interest rates more effectively in 2025:

1. Pay Off High-Interest Debt First

The study highlights that more consumers are accelerating debt repayment and for good reason. Credit cards and personal loans often carry the highest interest rates when looking at consumers with multiple products in their wallet.

“In a high-interest environment, every rand you pay off today saves you from paying more interest tomorrow,” says Hatea

Tip: List your debts and focus on paying off the ones with the highest rates first, while keeping up with minimum payments on the rest.

2. Be Strategic About Borrowing

Access to credit remains crucial. 92% of South Africans believe it’s important for achieving their goals. Yet only 36% intend to apply for credit in the next year, reflecting caution amid high borrowing costs and income uncertainty.

If you do borrow, make it purposeful. The study found that demand is strongest for credit cards (30%), personal loans (28%), and Buy Now, Pay Later services (25%) but remember, these are all unsecured products that can quickly become costly if not managed well.

Tip: Compare interest rates, fees, and repayment terms before taking on new credit. Avoid unnecessary borrowing for short-term wants when rates are high or if you aren’t sure you’ll be able to make the necessary repayments.

3. Build a Safety Net, Even Small Steps Count

Nearly one in four consumers (24%) increased contributions to emergency savings or stokvels in Q2. In addition, 37% plan to grow their retirement or investment savings in the coming months.

Tip: Start with a modest, consistent contribution to an emergency fund, even R200 a month can create a buffer that reduces reliance on credit when life throws curveballs.

4. Strengthen Your Financial Awareness

The study shows that 70% of South Africans check their credit reports at least quarterly, with Gen Z and Millennials leading the way. Those who actively monitor their credit tend to feel more confident and have a better understanding of their overall financial commitments.

Tip: Check your credit report regularly, track your score, and make sure all information is accurate. Awareness is power when it comes to negotiating better credit terms.

5. Protect Yourself Against Digital Fraud

Fraud remains a real risk with 58% of South Africans saying they were targeted by scams in Q2, and 13% fell victim. Younger generations are more likely to adopt safeguards like multi-factor authentication, but 21% of consumers took no action at all.

Tip: Use strong, unique passwords, enable two-factor authentication, and monitor your accounts for unusual activity. Protecting your identity is just as important as protecting your money.

The Bottom Line

The TransUnion Consumer Pulse Study shows that while many households remain under pressure, South Africans are becoming more selective in how they spend, strategic in how they borrow, and vigilant in how they protect themselves.

“Resilience comes from balance: focus on responsible spending and borrowing, reduce costly or unsustainable debt, and build savings to protect against future shocks,” Ayesha concludes.

By taking small, deliberate steps today, households can better manage debt and interest rate uncertainty and build financial stability for tomorrow.

Read more5 Smart Strategies to Manage Debt and Interest Rates in 2025
4 December 2025

TRC Commission: Does Jacob Zuma Have Something to Hide?

Location: News

Former President Jacob Zuma’s eleventh-hour demand that Justice Sisi Khampepe be withdrawn as chairperson of the Commission investigating alleged political interference in the prosecution of apartheid era crimes compounds the very injustice the Commission was set up to probe.

The post TRC COMMISSION: DOES ZUMA’S APPLICATION FOR CHAIR’S RECUSAL IMPLY HE HAS SOMETHING TO HIDE? appeared first on For Good.

Read moreTRC Commission: Does Jacob Zuma Have Something to Hide?
3 December 2025

Sudan’s Protesters Built Networks to Fight a Tyrant – Today They Save Lives in a War

Location: News

Sudan’s neighbourhood committees represent a unique blend of political and practical action. They mobilise for change while addressing immediate community needs.

Read moreSudan’s Protesters Built Networks to Fight a Tyrant – Today They Save Lives in a War
3 December 2025

South Africa’s Automotive Market Accelerates to 11-Year High as Value Brands and Younger Buyers Drive Momentum

Location: Business
  • 111 697 new passenger vehicles sold in Q3 – up 23.4% year-on-year, the highest quarterly total since 2014
  • Chinese brands captured a record 15%+ market share, growing almost nine times faster than the market average
  • Passenger-vehicle exports rebounded 4.1% year-on-year, powered by a 63.7% September surge to a six-year high

South Africa’s automotive market shifted into top gear in the third quarter of 2025, posting its strongest sales performance in more than a decade as greater macro-economic stability, easing interest rates and a firmer rand supported renewed consumer demand. According to TransUnion’s Q3 2025 Mobility Insights Report, total new-passenger-vehicle sales reached 111 697 units, 23.4% higher year-on-year (YoY), while new vehicle inflation dropped to a record low of 1.5% (since tracking began in 2008), creating one of the most competitive pricing environments in recent memory.

“Affordability and choice are redefining South Africa’s automotive landscape,” says Lee Naik, CEO TransUnion Africa. “Consumers are seeking greater value and flexibility and manufacturers that meet this demand through innovation and pricing discipline are winning the race for growth.”

Affordability Drives Record Growth and Market Realignment

Although established OEMs returned to positive growth in Q2 and Q3 2025, the market’s transformation is being led by Chinese manufacturers expanding nearly nine times faster than the overall market, with YoY growth of 89% in Q2 and 88% in Q3.

Their combined share has quadrupled since 2021 to more than 15%, powered by competitively priced, feature-rich SUVs and sedans that appeal to cost-conscious yet tech-savvy buyers. Top-performing value brands YoY included JAC (67% volume increase), GWM (54%), Mahindra (42%) and Chery (35%), while BMW (27%) proved that premium marques can still thrive by combining desirability with strong product pipelines.

“This isn’t a short-term surge, it’s a structural reset,” adds Naik. “The success of value-driven models shows how affordability, technology and trust are now the true levers of brand growth in South Africa.”

Younger and High-Income Buyers Sustain Demand

Despite surging sales, TransUnion’s recent Consumer Pulse Survey shows a modest easing in purchase intent, with the share of respondents likely to buy a vehicle in the next three months declining from 19% in Q2 to 17% in Q3. The report suggests that current sales momentum is being driven primarily by pent-up demand, dealer incentives and fleet renewals, rather than broad-based consumer confidence.

Purchase behaviour also remains sharply segmented across both age and income groups. Younger consumers continue to lead intent, with 21% of Gen Z and 19% of Millennials planning to buy a vehicle in the next three months, compared to 13% of Gen X and 8% of Baby Boomers. From an income perspective, high-income households earning R200 000 or more per month show the strongest intent at 34%, while middle- and lower-income consumers remain significantly more cautious in their purchasing outlook.

Electrification: A Tale of Price and Generation

Internal-combustion vehicles (ICE) remain the single largest category in consumer purchase intent, accounting for 42% of consumer preference, while interest in hybrid (39%) and plug-in hybrid (24%) models is steadily increasing. The shift toward electrification is most pronounced among Gen Z consumers, with 55% favouring hybrids and 32% considering battery-electric vehicles (BEVs).

This generational shift toward greener technology is evident among high-income buyers, with 75% considering plug-in hybrids, driven primarily by their perceived affordability. In contrast, preference for ICE vehicles remains largely affordability-based among lower-income segments. Higher budgets within affluent households enable greater consideration of hybrid electric (HEV), plug-in hybrid (PHEV), and battery electric vehicles (BEV), reinforcing an emerging “electrification divide.” This dynamic presents a significant opportunity for OEMs and financiers to tailor product offerings and financing strategies to meet the distinct needs of different age and income segments.

Connected Cars: Data Becomes the New Engine

Q3’s Mobility Insights Report special feature, The Connected Road, explores how connected-car technology is transforming mobility. Connectivity is now standard in most post-2015 vehicles, enabling real-time navigation, predictive maintenance, remote access, and advanced safety systems. Yet global data warns of “connectivity fatigue”: Over three quarters (76%) of drivers internationally don’t subscribe to connected services, mainly due to cost.

Naik says: “South Africa has a chance to leapfrog global missteps by focusing on value-adding applications, safer driving, cheaper insurance and smarter maintenance rather than gimmicks.”

Exports Rebound and Dealer Confidence Climbs

Passenger-vehicle unit exports rose 4.1% YoY after a steep Q2 contraction, driven by a 63.7% September surge that lifted shipments to a six-year high. Meanwhile, the RMB/BER Motor Traders Confidence Index advanced to 54, marking its second net-positive reading of 2025 and notably placing it above the neutral 50-point mark, which signals growing dealer optimism amid sustained sales momentum and improving export conditions.

Balancing Value and Transformation

The convergence of affordability, segmentation, electrification, and connectivity signals a pivotal shift in the automotive industry. “The future belongs to brands and financiers that master both the value-driven present and the connected, electrified future,” concludes Naik. “Data-led insight will be the bridge that connects today’s strategies with tomorrow’s innovation

Read the full TransUnion South Africa Q3 2025 Mobility Insights Report here.

Read moreSouth Africa’s Automotive Market Accelerates to 11-Year High as Value Brands and Younger Buyers Drive Momentum
2 December 2025

South African Automotive Market: Recovery Gains Traction but Headwinds Persist

Location: Business
  • New passenger sales rose 22.5% year-on-year, the strongest volumes since 2014
  • Chinese automakers expanded their market share to nearly 15%, up from just 3.1% in 2022
  • Passenger-vehicle exports contracted sharply, down 24.6% amid weaker global demand and new US tariffs

TransUnion’s latest Mobility Insights Report shows South Africa’s automotive market building momentum in 2025, supported by a favourable interest rate environment, record-low new-vehicle inflation, and liquidity from the two-pot pension reform. While recovery is underway, the outlook remains fragile, with affordability constraints and export headwinds threatening longer-term growth.

Supportive Shifts, But Growth Remains Fragile

The South African Reserve Bank has cut interest rates five times since September 2024 and inflation has returned to the lower end of the 3-6% band1, providing households with some relief. Consumer confidence has improved among middle- and higher-income groups, although low-income consumers continue to face pressure from food and electricity costs2.

“These macro shifts provide short-term support to the vehicle market, but momentum is likely to taper in 2026 without further reforms,” said Lee Naik, CEO of TransUnion Africa.

Affordability And Value Drive a Surge

Passenger car sales broke through the 35,000-unit ceiling for the first time in years, with July and August 2025 marking the strongest volumes since 2014. According to Naamsa, new passenger car sales grew 22.5% year-over-year (YoY) in Q2, fuelled by lower borrowing costs, aggressive OEM incentives and the entry of new value-focused brands.

Chinese automakers continued their rapid growth, expanding market share from 3.1% in 2022 to nearly 15% in Q2 2025. Their affordable, tech-rich SUVs and expanding dealer networks are reshaping competition, forcing legacy OEMs to rethink pricing, features, and model cycles. Toyota retained overall leadership, with Suzuki securing second place for the second consecutive quarter.

“Improved affordability, aggressive incentives and growing demand for value brands, alongside modest support from two-pot withdrawals, helped sustain momentum through 2025. However, as interest rates remain elevated and credit conditions tighten, and the two-pot effect normalises, growth is expected to moderate in 2026, with export risks and rand volatility adding uncertainty,” said Naik.

Diverging Trends: New vs. Used Vehicle Demand

NaTIS data shows new registrations rising 20% YoY in Q2 2025, led by Northern Cape, Free State and Northwest. In contrast, used registrations declined by 1.4%, reflecting pressure in that segment.

Across all vehicle sales, the Used-to-New Vehicle Registration Ratio rose to 3.2 in Q2, up from 2.5 in Q1, indicating a quarter-on-quarter increase in the relative share of used vehicle registrations. However, this remains below the 3.8 ratio seen through much of 2024, suggesting that new vehicles have regained some ground YoY. While used vehicles continue to dominate overall registrations, the market has shifted slightly back toward new vehicles compared to last year. This nuanced divergence presents opportunities for OEMs and dealer networks, while independent used dealers continue to face headwinds.

Exports Slump Amid Global Shocks

While domestic momentum improves, passenger vehicle exports fell 24.6% in Q2 2025 due to softer global demand and new US tariffs of up to 30%. Premium models, heavily reliant on the US and European markets, are under pressure, raising concerns for production, jobs, and investment.

Two-pot Withdrawals: Targeted Liquidity with Visible Impact

The September 2024 two-pot retirement reform injected liquidity into households, with evidence from the Bureau of Market Research suggesting a direct impact on mobility demand3, particularly in the used car market. While withdrawals were generally insufficient to fund deposits for new vehicles, they provided meaningful support to affordability-driven used vehicle purchases.

The reform is offering short-term relief rather than long-term wealth extraction, with withdrawals largely used for deposits, consumption, or debt repayment. Generational differences are evident: Millennials (aged 29 to 44) and younger Gen X (aged 18 to 28) are the most active claimants, while Baby Boomers withdraw minimally. Repeat withdrawals are becoming more common, suggesting both ongoing financial strain and the emergence of a recurring source of liquidity for entry-level and mid-market segments4.

“Two-pot withdrawals were not the only factor lifting sales,” noted Naik. “But the timing, scale and claimant profile suggest they acted as a meaningful catalyst for incremental used-car purchases.”

What Industry Players Should Do Next

Looking ahead, TransUnion advises that OEMs, dealers and lenders recalibrate strategies to balance domestic opportunities with external risks. Industry participants should align campaigns with liquidity cycles, planning promotions and stock availability around expected two-pot withdrawal windows.

Affordability must remain the priority, with a sharpened focus on value brands, certified pre-owned vehicles, and models that deliver a strong total cost of ownership. Financing solutions should also evolve, offering deposit support, trade-in boosters, and more flexible terms, while carefully monitoring repayment behaviour to manage post-purchase risk.

At the same time, leveraging data-driven insights, integrating credit and registration analytics to identify liquidity-sensitive buyers, preapprove customers, and track repayment performance, will be critical for sustaining growth in an uncertain environment.

“South Africa’s auto market is regaining momentum, but it’s a fragile recovery,” said Naik. “Those who time offers to policy-driven liquidity, sharpen affordability, and manage risk proactively will be best placed to capture growth.”

Read the full TransUnion South Africa Mobility Insights Report here.

ENDS

Notes to Editors: The Q2 2025 release is the second edition of the TransUnion South Africa Mobility Insights Report, formerly known as the Vehicle Pricing Index. The rebranded report now captures broader consumer, financing, and insurance insights across the mobility ecosystem.

Sources:

1 South African Reserve Bank (SARB)

2 TransUnion-South-Africa-CCI-Report-H2-2025-V9.pdf

3 Two-pot-claims-and-credit-data-FINAL.pdf

4 FAnews: Majority of two-pot withdrawals in the new tax year are repeat withdrawals; Moneyweb: Two-pot withdrawal: repeat claims surge; and Moneyweb, Two-pot payouts surge to R57B, with 4m withdrawals to date.

Read moreSouth African Automotive Market: Recovery Gains Traction but Headwinds Persist
2 December 2025

Johannesburg’s Landfills Fill Up

Location: News

They also want to be included in the City’s solutions. But there are obstacles.

Read moreJohannesburg’s Landfills Fill Up
1 December 2025

Nigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea

Location: News

Stronger public investment is needed so families are not forced to pay privately for basic education.

Read moreNigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea
1 December 2025

Understaffed, Crumbling Eastern Cape Clinic Cannot Meet Demand

Location: News

New temporary structure set to cost R1.2-million and take two years to complete

Read moreUnderstaffed, Crumbling Eastern Cape Clinic Cannot Meet Demand
1 December 2025

South Africa’s Credit Market Expanded During Q2 2025 Amid Eased Interest Rates and Shifting Consumer Risk

Location: Business
  • Millennial consumers drove significant new credit card growth, although new card limits dropped significantly
  • Vehicle asset finance growth trend continued, with more than two thirds of loans originated by Gen Z and Millennial consumers
  • Eased interest rates drove year-over-year growth in home loan originations, although affordability pressures may be impacting performance

South Africans responded to a more favourable interest rate environment during Q2 2025, leading to increased new account originations across most consumer credit products, particularly for credit cards and vehicle finance. Home loan activity also showed signs of recovery, as consumers felt more confident in committing to longer-term credit obligations. Retail revolving loans were the exception, with origination volumes declining despite growth in balances.

These are some of the findings of TransUnion’s Q2 2025 South Africa Industry Insights Report, which also found that South Africans were managing their credit better, as delinquencies improved across most consumer credit products during the quarter.

Credit Card Market Continued Upward Trajectory

Credit card originations increased by a robust 36.5% year-over-year (YoY), underscoring this product’s relevance as a flexible financial tool for consumers seeking convenience and/or liquidity in what remains a challenging economic environment. Millennials (born 1980 to 1994) drove this growth, with originations in this cohort making up 47.6% of all originations in the period.

Lenders seeking to expand market share continued to extend credit to consumers in higher-risk prime and below risk tiers[1], with originations to subprime consumers increased by 49.2% YoY. They balanced this growth among higher-risk borrowers with smaller credit limits. The average credit limit on new credit cards decreased by 19.5% YoY during the quarter.

Delinquency trends showed mixed results. Credit card balance-level delinquency rose slightly to 18.1%, up 13 basis points (bps) YoY, indicating a marginal increase in overdue balances. In contrast, account-level delinquency rates declined by 32 bps YoY to 12.1%. This decline in account-level delinquency suggests that while some consumers accumulated larger balances, many were able to make payments to keep their accounts active.

“The latest credit cards trends reflect strategic credit use and disciplined repayment behaviour among a financially stretched borrower base,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “The combination of rising origination volumes and shrinking new credit lines suggests that lenders are working to balance growth with prudent risk management. Lenders may need to refine their segmentation strategies, enhance early warning systems, and tailor credit line management to sustain portfolio health while supporting customers’ financial needs.”

Vehicle Asset Finance Shows Continued Growth

Vehicle asset finance originations increased by 21.0% YoY in Q2 2025, and average new loan amounts increased by 3.5% while the number of active accounts increased by 2.1% YoY. Growth was mainly driven by Gen Z (aged 18 to 28) and Millennial (aged 29 to 44) consumers who accounted for 64.3% of originations.

Outstanding balances grew by 7.6% YoY, and average balances have increased by more than 30% over the last five years, reflecting both higher vehicle prices and a sustained trend toward longer loan terms, which slows loan balance paydown rates. Loan terms granted during Q2 2025 averaged 74 months, up from 73 months in Q2 2024 and 72 months in Q2 2023. Longer loan terms, while slowing balance paydown, result in lower monthly payment amounts, which help consumers manage monthly cash flow in a high-cost environment.

Younger consumers are beginning to look for more ways to enter the vehicle market, including taking advantage of more cost-effective imported vehicles. However, 65% of vehicle finance originations were made by repeat buyers during Q2 2025, suggesting that access to vehicle finance remains limited for new entrants. At the same time, lenders need to be mindful of rising risk levels: in the second quarter of 2025, 44% of new-to-vehicle finance consumers fell into the subprime risk tier. These trends highlight the need for lenders to design credit products that support younger buyers, while ensuring responsible credit practices are upheld.

Account-level delinquencies for vehicle asset finance improved by 24 bps YoY to 5.1%, demonstrating that repayment behaviour for this product remained relatively stable, and that the overall risk profile of this portfolio is improving.

“For vehicle finance lenders, the rise in originations alongside modest growth in loan amounts suggests an opportunity to support demand while maintaining portfolio discipline,” said Hatea. “The improvement in delinquency rates is encouraging, but ongoing monitoring will be essential as economic recovery remains uneven. Vehicle finance lenders may benefit from refining pricing models, reassessing vehicle segmentation strategies, and balancing growth with prudent risk management.”

Home Loan Market Responds Positively to Eased Interest Rates

Lower interest rates, moderating inflation and improved real wage growth led to stronger consumer sentiment, giving lenders an opportunity to re-engage with consumers seeking home loans. New home loan account originations increased by 6.8% YoY during Q2 2025, showing early signs of recovery after declines in growth over previous quarters.

Favourable interest rate conditions and enhanced credit access drove broader access to home ownership this quarter, with 51% of home loans granted to individuals taking a home loan for the first time — the highest proportion in over five years. Among these, 56% were Millennials and 24% were Gen Z.

Delinquency trends showed mild deterioration, with the account-level delinquency rate increased by 29 bps to 7.5%. These movements suggest that while the market is stabilising, repayment stress remains a concern.

“These trends indicate a home loan market that is stabilising, but not without risk,” said Hatea. “For home loan lenders, the uptick in originations presents an opportunity to re-engage with the market, but rising delinquency rates underscore the need for vigilance. Portfolio strategies may need to shift toward enhanced consumer profile assessments, proactive risk monitoring, and targeted engagement with borrowers showing early signs of strain. As the market navigates this transitional phase, balancing growth with resilience will be key.”

 Table 1: Key South African Credit Market Metrics (Q2 2025 vs Q2 2024)

Product

YoY origination growth

Serious account-level delinquency rate*

YoY basis points (bps) change in delinquency rate

Credit card

36.5%

12.1%

-32 bps

Bank personal loan

2.2%

25.9%

-72 bps

Non-bank personal loan

18.8%

41.3%

256 bps

Clothing accounts

6.5%

25.9%

-265 bps

Retail instalment

21.4%

25.5%

-238 bps

Retail revolving

-6.3%

14.9%

-251 bps

Home loans

6.8%

7.5%

29 bps

Vehicle finance

21.0%

5.1%

-24 bps

 *Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears


[1] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).

Read moreSouth Africa’s Credit Market Expanded During Q2 2025 Amid Eased Interest Rates and Shifting Consumer Risk
1 December 2025

Police Foil Mugging During Anti-crime March

Location: News

Residents from Manenberg and Gugulethu demanded better policing

Read morePolice Foil Mugging During Anti-crime March
1 December 2025

Rent Control Not Only Fails, It Entrenches Inequality

Location: News

The solution to housing affordability is to increase supply by building more housing

Read moreRent Control Not Only Fails, It Entrenches Inequality
29 November 2025

Creditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers

Location: Business

South Africa’s younger credit-eligible consumers present significant growth opportunities for lenders if they can overcome persistent market assumptions that currently shape risk appetite and acquisition strategies.

These assumptions include that younger consumers do not value credit, they are disengaged from the credit market, are irresponsible with debt, have low appetite for new credit, lack loyalty to lenders, and struggle to meet payment obligations.

They could also partly explain South Africa’s low 13% credit card market penetration among both Millennials (aged 29 to 44) and Gen Z (aged 18 to 28). Furthermore, Gen Z consumers adopt credit cards and personal loans at half the rate that Millennials did at the same age, suggesting limited growth for lenders as these consumers age.

“Our research suggests systemic barriers to credit access in South Africa, rather than a lack of demand,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “It also highlights that lenders have opportunities to innovate in product design, onboarding and education to empower these consumers to manage everyday expenses and unexpected financial needs as they progress towards achieving key life milestones.”

To challenge perceptions about younger consumers, TransUnion South Africa conducted a focused study[1] to test lenders’ perceptions, analysing participation, engagement and repayment behaviour among the country’s 4.3 million credit-active population aged 18 to 30.

Myth 1: Younger consumers don’t value credit

More than six in 10 (62%) younger consumers believe that access to credit is important to achieve their financial goals[2], with 76% saying that credit can give them access to new opportunities that could lead to a better quality of life. Younger consumers’ favourable perception of credit exceeds that of older consumers, 57% of whom believe access is important, and 71% of whom believe that access to credit can unlock new opportunities. However, less than a quarter (24%) of young consumers view credit as a risk to prudent financial management.

“Younger consumers increasingly see credit as a way to achieve their financial goals – even more so than older consumers,” Hatea said. “With most disagreeing that applying for credit signals poor financial management, it’s clear that opportunities exist for segment-focused products supported by financial literacy initiatives.”

Myth 2: Younger consumers are disengaged and don’t participate in the credit market

Nearly four in 10 (39%) young consumers feel that they have sufficient access to credit and lending products, with 49% believing that they would be approved for a credit product if they needed one.

It’s worth noting that, over time, consumers’ choice of credit product shifts. Reviewing credit card originations across a six-year period showed similar trends across time: 2% of 18 year old credit active consumers hold a credit card, compared to 19% of 30 year olds. Their participation in secured credit products increases with age, reaching parity with the general population by 30 and reflecting life stage realities like income, affordability and asset ownership, rather than disengagement.

“These shifts show that young consumers are engaged with the credit market, particularly with unsecured products, but their participation evolves across product types and life stages,” Hatea said.

Myth 3: Younger consumers are irresponsible in leveraging debt

Credit utilisation and average balances are well aligned with risk-based access that improves with age. At age 21, 95% of consumers are classified as subprime, dropping to 74% by age 30, reflecting a maturing credit profile.

Despite limited access, younger borrowers demonstrate measured usage: the average credit card balance at age 21 is R11,000, rising to R24,000 by age 30, while utilisation among near-prime consumers increases from 58% to 78% over the same age range.

“These trends highlight responsible engagement with credit and clearly refute the myth that younger consumers overextend their credit exposure, or are reckless with credit,” Hatea said. “As young consumers gain access to larger loan amounts, they move into better risk categories, reflecting greater lender trust in recognition of responsible repayment behaviour.”

Myth 4: Younger consumers have a low appetite for credit, and lack loyalty to lenders

While one third (33%) of the general population intends to apply for new credit within the next year, this increases to 45% for Gen Z consumers. Additionally, 36% of these consumers inquired about new credit over the six years studies, compared to 28% of all consumers. However, only 3.4% of younger consumers return to their first lender for new credit – similar to the 3.6% average across all consumers.

“The data shows that younger consumers do indeed have appetite for credit, while revealing that South African consumers in general are not particularly loyal to their credit providers,” Hatea said. “To build loyalty and retain younger consumers, lenders should invest in early-stage experiences, personalised engagement, and relevant products that build lasting relationships.”

Myth 5: Younger consumes struggle to keep up with their payment obligations

Interestingly, younger consumers show significantly lower risk of delinquency at 30 days past due (DPD) in the first year after opening credit cards, although this rises as they get older: there was a 17% delinquency rate among near prime 18 to 22 year olds, while 30 year olds displayed a 24% delinquency rate.

However, for non-bank loans and bank loans, younger consumers (18 to 24 years old) show slightly higher delinquency rates than older consumers, although younger consumers, especially those aged 23 to 25, perform better than the industry average. This indicates that lender type influences delinquency outcomes, and that younger borrowers may respond differently to the structure, support, or perception of a lender’s credit.

“Younger consumers are effectively managing their loans when compared to industry averages across most products,” said Hatea. “They’re not broadly higher risk, but they may be more vulnerable in certain lending contexts, particularly non-bank personal loans, where product design, support, or affordability may not be well aligned to their needs. Higher delinquency rates on non-bank personal loans can be addressed through early default detection tools.

“By focusing on education, wallet growth, loyalty, alternative data to measure risk, and proactive risk management, lenders can support younger consumers and drive long-term, sustainable growth among these consumers and in the broader credit market,” she said. “Well-managed credit can also be a catalyst for broader economic growth in South Africa.”


[1] TransUnion South Africa conducted a focused study to test lenders’ perceptions of consumers aged 18 to 30, analysing participation, engagement and repayment behaviour among the country’s credit-active population in this age group. Data was studied across four time frames (September in 2018, 2022, 2023 and 2024), and included age, risk score, open products in wallet, credit lines, average balances by product and credit utilisation at commencement of the study, new products opened, line assignments and opening loan amounts for six months, and delinquency rates on newly opened products for 12 months. These were compared to overall market averages to evaluate gaps and opportunities.

[2] According to TransUnion’s Q2 2025 Consumer Pulse Survey of 922 adults aged 18 or older, residing in South Africa conducted May 5–25, 2025 by TransUnion in partnership with third-party research provider, Dynata.

Read moreCreditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers
  • Previous
  • Page 1
  • Interim pages omitted …
  • Page 5
  • Page 6
  • Page 7
  • Page 8
  • Page 9
  • Interim pages omitted …
  • Page 22
  • Next

Copyright © 2026 · MyZA · All Rights Reserved · Powered by Stratlec Online