• Skip to main content
  • Skip to header right navigation
  • Skip to after header navigation
  • Skip to site footer
MyZA

MyZA

News, Directory, Events and Other Stuff

  • Social Media
  • Sport
  • World News
  • Home
  • Submit News
  • Directory
  • Events
  • Stratlec
  • TFSA
  • News
    • APO
    • Today’s Sport News
    • Todays Social Media and Tech Headlines
    • Today’s World News
    • Today’s SA Financial News
  • Contact
You are here: Home / Archives for Market

Market

11 December 2025

South Africa’s Consumer Credit Market Sees Targeted Growth in Key Products, Despite New High in Personal Loans Delinquencies

Location: Business
  • Credit card originations rose by 30.7% as demand grew, with below prime originations up by one third year-over-year (YoY)
  • Vehicle finance originations grew significantly YoY, indicating growing momentum in the automotive industry
  • Non-bank personal loans saw highest delinquency rate since previous high point in Q2 2021

According to TransUnion’s (NYSE:TRU) Q1 2025 South Africa Industry Insights Report, the growth in originations of new credit cards, at 30.7% year-over-year (YoY), far outstripped growth for other consumer credit products during the first quarter of the year.

Strong growth in credit cards was driven, in part, by lenders extending cards to more below prime[1] borrowers than they did one year ago – up 33.1% YoY. Subprime and near prime borrowers accounted for 69.3% of credit card originations, up from 64.3% one year earlier. At the same time, lenders looked to actively manage the increased risk profile of borrowers by limiting the average credit limit on new credit cards – down 13.1% YoY.

Growth is likely to remain buoyant in the South African credit card market, with 33% of respondents to TransUnion’s recent Q1 2024 Consumer Pulse Survey saying that they planned to apply for a new credit card in the next 12 months.

Credit card average account balances increased by 7.1% YoY, although lenders’ default concerns may have been eased by the 20-basis point (bps) decrease in account-level delinquencies* over the same period, standing at 12.3% in Q1 2025.

“While inflation has dropped to the low end of the South African Reserve Bank’s target range during Q1 at close to 3%, South Africans are still experiencing financial pressures from prior price increases, turning to credit to help them make ends meet,” says Ayesha Hatea, director of research and consulting at TransUnion. “Despite these strains, consumers have increasingly prioritised keeping their credit cards in good standing, as they likely want to ensure access to the ongoing liquidity that this credit product provides.”

Vehicle loans grew at double-digit rate

The vehicle loans market continued to show encouraging signs of continued growth, as origination volumes increased by 11.6% YoY in Q1 2025. The average value of new loans also rose by 3.0% over the same period.

The highest growth rate continued to be among Gen Z[2] consumers, up 28.5% YoY. Within the Gen Z cohort, 62% of new vehicle loans were opened by consumers in the oldest subgroup in this generation, aged 26 to 29 years. This trend suggests that older Gen Z consumers are becoming increasingly active in the vehicle finance market, likely as they reach key life stages such as career stability and household formation. While this group is not necessarily New-to-Credit, their growing share of originations highlights a valuable opportunity for lenders to engage younger, upwardly mobile consumers.

In contrast, the share of vehicle loans declined across all other generations, with the exception of Gen X, where volumes remained relatively stable. This reinforces the importance of targeting older Gen Z consumers as a key growth segment in the vehicle finance space.

With a 0.25% repo rate cut announced by the South African Reserve Bank (SARB) in January followed by another in May, demand for vehicle loans is likely to remain buoyant, with more than one fifth (22%) of South Africans surveyed in the TransUnion Q1 Consumer Pulse Survey indicating that they intend to take out a new car loan or lease in the next 12 months.

“With vehicle ownership is a priority due to limited public transport offerings, buying a vehicle is often a first step into secured credit for young professionals,” said Hatea. “Vehicle finance often requires relatively small deposits, and flexible financing options can be negotiated to make monthly repayments more affordable. Borrowers don’t need as extensive a credit history to purchase a vehicle as they do to buy a home. Successfully managing a vehicle loan demonstrates financial responsibility, which can strengthen future home loan applications.”

Personal loans leveraged for meeting monthly expenses

During the first quarter of the year, consumers also increasingly turned to personal loans as strategic tools to achieve their financial objectives, with originations growing for both bank and non-bank personal loan lenders – up 2.7% and 11.5% YoY, respectively. Demand for personal loans will likely continue, with 35% of surveyed South Africans saying that they intend to apply for a personal loan in the next 12 months.

However, non-bank lenders may yet have to refocus their risk management strategies in the coming months as more than two in five (41.3%) of South Africans who hold one of these loans – 83.9% of whom are below prime borrowers – being three months or more in arrears during Q1 2025. This is a 520-basis point (bps) YoY increase and is the highest delinquency rate for this product since the previous high of 39.1% in Q2 2021.

The delinquency rate among non-bank personal loans was 15 percentage points higher than delinquencies on bank personal loans, where below prime borrowers comprise 71.8% of the bank personal loans book.

“South Africans are increasingly turning to low-value personal loans with shorter repayment terms to manage their monthly expenses. However, persistently high delinquency rates — particularly among non-bank personal loans — indicate that many consumers are under significant financial pressure and struggling to meet their loan commitments,” says Hatea. “As lenders respond to growing demand for this type of credit, it’s essential they align their growth strategies with prudent risk management to ensure long-term sustainability.”

Home loans remain under pressure

Home loans were the only sector to experience a decline in originations in Q1 2025, down 10.8% YoY. Although originations fell across all risk tiers, loans to prime and above consumers saw a particularly sharp decline, down 21.1% YoY. This continues the downward trend in home loan growth observed since Q1 2020, with exception of a moderate YoY increase between Q1 2022 and Q1 2023.

“The fact that even prime consumers are pulling back from the housing market is a clear signal that affordability remains a significant barrier,” said Hatea. “This trend has implications not only for the credit market, but also for broader economic activity tied to home ownership and property development.”

As the housing finance sector continues to soften, lenders may need to reassess their strategies. This includes rethinking product design and pricing, as well as how they connect with younger consumers and first-time buyers, in order to reignite demand in a segment that has traditionally served as a foundation of secured lending.

 Table 1: Key South African Credit Market Metrics (Q1 2025 vs Q1 2024)

Product

YoY origination growth

Serious account-level delinquency rate*

YoY basis points (bps) change in delinquency rate

Credit card

30.7%

12.3%

-20 bps

Bank personal loan

2.7%

26.3%

14 bps

Non-bank personal loan

11.5%

41.3%

520 bps

Clothing accounts

7.6%

25.9%

-294 bps

Retail instalment

16.0%

27.1%

-138 bps

Retail revolving

5.4%

14.9%

-350 bps

Home loans

-10.8%

7.4%

19 bps

Vehicle finance

11.7%

5.4%

-1 bps

 *Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears


[1] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).

[2] TransUnion age distribution: Gen Z (Born 1995 – 2010); Millennials (Born 1980-1994); Gen X (Born 1965-1979); Baby Boomers (Born 1946-1964
Read moreSouth Africa’s Consumer Credit Market Sees Targeted Growth in Key Products, Despite New High in Personal Loans Delinquencies
11 December 2025

Economic Growth Must Be the State’s Primary New Year’s Resolution

Location: News

The GOOD Party supports the proposed 1.5% above-inflation rate increase to the minimum wage, which will rise from R28.79 per hour to more than R30 per hour in March 2026.

The post NEW MINIMUM WAGE A SMALL STEP TOWARDS FAIRNESS- BUT ECONOMIC GROWTH MUST BE THE STATE’S PRIMARY NEW YEAR’S RESOLUTION appeared first on For Good.

Read moreEconomic Growth Must Be the State’s Primary New Year’s Resolution
11 December 2025

How African Consumers Set Global Trade Trends in the 1800s

Location: News

Africa’s ‘new consumer class’ isn’t new; in the 1800s the continent called the tune for European factories.

Read moreHow African Consumers Set Global Trade Trends in the 1800s
10 December 2025

Coups in Africa: How Democratic Failings Help Shape Military Takeovers – Study

Location: News

Popular disappointment in elected governments was a prominent trigger for coup makers.

Read moreCoups in Africa: How Democratic Failings Help Shape Military Takeovers – Study
9 December 2025

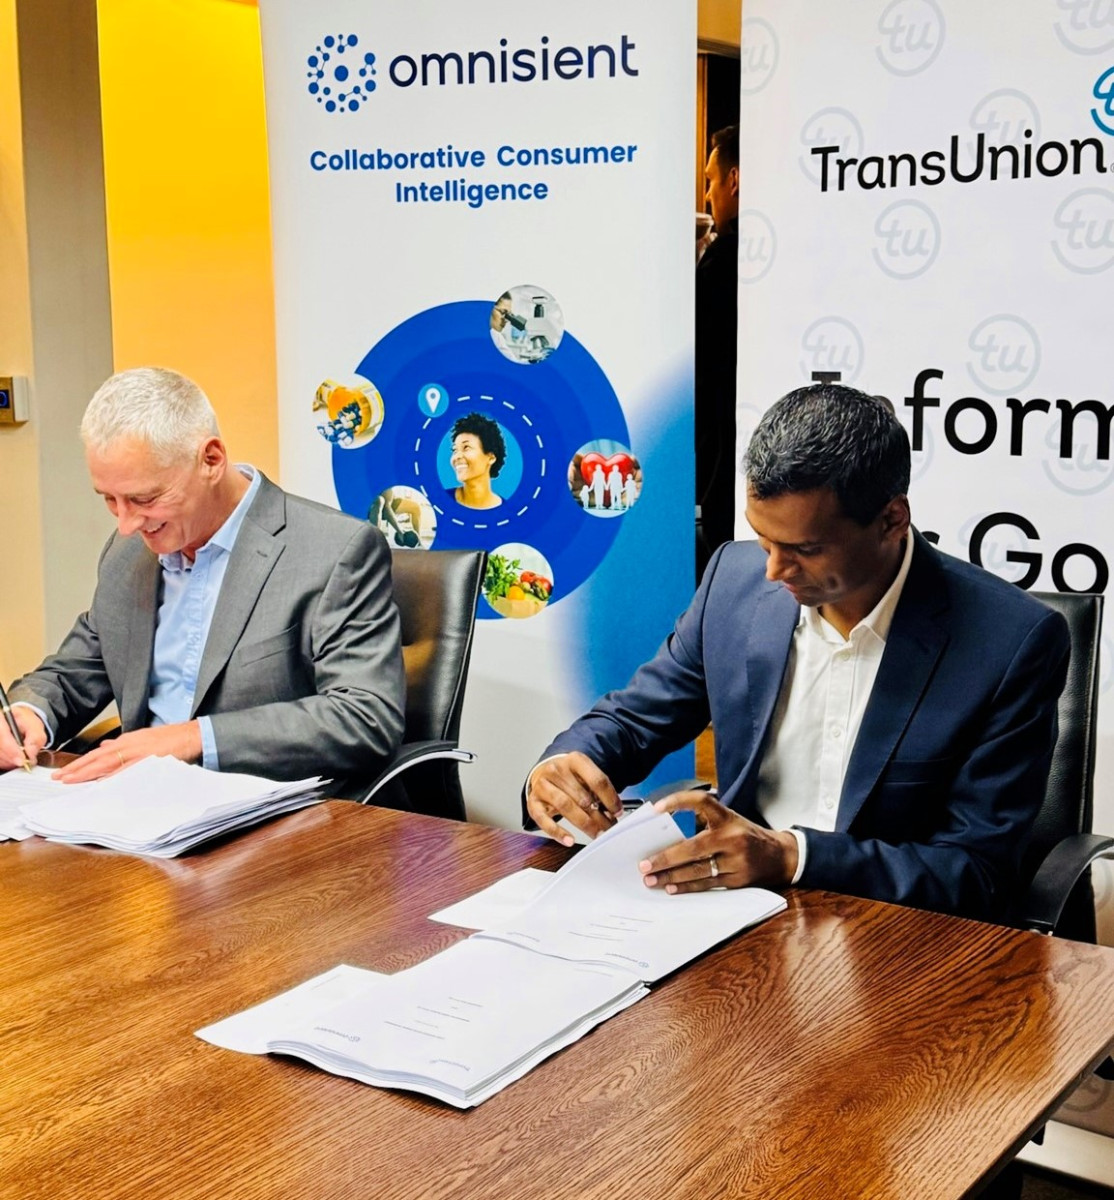
TransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption

Location: Business

TransUnion today announced a minority investment and broader strategic partnership with Omnisient, a South Africa-founded FinTech operating internationally that offers a privacy-preserving data collaboration and advanced analytics platform. The Omnisient platform empowers businesses to safely access high-value consumer data ecosystems and rapidly integrate alternative data sets to drive intelligent decision-making. As part of the investment, a TransUnion representative will join Omnisient’s board of directors.

“The Omnisient platform allows multiple clients to use built-in advanced analytical tools to simultaneously evaluate the utility of diverse data sets, identifying those that deliver measurable value. Through this collaboration, TransUnion expects to gain access to a broader range of alternative data sources and privacy preservation capabilities. By accelerating the integration of high-impact data into our ecosystem, we intend to enhance existing solutions and develop new, market-relevant products that better meet the evolving needs of our customers,” said Lee Naik, Regional President/ CEO of TransUnion Africa. 

“Traditional data models often fail to reflect the lived realities of African consumers, leaving millions without access to credit and the opportunities it enables,” said Naik. “Financial inclusion is central to unlocking economic growth across the continent. That’s why we’re committed to leading with bold, African-born solutions designed to see the unseen and serve the credit invisible by integrating alternative data sets alongside traditional credit data in ways that reflect uniquely African contexts and realities. By incorporating non-traditional indicators of financial behaviour, this approach broadens access to credit and helps us reach more underserved communities. We believe accelerating the adoption of alternative data is critical to closing the credit gap at scale, enabling faster, fairer and more inclusive access to financial services for millions across the continent."

“Our privacy-preserving data collaboration platform brings financial services and consumer brands together, allowing them to discover, validate and commercialise new alternative sources of consumer behavioural and transactional data without having to exchange sensitive personal information,” said Jon Jacobson, co-founder and group CEO of Omnisient. “This data allows financial institutions to make better risk decisions with more confidence and security, unlocking the potential to grow financial inclusion for hundreds of millions of people around the world.”

This collaboration marks a natural progression in TransUnion’s strategy to expand financial inclusion across Africa. By leveraging privacy-enabled alternative data sets through Omnisient’s platform, TransUnion intends to strengthen its ability to help address the challenge of bringing an estimated 500 million* financially excluded Africans into the formal financial ecosystem. By responsibly harnessing alternative data at scale, TransUnion sees the opportunity to bring millions of new-to-credit and credit-underserved consumers across Africa into the financial mainstream. This enables individuals to begin building a credit profile, many for the first time, laying the foundation for long-term economic empowerment. It’s a powerful demonstration of TransUnion’s commitment to using Information for Good® to drive measurable impact at scale: expanding access to credit, unlocking economic potential and reshaping the future of finance across Africa.

Global demand is rising for alternative data solutions that protect privacy, build trust and unlock value. Omnisient’s platform meets this need with technology that enables secure, privacy-preserving data collaboration. Instead of transferring raw data, Omnisient uses tokenised keys to represent personal information in the data set, ensuring privacy is maintained throughout the process. As a leading provider in Africa of secure, many-to-many data connectivity between banks, financial institutions and third-party sources, Omnisient is driving innovation in data collaboration.

*Source: The Global Findex Database 2021

Read moreTransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption
8 December 2025

South Africans Signal Cautious Confidence as Financial Habits Evolve

Location: Business
  • TransUnion’s Q2 2025 Consumer Pulse Study reveals strategic shifts in saving, borrowing, and fraud defence, with younger generations leading the way
  • 75% of South Africans expect their income to rise, but nearly 39% anticipate missing at least one bill or loan payment
  • 45% of Gen Z and 39% of Millennials plan to apply for credit, leading a shift toward more proactive financial habits
  • 58% of consumers were targeted by fraud in Q2, with many responding by strengthening their digital security

South African consumers are responding to ongoing financial pressures with increasing intent and vigilance. While inflation, high interest rates and job market uncertainty continue to weigh on household budgets, the latest TransUnion Consumer Pulse Study for Q2 2025* reveals a population adjusting not just defensively, but proactively. From rethinking spending and saving to becoming more discerning about credit and fraud, South Africans are adopting behaviours that suggest a shift toward long-term financial resilience, especially among younger generations.

“South Africans are showing resilience with purpose,” said Ayesha Hatea, director of research and consulting at TransUnion. “They’re not simply reacting to pressure, they’re taking charge, rebalancing their finances and protecting their future.”

Mixed Incomes, Bold Adjustments

While there are some positive signs, many households are still experiencing fluctuations in their income. In the second quarter, 21% of consumers said their household income had decreased, while 38% reported an increase. A majority of respondents (75%) are hopeful that their earnings will increase in the next year. However, this confidence exists alongside financial challenges, with nearly 39% of consumers reporting that they expect they might miss at least one bill or loan payment in the near future.

This financial pressure is driving noticeable changes in how people manage their money. More than half of consumers (54%) trimmed back on non-essential expenses like dining out, entertainment and travel. Many are also taking steps to strengthen their financial security; 31% paid down debt faster, 24% put more into emergency savings or stokvels and 37% planned to increase their retirement or investment savings.

Generational Differences Define the Shift

While overall behaviours are trending positive, the evolution is not uniform across age groups. Younger consumers, particularly Gen Z (ages 18-28) and Millennials (29-44) are emerging as drivers of this transformation. They are more likely to apply for credit, monitor their credit reports frequently and adopt security tools like multi-factor authentication.

Forty-five percent of Gen Z respondents and 39% of Millennials indicated they plan to apply for or refinance credit in the next year, compared to just 27% of Gen X (45-60) and 15% of Baby Boomers (61+). They are also the most engaged in monitoring their credit monthly and believe that access to alternative data, such as rental or Buy Now Pay Later (BNPL) payment histories, would improve their credit scores.

“Younger South Africans are embracing financial tools with growing confidence,” Hatea added. “They’re more comfortable with digital platforms, increasingly aware of how their financial choices affect their long-term goals, and, as a result, are more proactive about managing their credit.”

Cautious Credit Intent Amid Access Concerns

While 92% of consumers believe access to credit is important to achieving their financial goals, only 36% intend to apply for credit in the coming year, a figure that has remained stable since Q1. This cautious demand reflects continued uncertainty around employment, income and affordability.

Consumers favour unsecured lending, with credit cards (30%), personal loans (28%) and BNPL services (25%) attracting the most interest. Interest in secured lending remains comparatively low, with only 22% planning to apply for vehicle finance and 19% expressing interest in home loans.

Still, barriers remain. Nearly half (48%) of consumers said they had considered applying for credit but ultimately decided not to. The main reasons were income/ employment status (30%), high borrowing costs (29%) and concerns about their credit history (27%). Overall, 45% of consumers believed they would be approved if they applied for credit. While this figure reflects general sentiment, optimism tends to be higher among those who actively monitor their credit, suggesting a link between financial awareness and confidence.

Digital Fraud on the Rise, but So Is Awareness

As digital engagement grows, so does the threat of fraud. In Q2 2025, 58% of South Africans reported being targeted by fraud schemes, a decrease from the previous quarter (61%) with 13% confirming they had fallen victim. The most common scams included gift card or money transfer scams (33%), phishing (31%), smishing (30%) and third-party seller scams (28%).

Consumers are responding with heightened vigilance in response to cyber security concerns. A majority (59%) changed their passwords, 39% checked their credit reports and 25% added multi-factor authentication. Gen Z and Millennials were the most likely to take protective action, a likely result of both their greater exposure to digital platforms and higher awareness of evolving scam tactics. Alarmingly, 21% of consumers said they took no action at all, often citing uncertainty about what to do. This highlights the ongoing need for stronger cybersecurity and fraud education, and accessible protection tools.

“Consumers are trying to keep pace, but the threat landscape is evolving quickly,” said Hatea. “What we need now is a national conversation, one that gives all South Africans the knowledge and resources to protect their identities in a digital-first world.”

A Financial Turning Point

The Q2 2025 Consumer Pulse Study reveals a country making deliberate financial choices in the face of uncertainty. South Africans are shifting from survival mode to a more balanced, future-focused financial mindset. While challenges remain, the direction is clear; consumers are becoming more selective in how they spend, more strategic in how they borrow and more vigilant in how they protect themselves.

“At TransUnion, we believe these shifts represent not just resilience, but growth,” concluded Hatea. “South Africans are taking ownership of their financial journeys and in doing so, they’re laying the groundwork for lasting stability and inclusion.”

Consumers can get their free annual credit report from TransUnion here.

* This online survey of 922 adults was conducted May 5–25, 2025

Read moreSouth Africans Signal Cautious Confidence as Financial Habits Evolve
8 December 2025

Kouga’s Failed R1.4-Million Mini Market Project

Location: News

A mini fresh food and craft market for Hankey never opened

Read moreKouga’s Failed R1.4-Million Mini Market Project
7 December 2025

TransUnion Unlocks Smarter, Faster Financial Services for SMMEs and FinTechs With API Marketplace

Location: Business
  • TransUnion’s new API Marketplace gives SMMEs and FinTechs instant, self-service access to credit, identity, and fraud prevention tools
  • The platform simplifies integration, accelerates decision-making, and supports inclusive, data-driven financial services
  • Designed for agility and scale, it empowers smaller businesses to compete and innovate in South Africa’s growing digital economy
  • Improved access to accurate data enables businesses to better serve underserved communities, advancing equitable access to financial services

Global information and insights company TransUnion Africa has launched its API Marketplace, a streamlined digital platform designed to give small, medium, and micro enterprises (SMMEs) as well as FinTechs direct, self-service access to a wide range of credit, identity and fraud prevention solutions. The platform aims to simplify integration, strengthen risk assessment, and support the delivery of faster, more personalised financial services across the country. The API Marketplace helps reduce technical complexities, enabling companies to quickly incorporate credit checks, identity verification, and fraud detection into their operations for faster, more accurate decision-making.

Simplifying Access to Trusted Data Solutions

For many SMMEs and FinTechs, limited access to reliable credit data, time-consuming verification processes, and the burden of manual fraud checks can slow growth and undermine customer trust. The TransUnion API Marketplace addresses these pain points by allowing businesses to discover and embed TransUnion’s trusted data solutions directly into their systems, without lengthy onboarding processes or complex development cycles.

“With the launch of the TransUnion API Marketplace in South Africa, we’re empowering SMMEs and FinTechs with the tools they need to thrive in the digital economy,” says Dee Chetty, Chief Product Officer at TransUnion Africa. “It’s about lowering barriers to entry for businesses aiming to innovate quickly, deliver inclusive financial services, and make smarter decisions, while upholding the highest standards of data integrity and security.”

The platform offers real-time access to insights that support key business functions, from identity verification during customer onboarding to fraud flagging and credit risk assessment throughout the customer lifecycle. This is particularly powerful for SMMEs and FinTechs, which often operate with lean teams and need to maximise efficiency without compromising on due diligence.

Supporting Financial Inclusion and Economic Growth

According to the latest Mastercard SME Confidence Index, 90% of South African SMMEs have adopted digital payments in recent years, demonstrating the sector’s appetite for modernisation. However, many still lack access to the kind of scalable, reliable infrastructure that larger organisations take for granted. The API Marketplace bridges that gap, enabling smaller firms to leverage TransUnion’s capabilities in a cost-effective and agile way.

Crucially, the offering also supports national priorities around financial inclusion. Improving the flow of accurate credit and identity data enables businesses to offer more tailored products to underserved consumers, particularly in emerging markets and low-income communities. This helps create a more transparent and equitable financial ecosystem, where access to funding and services is based on real, data-driven insights.

“The API Marketplace is not just a product, it’s an enabler of impact,” adds Chetty. “We know that the future of inclusive finance in South Africa depends on access: to data, to tools, and to trust. This platform delivers on all three, helping more businesses deliver safe, responsible, and responsive financial products.”

Developer-Friendly Design for Rapid Deployment

Digitising integration through the API Marketplace enhances operational efficiency and significantly shortens development timelines. The platform includes a wide range of features designed for accessibility and ease of use. It offers a searchable API catalogue, developer-friendly documentation, and robust security protocols, all designed to reduce friction and accelerate deployment. A structured onboarding process is already in place, with plans to introduce full self-service and digital onboarding in the next phase of development.

Looking ahead, TransUnion sees the API Marketplace as a critical lever for economic resilience and innovation, particularly as the South African FinTech sector continues its rapid growth. The local FinTech market is projected to reach USD 14.86 billion by 2033, with APIs playing a foundational role in scaling new financial solutions.

Visit TransUnion’s API Marketplace for more information.

Read moreTransUnion Unlocks Smarter, Faster Financial Services for SMMEs and FinTechs With API Marketplace
5 December 2025

Vodacom Found Guilty of Unfair Market Practices

Location: News

Communications authority says the company altered contract terms without prior communication

Read moreVodacom Found Guilty of Unfair Market Practices
4 December 2025

Cape Town City Council Approves Plan to Sell Woodstock Hospital

Location: News

Residential development planned, including affordable housing

Read moreCape Town City Council Approves Plan to Sell Woodstock Hospital
4 December 2025

TransUnion South Africa Busts Three Short-Term Insurance Industry Myths

Location: Business

Every industry has its myths, and the short-term insurance environment is no exception: leading industry players plan their growth strategies around perceptions of a limited pool of customers, focusing mostly on pricing strategies to attract new business, and finding ways to avoid consumers perceived as too risky.

The best way to confirm or ‘bust’ industry myths is to test them through experiments and data analysis to reveal the truth – and that’s exactly what TransUnion South Africa did with data it holds in the short-term insurance sector.

“South African consumers remain under pressure despite recent interest rate cuts, making this an opportune moment for insurers to rethink their customer acquisition and retention strategies – and to challenge the truisms they’ve relied on in recent years,” said Schalk Fischer, insurance lead at TransUnion South Africa. “To drive better outcomes, insurers must evolve and adapt their strategies to respond to changing market conditions, drawing on risk-management solutions that feature unique data and advanced analytics.”

Myth 1: With stagnant total policy volumes, the only way for an insurer to grow is to win customers from other insurers.

In assessing all new short-term insurance policies taken out between April 2024 and March 2025, TransUnion found that only 17% of new policies were opened by consumers moving to another insurer. Another 37% involved ‘policy splitting’, where consumers moved cover of one of their assets to a new provider, but did not move their whole portfolio.

This means that roughly 54% of new policies are opened due to churn – a significant portion, but certainly not the overwhelming portion that many insurers believe it to be.

“This data shows key growth opportunities for insurers lie among consumers who are new to insurance. In fact, 33% of new policies opened during the time of the study were taken out by consumers who had not had an insurance premium in the previous 24 months,” Fischer said. “While the short-term industry will always be very competitive, there are growth opportunities outside of working aggressively to attract customers from other insurers.”

Myth 2: Loyalty in short-term insurance is dead. Price is the primary variable.

With many consumers scrambling for cost savings, price is perceived to be the most important differentiator between insurers, along with being seen as the main reason that consumers leave one insurer for another.

TransUnion’s analysis showed that 13% of insured consumers who cancel their insurance eventually return to their original insurance provider over time, without switching to another insurer in the interim.

This brand loyalty is fairly consistent between different distribution channels: 9% for banks’ insurance offerings, 11% for brokers, and 14% for direct insurers.

“These findings highlight that, while insurance pricing is certainly a leading consideration among consumers, it is evident that brand loyalty is still a driving factor,” Fischer said. “Marketing and acquisition strategies clearly focus on price, but there’s a greater than expected opportunity to build loyalty that will either retain customers or encourage them to return to brands they have trusted before.”

Myth 3: The new-to-insurance segment is small and only includes risky younger consumers.

TransUnion’s analysis revealed that one in three (33%) consumers who took out policies between April 2024 and March 2025 were new to insurance – they did not have short-term insurance payments linked to their identity number in the previous 24 months.

However, this doesn’t necessarily mean that all newly insured consumers were uninsured before. Some may have previously been covered under their partner or spouse, and later separated their insurance portfolios, or they could have been young adults who sought their own cover after being included in their parents’ policies.

“These findings show that insurers need to expand the scope of how they segment their target audiences, as new-to-insurance consumers are not always who they’re perceived to be,” Fischer adds.

The analysis revealed additional insights into consumers taking out a policy for the first time. Only 6% were aged 18 to 24 years – perceived to be the riskiest consumers – while the greatest portion of these consumers (36%) were aged 25 to 35 years, followed by 36 to 45 year olds, who took out 25% of new policies. It’s clear, then, that consumers aged 25 to 45 present the greatest opportunity for insurers.

In overlaying loyalty data with these findings, it emerged that only 1% of 18 to 24 year olds shopped around for a better deal once they were granted cover, while less than a quarter (24%) of 25 to 35 year olds shopped around. However, consumers aged 36 to 45 showed the greatest propensity to shop around for a better deal, with 29% taking on that challenge.

The myth is officially busted: opportunities for growth lie well beyond young consumers who have only just reached eligibility to apply for their own short-term insurance policies.

“While the short-term insurance market is perhaps not growing at the rate that many insurers would like, our analysis shows that it’s far from stagnant. Clear segmentation along with careful risk management and profitability assessments can help providers acquire lower-risk, higher-value customers across diverse groups of potential customers,” Fischer said. “While price remains a significant driver among consumers, other variables continue to play a meaningful role in building customer loyalty.”

Read moreTransUnion South Africa Busts Three Short-Term Insurance Industry Myths
4 December 2025

Concern Raised Over Fairness and Transparency in MyCiTi Deviation Contract

Location: News

We note with concern the City of Cape Town’s decision to conclude the deviation contract with the existing MyCiTi Phase 1A Vehicle Operating Companies without an open and competitive tender process.

The post CONCERN RAISED OVER FAIRNESS AND TRANSPARENCY IN MyCiTi DEVIATION CONTRACT appeared first on For Good.

Read moreConcern Raised Over Fairness and Transparency in MyCiTi Deviation Contract
4 December 2025

Facebook Promotes Rubbish Because It Doesn’t Understand Indigenous Languages

Location: News

Content producers get away with fake news and clickbait

Read moreFacebook Promotes Rubbish Because It Doesn’t Understand Indigenous Languages
3 December 2025

A Walk in the Night to Mark the End of Slavery

Location: News

March through Cape Town commemorates the emancipation of slaves in 1834

Read moreA Walk in the Night to Mark the End of Slavery
3 December 2025

South Africa’s Automotive Market Accelerates to 11-Year High as Value Brands and Younger Buyers Drive Momentum

Location: Business
  • 111 697 new passenger vehicles sold in Q3 – up 23.4% year-on-year, the highest quarterly total since 2014
  • Chinese brands captured a record 15%+ market share, growing almost nine times faster than the market average
  • Passenger-vehicle exports rebounded 4.1% year-on-year, powered by a 63.7% September surge to a six-year high

South Africa’s automotive market shifted into top gear in the third quarter of 2025, posting its strongest sales performance in more than a decade as greater macro-economic stability, easing interest rates and a firmer rand supported renewed consumer demand. According to TransUnion’s Q3 2025 Mobility Insights Report, total new-passenger-vehicle sales reached 111 697 units, 23.4% higher year-on-year (YoY), while new vehicle inflation dropped to a record low of 1.5% (since tracking began in 2008), creating one of the most competitive pricing environments in recent memory.

“Affordability and choice are redefining South Africa’s automotive landscape,” says Lee Naik, CEO TransUnion Africa. “Consumers are seeking greater value and flexibility and manufacturers that meet this demand through innovation and pricing discipline are winning the race for growth.”

Affordability Drives Record Growth and Market Realignment

Although established OEMs returned to positive growth in Q2 and Q3 2025, the market’s transformation is being led by Chinese manufacturers expanding nearly nine times faster than the overall market, with YoY growth of 89% in Q2 and 88% in Q3.

Their combined share has quadrupled since 2021 to more than 15%, powered by competitively priced, feature-rich SUVs and sedans that appeal to cost-conscious yet tech-savvy buyers. Top-performing value brands YoY included JAC (67% volume increase), GWM (54%), Mahindra (42%) and Chery (35%), while BMW (27%) proved that premium marques can still thrive by combining desirability with strong product pipelines.

“This isn’t a short-term surge, it’s a structural reset,” adds Naik. “The success of value-driven models shows how affordability, technology and trust are now the true levers of brand growth in South Africa.”

Younger and High-Income Buyers Sustain Demand

Despite surging sales, TransUnion’s recent Consumer Pulse Survey shows a modest easing in purchase intent, with the share of respondents likely to buy a vehicle in the next three months declining from 19% in Q2 to 17% in Q3. The report suggests that current sales momentum is being driven primarily by pent-up demand, dealer incentives and fleet renewals, rather than broad-based consumer confidence.

Purchase behaviour also remains sharply segmented across both age and income groups. Younger consumers continue to lead intent, with 21% of Gen Z and 19% of Millennials planning to buy a vehicle in the next three months, compared to 13% of Gen X and 8% of Baby Boomers. From an income perspective, high-income households earning R200 000 or more per month show the strongest intent at 34%, while middle- and lower-income consumers remain significantly more cautious in their purchasing outlook.

Electrification: A Tale of Price and Generation

Internal-combustion vehicles (ICE) remain the single largest category in consumer purchase intent, accounting for 42% of consumer preference, while interest in hybrid (39%) and plug-in hybrid (24%) models is steadily increasing. The shift toward electrification is most pronounced among Gen Z consumers, with 55% favouring hybrids and 32% considering battery-electric vehicles (BEVs).

This generational shift toward greener technology is evident among high-income buyers, with 75% considering plug-in hybrids, driven primarily by their perceived affordability. In contrast, preference for ICE vehicles remains largely affordability-based among lower-income segments. Higher budgets within affluent households enable greater consideration of hybrid electric (HEV), plug-in hybrid (PHEV), and battery electric vehicles (BEV), reinforcing an emerging “electrification divide.” This dynamic presents a significant opportunity for OEMs and financiers to tailor product offerings and financing strategies to meet the distinct needs of different age and income segments.

Connected Cars: Data Becomes the New Engine

Q3’s Mobility Insights Report special feature, The Connected Road, explores how connected-car technology is transforming mobility. Connectivity is now standard in most post-2015 vehicles, enabling real-time navigation, predictive maintenance, remote access, and advanced safety systems. Yet global data warns of “connectivity fatigue”: Over three quarters (76%) of drivers internationally don’t subscribe to connected services, mainly due to cost.

Naik says: “South Africa has a chance to leapfrog global missteps by focusing on value-adding applications, safer driving, cheaper insurance and smarter maintenance rather than gimmicks.”

Exports Rebound and Dealer Confidence Climbs

Passenger-vehicle unit exports rose 4.1% YoY after a steep Q2 contraction, driven by a 63.7% September surge that lifted shipments to a six-year high. Meanwhile, the RMB/BER Motor Traders Confidence Index advanced to 54, marking its second net-positive reading of 2025 and notably placing it above the neutral 50-point mark, which signals growing dealer optimism amid sustained sales momentum and improving export conditions.

Balancing Value and Transformation

The convergence of affordability, segmentation, electrification, and connectivity signals a pivotal shift in the automotive industry. “The future belongs to brands and financiers that master both the value-driven present and the connected, electrified future,” concludes Naik. “Data-led insight will be the bridge that connects today’s strategies with tomorrow’s innovation

Read the full TransUnion South Africa Q3 2025 Mobility Insights Report here.

Read moreSouth Africa’s Automotive Market Accelerates to 11-Year High as Value Brands and Younger Buyers Drive Momentum
2 December 2025

South African Automotive Market: Recovery Gains Traction but Headwinds Persist

Location: Business
  • New passenger sales rose 22.5% year-on-year, the strongest volumes since 2014
  • Chinese automakers expanded their market share to nearly 15%, up from just 3.1% in 2022
  • Passenger-vehicle exports contracted sharply, down 24.6% amid weaker global demand and new US tariffs

TransUnion’s latest Mobility Insights Report shows South Africa’s automotive market building momentum in 2025, supported by a favourable interest rate environment, record-low new-vehicle inflation, and liquidity from the two-pot pension reform. While recovery is underway, the outlook remains fragile, with affordability constraints and export headwinds threatening longer-term growth.

Supportive Shifts, But Growth Remains Fragile

The South African Reserve Bank has cut interest rates five times since September 2024 and inflation has returned to the lower end of the 3-6% band1, providing households with some relief. Consumer confidence has improved among middle- and higher-income groups, although low-income consumers continue to face pressure from food and electricity costs2.

“These macro shifts provide short-term support to the vehicle market, but momentum is likely to taper in 2026 without further reforms,” said Lee Naik, CEO of TransUnion Africa.

Affordability And Value Drive a Surge

Passenger car sales broke through the 35,000-unit ceiling for the first time in years, with July and August 2025 marking the strongest volumes since 2014. According to Naamsa, new passenger car sales grew 22.5% year-over-year (YoY) in Q2, fuelled by lower borrowing costs, aggressive OEM incentives and the entry of new value-focused brands.

Chinese automakers continued their rapid growth, expanding market share from 3.1% in 2022 to nearly 15% in Q2 2025. Their affordable, tech-rich SUVs and expanding dealer networks are reshaping competition, forcing legacy OEMs to rethink pricing, features, and model cycles. Toyota retained overall leadership, with Suzuki securing second place for the second consecutive quarter.

“Improved affordability, aggressive incentives and growing demand for value brands, alongside modest support from two-pot withdrawals, helped sustain momentum through 2025. However, as interest rates remain elevated and credit conditions tighten, and the two-pot effect normalises, growth is expected to moderate in 2026, with export risks and rand volatility adding uncertainty,” said Naik.

Diverging Trends: New vs. Used Vehicle Demand

NaTIS data shows new registrations rising 20% YoY in Q2 2025, led by Northern Cape, Free State and Northwest. In contrast, used registrations declined by 1.4%, reflecting pressure in that segment.

Across all vehicle sales, the Used-to-New Vehicle Registration Ratio rose to 3.2 in Q2, up from 2.5 in Q1, indicating a quarter-on-quarter increase in the relative share of used vehicle registrations. However, this remains below the 3.8 ratio seen through much of 2024, suggesting that new vehicles have regained some ground YoY. While used vehicles continue to dominate overall registrations, the market has shifted slightly back toward new vehicles compared to last year. This nuanced divergence presents opportunities for OEMs and dealer networks, while independent used dealers continue to face headwinds.

Exports Slump Amid Global Shocks

While domestic momentum improves, passenger vehicle exports fell 24.6% in Q2 2025 due to softer global demand and new US tariffs of up to 30%. Premium models, heavily reliant on the US and European markets, are under pressure, raising concerns for production, jobs, and investment.

Two-pot Withdrawals: Targeted Liquidity with Visible Impact

The September 2024 two-pot retirement reform injected liquidity into households, with evidence from the Bureau of Market Research suggesting a direct impact on mobility demand3, particularly in the used car market. While withdrawals were generally insufficient to fund deposits for new vehicles, they provided meaningful support to affordability-driven used vehicle purchases.

The reform is offering short-term relief rather than long-term wealth extraction, with withdrawals largely used for deposits, consumption, or debt repayment. Generational differences are evident: Millennials (aged 29 to 44) and younger Gen X (aged 18 to 28) are the most active claimants, while Baby Boomers withdraw minimally. Repeat withdrawals are becoming more common, suggesting both ongoing financial strain and the emergence of a recurring source of liquidity for entry-level and mid-market segments4.

“Two-pot withdrawals were not the only factor lifting sales,” noted Naik. “But the timing, scale and claimant profile suggest they acted as a meaningful catalyst for incremental used-car purchases.”

What Industry Players Should Do Next

Looking ahead, TransUnion advises that OEMs, dealers and lenders recalibrate strategies to balance domestic opportunities with external risks. Industry participants should align campaigns with liquidity cycles, planning promotions and stock availability around expected two-pot withdrawal windows.

Affordability must remain the priority, with a sharpened focus on value brands, certified pre-owned vehicles, and models that deliver a strong total cost of ownership. Financing solutions should also evolve, offering deposit support, trade-in boosters, and more flexible terms, while carefully monitoring repayment behaviour to manage post-purchase risk.

At the same time, leveraging data-driven insights, integrating credit and registration analytics to identify liquidity-sensitive buyers, preapprove customers, and track repayment performance, will be critical for sustaining growth in an uncertain environment.

“South Africa’s auto market is regaining momentum, but it’s a fragile recovery,” said Naik. “Those who time offers to policy-driven liquidity, sharpen affordability, and manage risk proactively will be best placed to capture growth.”

Read the full TransUnion South Africa Mobility Insights Report here.

ENDS

Notes to Editors: The Q2 2025 release is the second edition of the TransUnion South Africa Mobility Insights Report, formerly known as the Vehicle Pricing Index. The rebranded report now captures broader consumer, financing, and insurance insights across the mobility ecosystem.

Sources:

1 South African Reserve Bank (SARB)

2 TransUnion-South-Africa-CCI-Report-H2-2025-V9.pdf

3 Two-pot-claims-and-credit-data-FINAL.pdf

4 FAnews: Majority of two-pot withdrawals in the new tax year are repeat withdrawals; Moneyweb: Two-pot withdrawal: repeat claims surge; and Moneyweb, Two-pot payouts surge to R57B, with 4m withdrawals to date.

Read moreSouth African Automotive Market: Recovery Gains Traction but Headwinds Persist
1 December 2025

Nigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea

Location: News

Stronger public investment is needed so families are not forced to pay privately for basic education.

Read moreNigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea
1 December 2025

South Africa’s Credit Market Expanded During Q2 2025 Amid Eased Interest Rates and Shifting Consumer Risk

Location: Business
  • Millennial consumers drove significant new credit card growth, although new card limits dropped significantly
  • Vehicle asset finance growth trend continued, with more than two thirds of loans originated by Gen Z and Millennial consumers
  • Eased interest rates drove year-over-year growth in home loan originations, although affordability pressures may be impacting performance

South Africans responded to a more favourable interest rate environment during Q2 2025, leading to increased new account originations across most consumer credit products, particularly for credit cards and vehicle finance. Home loan activity also showed signs of recovery, as consumers felt more confident in committing to longer-term credit obligations. Retail revolving loans were the exception, with origination volumes declining despite growth in balances.

These are some of the findings of TransUnion’s Q2 2025 South Africa Industry Insights Report, which also found that South Africans were managing their credit better, as delinquencies improved across most consumer credit products during the quarter.

Credit Card Market Continued Upward Trajectory

Credit card originations increased by a robust 36.5% year-over-year (YoY), underscoring this product’s relevance as a flexible financial tool for consumers seeking convenience and/or liquidity in what remains a challenging economic environment. Millennials (born 1980 to 1994) drove this growth, with originations in this cohort making up 47.6% of all originations in the period.

Lenders seeking to expand market share continued to extend credit to consumers in higher-risk prime and below risk tiers[1], with originations to subprime consumers increased by 49.2% YoY. They balanced this growth among higher-risk borrowers with smaller credit limits. The average credit limit on new credit cards decreased by 19.5% YoY during the quarter.

Delinquency trends showed mixed results. Credit card balance-level delinquency rose slightly to 18.1%, up 13 basis points (bps) YoY, indicating a marginal increase in overdue balances. In contrast, account-level delinquency rates declined by 32 bps YoY to 12.1%. This decline in account-level delinquency suggests that while some consumers accumulated larger balances, many were able to make payments to keep their accounts active.

“The latest credit cards trends reflect strategic credit use and disciplined repayment behaviour among a financially stretched borrower base,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “The combination of rising origination volumes and shrinking new credit lines suggests that lenders are working to balance growth with prudent risk management. Lenders may need to refine their segmentation strategies, enhance early warning systems, and tailor credit line management to sustain portfolio health while supporting customers’ financial needs.”

Vehicle Asset Finance Shows Continued Growth

Vehicle asset finance originations increased by 21.0% YoY in Q2 2025, and average new loan amounts increased by 3.5% while the number of active accounts increased by 2.1% YoY. Growth was mainly driven by Gen Z (aged 18 to 28) and Millennial (aged 29 to 44) consumers who accounted for 64.3% of originations.

Outstanding balances grew by 7.6% YoY, and average balances have increased by more than 30% over the last five years, reflecting both higher vehicle prices and a sustained trend toward longer loan terms, which slows loan balance paydown rates. Loan terms granted during Q2 2025 averaged 74 months, up from 73 months in Q2 2024 and 72 months in Q2 2023. Longer loan terms, while slowing balance paydown, result in lower monthly payment amounts, which help consumers manage monthly cash flow in a high-cost environment.

Younger consumers are beginning to look for more ways to enter the vehicle market, including taking advantage of more cost-effective imported vehicles. However, 65% of vehicle finance originations were made by repeat buyers during Q2 2025, suggesting that access to vehicle finance remains limited for new entrants. At the same time, lenders need to be mindful of rising risk levels: in the second quarter of 2025, 44% of new-to-vehicle finance consumers fell into the subprime risk tier. These trends highlight the need for lenders to design credit products that support younger buyers, while ensuring responsible credit practices are upheld.

Account-level delinquencies for vehicle asset finance improved by 24 bps YoY to 5.1%, demonstrating that repayment behaviour for this product remained relatively stable, and that the overall risk profile of this portfolio is improving.

“For vehicle finance lenders, the rise in originations alongside modest growth in loan amounts suggests an opportunity to support demand while maintaining portfolio discipline,” said Hatea. “The improvement in delinquency rates is encouraging, but ongoing monitoring will be essential as economic recovery remains uneven. Vehicle finance lenders may benefit from refining pricing models, reassessing vehicle segmentation strategies, and balancing growth with prudent risk management.”

Home Loan Market Responds Positively to Eased Interest Rates

Lower interest rates, moderating inflation and improved real wage growth led to stronger consumer sentiment, giving lenders an opportunity to re-engage with consumers seeking home loans. New home loan account originations increased by 6.8% YoY during Q2 2025, showing early signs of recovery after declines in growth over previous quarters.

Favourable interest rate conditions and enhanced credit access drove broader access to home ownership this quarter, with 51% of home loans granted to individuals taking a home loan for the first time — the highest proportion in over five years. Among these, 56% were Millennials and 24% were Gen Z.

Delinquency trends showed mild deterioration, with the account-level delinquency rate increased by 29 bps to 7.5%. These movements suggest that while the market is stabilising, repayment stress remains a concern.

“These trends indicate a home loan market that is stabilising, but not without risk,” said Hatea. “For home loan lenders, the uptick in originations presents an opportunity to re-engage with the market, but rising delinquency rates underscore the need for vigilance. Portfolio strategies may need to shift toward enhanced consumer profile assessments, proactive risk monitoring, and targeted engagement with borrowers showing early signs of strain. As the market navigates this transitional phase, balancing growth with resilience will be key.”

 Table 1: Key South African Credit Market Metrics (Q2 2025 vs Q2 2024)

Product

YoY origination growth

Serious account-level delinquency rate*

YoY basis points (bps) change in delinquency rate

Credit card

36.5%

12.1%

-32 bps

Bank personal loan

2.2%

25.9%

-72 bps

Non-bank personal loan

18.8%

41.3%

256 bps

Clothing accounts

6.5%

25.9%

-265 bps

Retail instalment

21.4%

25.5%

-238 bps

Retail revolving

-6.3%

14.9%

-251 bps

Home loans

6.8%

7.5%

29 bps

Vehicle finance

21.0%

5.1%

-24 bps

 *Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears


[1] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).

Read moreSouth Africa’s Credit Market Expanded During Q2 2025 Amid Eased Interest Rates and Shifting Consumer Risk
1 December 2025

Rent Control Not Only Fails, It Entrenches Inequality

Location: News

The solution to housing affordability is to increase supply by building more housing

Read moreRent Control Not Only Fails, It Entrenches Inequality
29 November 2025

Creditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers

Location: Business

South Africa’s younger credit-eligible consumers present significant growth opportunities for lenders if they can overcome persistent market assumptions that currently shape risk appetite and acquisition strategies.

These assumptions include that younger consumers do not value credit, they are disengaged from the credit market, are irresponsible with debt, have low appetite for new credit, lack loyalty to lenders, and struggle to meet payment obligations.

They could also partly explain South Africa’s low 13% credit card market penetration among both Millennials (aged 29 to 44) and Gen Z (aged 18 to 28). Furthermore, Gen Z consumers adopt credit cards and personal loans at half the rate that Millennials did at the same age, suggesting limited growth for lenders as these consumers age.

“Our research suggests systemic barriers to credit access in South Africa, rather than a lack of demand,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “It also highlights that lenders have opportunities to innovate in product design, onboarding and education to empower these consumers to manage everyday expenses and unexpected financial needs as they progress towards achieving key life milestones.”

To challenge perceptions about younger consumers, TransUnion South Africa conducted a focused study[1] to test lenders’ perceptions, analysing participation, engagement and repayment behaviour among the country’s 4.3 million credit-active population aged 18 to 30.

Myth 1: Younger consumers don’t value credit

More than six in 10 (62%) younger consumers believe that access to credit is important to achieve their financial goals[2], with 76% saying that credit can give them access to new opportunities that could lead to a better quality of life. Younger consumers’ favourable perception of credit exceeds that of older consumers, 57% of whom believe access is important, and 71% of whom believe that access to credit can unlock new opportunities. However, less than a quarter (24%) of young consumers view credit as a risk to prudent financial management.

“Younger consumers increasingly see credit as a way to achieve their financial goals – even more so than older consumers,” Hatea said. “With most disagreeing that applying for credit signals poor financial management, it’s clear that opportunities exist for segment-focused products supported by financial literacy initiatives.”

Myth 2: Younger consumers are disengaged and don’t participate in the credit market

Nearly four in 10 (39%) young consumers feel that they have sufficient access to credit and lending products, with 49% believing that they would be approved for a credit product if they needed one.

It’s worth noting that, over time, consumers’ choice of credit product shifts. Reviewing credit card originations across a six-year period showed similar trends across time: 2% of 18 year old credit active consumers hold a credit card, compared to 19% of 30 year olds. Their participation in secured credit products increases with age, reaching parity with the general population by 30 and reflecting life stage realities like income, affordability and asset ownership, rather than disengagement.

“These shifts show that young consumers are engaged with the credit market, particularly with unsecured products, but their participation evolves across product types and life stages,” Hatea said.

Myth 3: Younger consumers are irresponsible in leveraging debt

Credit utilisation and average balances are well aligned with risk-based access that improves with age. At age 21, 95% of consumers are classified as subprime, dropping to 74% by age 30, reflecting a maturing credit profile.

Despite limited access, younger borrowers demonstrate measured usage: the average credit card balance at age 21 is R11,000, rising to R24,000 by age 30, while utilisation among near-prime consumers increases from 58% to 78% over the same age range.

“These trends highlight responsible engagement with credit and clearly refute the myth that younger consumers overextend their credit exposure, or are reckless with credit,” Hatea said. “As young consumers gain access to larger loan amounts, they move into better risk categories, reflecting greater lender trust in recognition of responsible repayment behaviour.”

Myth 4: Younger consumers have a low appetite for credit, and lack loyalty to lenders

While one third (33%) of the general population intends to apply for new credit within the next year, this increases to 45% for Gen Z consumers. Additionally, 36% of these consumers inquired about new credit over the six years studies, compared to 28% of all consumers. However, only 3.4% of younger consumers return to their first lender for new credit – similar to the 3.6% average across all consumers.

“The data shows that younger consumers do indeed have appetite for credit, while revealing that South African consumers in general are not particularly loyal to their credit providers,” Hatea said. “To build loyalty and retain younger consumers, lenders should invest in early-stage experiences, personalised engagement, and relevant products that build lasting relationships.”

Myth 5: Younger consumes struggle to keep up with their payment obligations

Interestingly, younger consumers show significantly lower risk of delinquency at 30 days past due (DPD) in the first year after opening credit cards, although this rises as they get older: there was a 17% delinquency rate among near prime 18 to 22 year olds, while 30 year olds displayed a 24% delinquency rate.

However, for non-bank loans and bank loans, younger consumers (18 to 24 years old) show slightly higher delinquency rates than older consumers, although younger consumers, especially those aged 23 to 25, perform better than the industry average. This indicates that lender type influences delinquency outcomes, and that younger borrowers may respond differently to the structure, support, or perception of a lender’s credit.

“Younger consumers are effectively managing their loans when compared to industry averages across most products,” said Hatea. “They’re not broadly higher risk, but they may be more vulnerable in certain lending contexts, particularly non-bank personal loans, where product design, support, or affordability may not be well aligned to their needs. Higher delinquency rates on non-bank personal loans can be addressed through early default detection tools.

“By focusing on education, wallet growth, loyalty, alternative data to measure risk, and proactive risk management, lenders can support younger consumers and drive long-term, sustainable growth among these consumers and in the broader credit market,” she said. “Well-managed credit can also be a catalyst for broader economic growth in South Africa.”


[1] TransUnion South Africa conducted a focused study to test lenders’ perceptions of consumers aged 18 to 30, analysing participation, engagement and repayment behaviour among the country’s credit-active population in this age group. Data was studied across four time frames (September in 2018, 2022, 2023 and 2024), and included age, risk score, open products in wallet, credit lines, average balances by product and credit utilisation at commencement of the study, new products opened, line assignments and opening loan amounts for six months, and delinquency rates on newly opened products for 12 months. These were compared to overall market averages to evaluate gaps and opportunities.

[2] According to TransUnion’s Q2 2025 Consumer Pulse Survey of 922 adults aged 18 or older, residing in South Africa conducted May 5–25, 2025 by TransUnion in partnership with third-party research provider, Dynata.

Read moreCreditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers
28 November 2025

TransUnion Study Reveals Key Insights Into South Africa’s FinTech Borrowers as Market Poised for Growth

Location: Business
  • TransUnion analysis reveals actionable insights for FinTech lenders seeking to navigate market complexities to achieve growth targets
  • FinTech lending is not the main gateway to financial inclusion, with most consumers choosing a clothing account as their first credit product
  • FinTech borrowers are loyal when it comes to subsequent products, but FinTech lenders are lower in consumers’ payment hierarchy than other lender types

TransUnion’s latest research into South Africa’s FinTech lending market reveals critical insights into borrower behaviour, loyalty and risk based on an analysis of 4.3 million South Africa consumers. The study highlights patterns that present both opportunities and challenges when navigating a rapidly digitising credit ecosystem.

South Africa’s FinTech sector is undergoing rapid transformation, signalling a major shift in how consumers will engage with credit in the next five years, and beyond. As digital adoption accelerates, lenders will need to adapt their approach to South African consumers if they’re to attract, retain and grow relationships with digitally engaged borrowers.

Emerging FinTechs are offering diverse solutions such as buy now, pay later (BNPL) loans with interest free payments, flexible financing for small and medium enterprises, point-of-sale credit and insurance coverage. Financial services are now more accessible than ever before. However, it’s essential that the lenders behind these solutions understand who is using them, how they engage with credit, and whether borrowers’ loyalty can help drive sustainable growth.

“As competition intensifies and regulatory frameworks evolve, lenders must go beyond product innovation and develop a deeper understanding of consumer behaviour,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “Our study offers a data-driven lens into the FinTech borrower profile, helping lenders build loyalty, manage risk, and drive inclusion.”

TransUnion analysed South Africans who held at least one open FinTech credit obligation in Q4 2024, including long-term personal loans, short-term personal loans and credit cards, to learn more about the consumers driving growth in the sector. The study examined risk profiles, delinquency trends, product breadth, and loyalty patterns among FinTech borrowers. Further, the study compared those characteristics to similar-risk consumers using traditional lender products only (non-FinTech borrowers[1]), providing a deeper understanding of growth opportunities for South Africa’s credit market.

Five Themes Shaping FinTech Lending Strategy

1.     FinTechs are not yet the main gateway to financial inclusion.

Despite South Africa’s high mobile penetration[2], 69% of New-to-Credit consumers – those with no prior reported credit history – enter the market via retail accounts, with clothing accounts being the most common first product. FinTechs have an opportunity to reposition themselves as enablers of financial inclusion by partnering with retailers and mobile ecosystems to reach underserved segments.

2.     FinTech borrowers are concentrated in below prime risk tiers[3].

While many FinTech borrowers have experience managing credit, 95% of FinTech borrowers with 0–1 month loans are in below prime risk tiers, compared to 29% for bank borrowers and 69% for non-bank lender borrowers. For 2–12 month loans, 94% of FinTech borrowers are below prime, in contrast to 58% for banks and 50% for non-banks. This highlights greater risk exposure among the FinTech borrower base and suggests that FinTech lenders could benefit from leveraging trended and alternative data to better predict repayment risk and reduce delinquency rates, particularly among below-prime borrowers.

3.     FinTech borrowers are not all underserved.

Among 0–1 month term borrowers, 44% of FinTech consumers already hold two or three credit products and 27% hold four or more, debunking the assumption that FinTech borrowers have limited access to credit. Additionally, more than 56% of FinTech personal loan borrowers hold credit products with non-FinTech lenders. These multi-lender relationships underscore the need for lenders to view borrowing patterns holistically and better understand the reasons why borrowers may be seeking credit from different lender types, in order to develop strategies for capturing more of their customers’ wallets.

4.     FinTech borrowers underperform on repayments.

While there are no material differences by lender type for longer-term loans, there are significant differences for 0-1 month loans. This is an important consideration as these shorter-term loans are more likely to be used by borrowers earlier in their credit journeys when they are potentially more financially vulnerable. After controlling for borrower risk score, delinquency rates (consumers 2+ months in arrears on a loan) were highest among FinTech borrowers: The consumer-level delinquencies were 74% for 0–1 month loans from FinTechs compared to lower rates for bank loans (53%) and non-bank lender loans (53%), underscoring the need for enhanced risk management strategies tailored to the FinTech segment.

5.     FinTech borrowers are loyal to FinTech lenders

TransUnion’s research provides compelling evidence of borrower loyalty within the FinTech lending ecosystem. Among consumers who originated a 0–1 month personal loan, 65% opened another 0–1 month loan within 12 months, and 93% of those chose a FinTech lender. More than one fifth (21%) of these borrowers progressed to a 2–12 month loan, with 80% remaining with FinTech providers.

Among consumers who started with a 2–12 month personal loan, 95% opened another 2–12 month loan, with 60% choosing a FinTech lender. In addition, 85% of these borrowers also opened a 0–1 month loan, and 38% did so with FinTech lenders. These patterns demonstrate a strong preference among borrowers to remain within the FinTech category, even as they take loans over longer time periods. This loyalty presents a strategic opportunity for FinTech lenders to deepen relationships through personalised engagement, targeted product offerings, and proactive risk management.

However, loyalty in product originations does not necessarily translate into repayment prioritisation. When consumers hold loans with both FinTech and non-FinTech lenders, they tend to prioritise repayments to traditional institutions. Among consumers with 2–12 term personal loans from both FinTech and non-FinTech non-bank lenders, delinquency measured as 1+ month in arrears was 33% for FinTechs, compared to 26% for non-FinTech non-bank lenders. Similarly, for those with loans from both FinTechs and banks, delinquency was 30% for FinTechs versus 28% for banks.

The takeaway for lenders is that while FinTech borrowers are loyal in terms of repeat borrowing, they may deprioritise FinTech repayments when under financial pressure. This highlights the need for FinTech lenders to strengthen their engagement strategies, build trust, and implement early intervention tools to improve repayment outcomes and long-term value.

“If lenders are to benefit from the anticipated growth in the FinTech lending market, it’s essential that they offer financial literacy and awareness education to help consumers understand how responsible credit use can support their financial goals. Once consumers have opened FinTech-issued products, lenders can activate lifestyle triggers to anticipate consumer progression so that they can deliver timely, relevant engagement to drive loyalty and long-term value. This can be further supported by deploying predelinquency models to identify early signs of consumer stress, and to initiate recovery efforts before risk escalates,” said Hatea.


[1] FinTech consumers were those with an open FinTech long-term personal loan, short-term personal loan, or credit card. Non-FinTech consumers were a control group with no FinTech obligations of any type in their history, who held a long-term personal loan, short term personal loan or credit card from a non-FinTech lender

[2] 118,600,000 connections across 60,690,000 people https://datareportal.com/reports/digital-2024-south-africa

[3] Scores are based on TransUnion’s CreditVision® generic scoring methodology. Risk distribution key: subprime (0-625), near prime (626-655), prime (656-695), prime plus (696-720), super prime (721-999).

Read moreTransUnion Study Reveals Key Insights Into South Africa’s FinTech Borrowers as Market Poised for Growth
28 November 2025

Part Two: Dodgy Nguni Cattle Deals Uncovered at Fort Hare

Location: News

A forensic investigation of a research farm found cattle sold for below market prices

Read morePart Two: Dodgy Nguni Cattle Deals Uncovered at Fort Hare
28 November 2025

News Influencers Are Reshaping the Media – Insights From Kenya, Nigeria and South Africa

Location: News

The most prominent news creators on social media and video networks are men and YouTube is the most important platform for them.

Read moreNews Influencers Are Reshaping the Media – Insights From Kenya, Nigeria and South Africa
27 November 2025

Global Power Shifts Are Playing Out in the Red Sea Region: Why This Is Where the Rules Are Changing

Location: News

The Red Sea region has become a showcase of the new alliances shaping global power and influence.

Read moreGlobal Power Shifts Are Playing Out in the Red Sea Region: Why This Is Where the Rules Are Changing
  • Previous
  • Page 1
  • Interim pages omitted …
  • Page 5
  • Page 6
  • Page 7
  • Page 8
  • Page 9
  • Interim pages omitted …
  • Page 31
  • Next

Copyright © 2026 · MyZA · All Rights Reserved · Powered by Stratlec Online