• Skip to main content
  • Skip to header right navigation
  • Skip to after header navigation
  • Skip to site footer
MyZA

MyZA

News, Directory, Events and Other Stuff

  • Social Media
  • Sport
  • World News
  • Home
  • Submit News
  • Directory
  • Events
  • Stratlec
  • TFSA
  • News
    • APO
    • Today’s Sport News
    • Todays Social Media and Tech Headlines
    • Today’s World News
    • Today’s SA Financial News
  • Contact
You are here: Home / Archives for Partnership

Partnership

9 December 2025

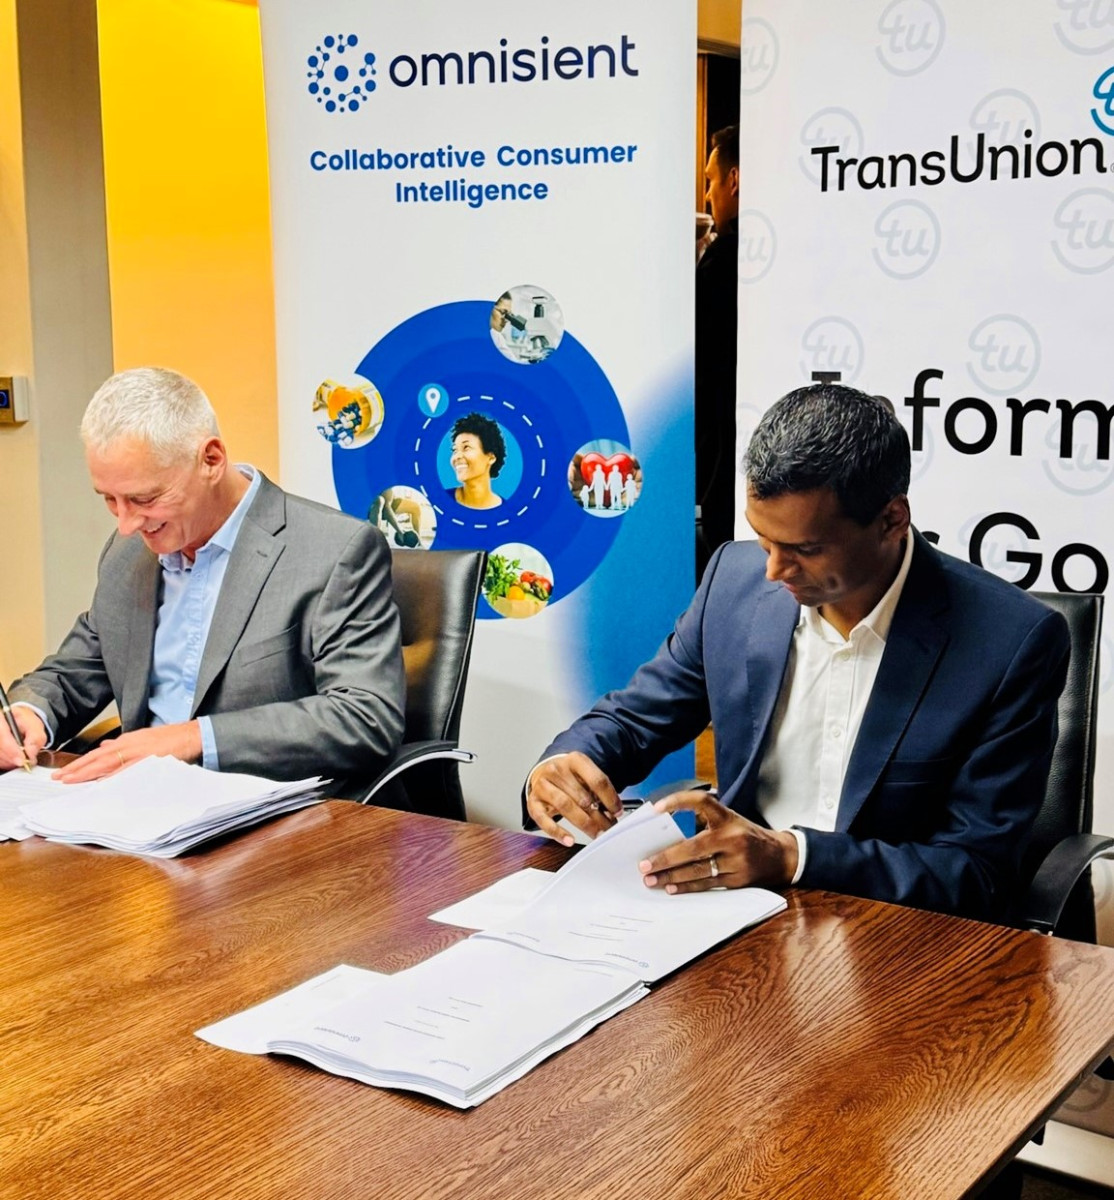
TransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption
Location: Business

TransUnion today announced a minority investment and broader strategic partnership with Omnisient, a South Africa-founded FinTech operating internationally that offers a privacy-preserving data collaboration and advanced analytics platform. The Omnisient platform empowers businesses to safely access high-value consumer data ecosystems and rapidly integrate alternative data sets to drive intelligent decision-making. As part of the investment, a TransUnion representative will join Omnisient’s board of directors.

“The Omnisient platform allows multiple clients to use built-in advanced analytical tools to simultaneously evaluate the utility of diverse data sets, identifying those that deliver measurable value. Through this collaboration, TransUnion expects to gain access to a broader range of alternative data sources and privacy preservation capabilities. By accelerating the integration of high-impact data into our ecosystem, we intend to enhance existing solutions and develop new, market-relevant products that better meet the evolving needs of our customers,” said Lee Naik, Regional President/ CEO of TransUnion Africa. 

“Traditional data models often fail to reflect the lived realities of African consumers, leaving millions without access to credit and the opportunities it enables,” said Naik. “Financial inclusion is central to unlocking economic growth across the continent. That’s why we’re committed to leading with bold, African-born solutions designed to see the unseen and serve the credit invisible by integrating alternative data sets alongside traditional credit data in ways that reflect uniquely African contexts and realities. By incorporating non-traditional indicators of financial behaviour, this approach broadens access to credit and helps us reach more underserved communities. We believe accelerating the adoption of alternative data is critical to closing the credit gap at scale, enabling faster, fairer and more inclusive access to financial services for millions across the continent."

“Our privacy-preserving data collaboration platform brings financial services and consumer brands together, allowing them to discover, validate and commercialise new alternative sources of consumer behavioural and transactional data without having to exchange sensitive personal information,” said Jon Jacobson, co-founder and group CEO of Omnisient. “This data allows financial institutions to make better risk decisions with more confidence and security, unlocking the potential to grow financial inclusion for hundreds of millions of people around the world.”

This collaboration marks a natural progression in TransUnion’s strategy to expand financial inclusion across Africa. By leveraging privacy-enabled alternative data sets through Omnisient’s platform, TransUnion intends to strengthen its ability to help address the challenge of bringing an estimated 500 million* financially excluded Africans into the formal financial ecosystem. By responsibly harnessing alternative data at scale, TransUnion sees the opportunity to bring millions of new-to-credit and credit-underserved consumers across Africa into the financial mainstream. This enables individuals to begin building a credit profile, many for the first time, laying the foundation for long-term economic empowerment. It’s a powerful demonstration of TransUnion’s commitment to using Information for Good® to drive measurable impact at scale: expanding access to credit, unlocking economic potential and reshaping the future of finance across Africa.

Global demand is rising for alternative data solutions that protect privacy, build trust and unlock value. Omnisient’s platform meets this need with technology that enables secure, privacy-preserving data collaboration. Instead of transferring raw data, Omnisient uses tokenised keys to represent personal information in the data set, ensuring privacy is maintained throughout the process. As a leading provider in Africa of secure, many-to-many data connectivity between banks, financial institutions and third-party sources, Omnisient is driving innovation in data collaboration.

*Source: The Global Findex Database 2021

Read moreTransUnion Announces Minority Investment and Strategic Partnership with Omnisient to Accelerate Alternative Data Adoption
9 December 2025

Lesotho’s Parliament blocks debate on explosive hospital report

Location: News

The wife of the foreign affairs minister features prominently in the report

Read moreLesotho’s Parliament blocks debate on explosive hospital report
6 December 2025

Be the Reason: A Movement in Partnership with TransUnion and the International Finance Corporation to Unlock Financial Opportunity for All

Location: Business

TransUnion, a global information and insights company, has launched a bold new campaign, ‘Be the Reason Things Change’, aimed at making financial inclusion a reality for more South Africans. This powerful initiative calls on individuals, communities, businesses, and institutions to join a movement for change, one that ensures every person is seen, supported, and given the tools to participate in the formal financial system.

In a country known for both its beauty and inequality, where access to formal credit remains out of reach for many, ‘Be the Reason Things Change’ seeks to break down the barriers that keep people excluded, by focusing on consumer education, innovation, and community engagement. The campaign is designed to help South Africans take control of their financial futures, regardless of who they are or where they come from, whilst also advocating for businesses to embrace alternative data and innovative scoring solutions to see and serve the unseen. By doing so, they too can empower the disempowered, expanding access and inclusion, and enabling more people to participate meaningfully in the financial ecosystem and live the lives they deserve.

“At TransUnion, we believe in a world where the impossible becomes possible, where the unseen are finally seen, and where every South African deserves the opportunity to participate fully in the economy,” says Lee Naik, CEO TransUnion Africa.

’Be the Reason Things Change’ is more than a campaign slogan; it’s a call to action to take part in building a more inclusive financial system. Through innovative data solutions and consumer education, we aim to spark a national conversation about breaking down barriers in the credit landscape and ensuring financial empowerment is accessible to all. Ultimately, we want more South Africans to be included in the formal financial economy, empowering them to understand how access to credit can transform their lives and enable them to uplift their communities,” says Naik.

Addressing South Africa’s Financial Inclusion Challenge

Many South Africans continue to face obstacles in accessing formal credit and quality financial services. Traditional systems often feel exclusive or out of reach, especially for underserved individuals and small businesses, because they rely heavily on past borrowing behaviour as the primary measure of creditworthiness. According to TransUnion’s CreditVision® Telco Data Score data-modelling, over 1.4 million credit-invisible South Africans open new credit accounts each year, contributing to more than four million new accounts over the past three years*. Yet traditional scoring models frequently fail to assess these consumers accurately, leaving over 16 million adults outside the formal credit system. Successfully integrating these and other excluded consumers into the economy could contribute an estimated R173 billion to South Africa’s GDP.

A significant portion, approximately 35% of new-to-credit consumers are under the age of 25, many entering the workforce for the first time and using credit to cover essentials such as work clothing. This highlights the urgent need for innovative, inclusive tools that better reflect the realities of younger, digitally active individuals who may lack a conventional credit footprint.

TransUnion is shifting the paradigm by embracing alternative data, creating new scoring capabilities, and ensuring that individuals who were once unclassifiable can now be assessed fairly and accurately. Its “Be the Reason Things Change” campaign responds to this need by equipping the public with practical tools, credit education, and the confidence to take charge of their financial futures.

Collaborative Effort with Global Partners

The campaign is supported by the International Finance Corporation (IFC), the private sector arm of the World Bank Group, has played a key role as a technical advisor and promotor of credit information tools in South Africa, reinforcing the global imperative to expand equitable access to financial services.

“We are proud to support TransUnion’s ‘Be the Reason Things Change’ campaign, which aligns closely with our mission to advance inclusive economic development,” says Cláudia Conceição, IFC Regional Director for Southern Africa. “By removing barriers to credit access, this initiative empowers individuals and communities to build financial resilience and unlock economic opportunity, key pillars of long-term social impact.”

This collaboration highlights the value of cross-sector partnerships in tackling systemic financial exclusion, combining local insights with global best practices to deliver scalable solutions.

Empowering Through Education, Innovation, Investment and Africa Firsts

‘Be the Reason Things Change’ will see TransUnion roll out a fully integrated marketing campaign designed to demystify the credit system and empower people from all walks of life. Key pillars of the campaign include:

  • A first-ever interactive peelable billboard in Africa, installed at Melrose Arch, located by the entrance off Corlett Drive in Johannesburg. 
  • A first-ever digital billboard aimed at reaching audiences beyond the Johannesburg area.
  • Transformational stories from campaign ambassadors include Springbok rugby stars Makazole Mapimpi and Lukhanyo Am, as well as fashion entrepreneur Tshepo Mohlala
  • Springbok, Lukhanyo Am and fashion entrepreneur, Tshepo Mohlala will be launching the campaign at Melrose Arch on 21 August 2025 where they will peel the first layers of the billboard and share their own personal journeys.
  • Over R10m valued in sponsorship and investment in e-learning credit courses for over 5,000 South Africans.
  • Practical education: Simple, clear resources to help people understand credit scores, manage debt, and make informed financial choices.
  • A unique AI-powered digital film piece.
  • Innovative Solutions: New offerings to help enable lenders to see consumers previously unseen, empowering consumers to access new credit opportunities

‘Be the Reason Things Change’ is about rewriting the story around credit and creditworthiness,” says Naik. “We want every South African to understand how credit works, what their score means, and how they can maintain and improve it. More importantly, we want them to believe they can be the reason things change.”

Campaign Execution Partners

The campaign was brought to life through a dynamic collaboration with creative agency 1 Over One, who led the conceptual development; local production partner Run Jump Fly, who delivered a unique AI-powered digital film piece, FleishmanHillard South Africa and Capacity Relations who provided strategic PR, media and activation support to amplify the message and ensure meaningful engagement across key audiences.

Join the Movement

TransUnion invites all South Africans to join the movement for financial inclusion. To learn more, participate in the campaign, and access educational resources, visit www.transunion.co.za/bethereason.

Consumers can get their free annual credit report from TransUnion here.

* The three-year period refers to an analysis of the TransUnion Credit Bureau database over the period for January 2022 – December 2025.

Read moreBe the Reason: A Movement in Partnership with TransUnion and the International Finance Corporation to Unlock Financial Opportunity for All
5 December 2025

Whatever Trump Says, Whites Are Not Doing Badly in South Africa

Location: News

How do we grow the economy and create a more racially equal society?

Read moreWhatever Trump Says, Whites Are Not Doing Badly in South Africa
5 December 2025

Magnus Carlsen and World’s Top Chess Players Show Their Skills in Cape Town

Location: News

The University of the Western Cape hosted a simultaneous display ahead of the Freestyle Chess Grand Slam Finals

Read moreMagnus Carlsen and World’s Top Chess Players Show Their Skills in Cape Town
1 December 2025

Nigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea

Location: News

Stronger public investment is needed so families are not forced to pay privately for basic education.

Read moreNigeria’s Low-Cost Private Schools Are the Only Option for Millions: Is Closing Them a Good Idea
29 November 2025

Creditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers

Location: Business

South Africa’s younger credit-eligible consumers present significant growth opportunities for lenders if they can overcome persistent market assumptions that currently shape risk appetite and acquisition strategies.

These assumptions include that younger consumers do not value credit, they are disengaged from the credit market, are irresponsible with debt, have low appetite for new credit, lack loyalty to lenders, and struggle to meet payment obligations.

They could also partly explain South Africa’s low 13% credit card market penetration among both Millennials (aged 29 to 44) and Gen Z (aged 18 to 28). Furthermore, Gen Z consumers adopt credit cards and personal loans at half the rate that Millennials did at the same age, suggesting limited growth for lenders as these consumers age.

“Our research suggests systemic barriers to credit access in South Africa, rather than a lack of demand,” said Ayesha Hatea, director of research and consulting at TransUnion South Africa. “It also highlights that lenders have opportunities to innovate in product design, onboarding and education to empower these consumers to manage everyday expenses and unexpected financial needs as they progress towards achieving key life milestones.”

To challenge perceptions about younger consumers, TransUnion South Africa conducted a focused study[1] to test lenders’ perceptions, analysing participation, engagement and repayment behaviour among the country’s 4.3 million credit-active population aged 18 to 30.

Myth 1: Younger consumers don’t value credit

More than six in 10 (62%) younger consumers believe that access to credit is important to achieve their financial goals[2], with 76% saying that credit can give them access to new opportunities that could lead to a better quality of life. Younger consumers’ favourable perception of credit exceeds that of older consumers, 57% of whom believe access is important, and 71% of whom believe that access to credit can unlock new opportunities. However, less than a quarter (24%) of young consumers view credit as a risk to prudent financial management.

“Younger consumers increasingly see credit as a way to achieve their financial goals – even more so than older consumers,” Hatea said. “With most disagreeing that applying for credit signals poor financial management, it’s clear that opportunities exist for segment-focused products supported by financial literacy initiatives.”

Myth 2: Younger consumers are disengaged and don’t participate in the credit market

Nearly four in 10 (39%) young consumers feel that they have sufficient access to credit and lending products, with 49% believing that they would be approved for a credit product if they needed one.

It’s worth noting that, over time, consumers’ choice of credit product shifts. Reviewing credit card originations across a six-year period showed similar trends across time: 2% of 18 year old credit active consumers hold a credit card, compared to 19% of 30 year olds. Their participation in secured credit products increases with age, reaching parity with the general population by 30 and reflecting life stage realities like income, affordability and asset ownership, rather than disengagement.

“These shifts show that young consumers are engaged with the credit market, particularly with unsecured products, but their participation evolves across product types and life stages,” Hatea said.

Myth 3: Younger consumers are irresponsible in leveraging debt

Credit utilisation and average balances are well aligned with risk-based access that improves with age. At age 21, 95% of consumers are classified as subprime, dropping to 74% by age 30, reflecting a maturing credit profile.

Despite limited access, younger borrowers demonstrate measured usage: the average credit card balance at age 21 is R11,000, rising to R24,000 by age 30, while utilisation among near-prime consumers increases from 58% to 78% over the same age range.

“These trends highlight responsible engagement with credit and clearly refute the myth that younger consumers overextend their credit exposure, or are reckless with credit,” Hatea said. “As young consumers gain access to larger loan amounts, they move into better risk categories, reflecting greater lender trust in recognition of responsible repayment behaviour.”

Myth 4: Younger consumers have a low appetite for credit, and lack loyalty to lenders

While one third (33%) of the general population intends to apply for new credit within the next year, this increases to 45% for Gen Z consumers. Additionally, 36% of these consumers inquired about new credit over the six years studies, compared to 28% of all consumers. However, only 3.4% of younger consumers return to their first lender for new credit – similar to the 3.6% average across all consumers.

“The data shows that younger consumers do indeed have appetite for credit, while revealing that South African consumers in general are not particularly loyal to their credit providers,” Hatea said. “To build loyalty and retain younger consumers, lenders should invest in early-stage experiences, personalised engagement, and relevant products that build lasting relationships.”

Myth 5: Younger consumes struggle to keep up with their payment obligations

Interestingly, younger consumers show significantly lower risk of delinquency at 30 days past due (DPD) in the first year after opening credit cards, although this rises as they get older: there was a 17% delinquency rate among near prime 18 to 22 year olds, while 30 year olds displayed a 24% delinquency rate.

However, for non-bank loans and bank loans, younger consumers (18 to 24 years old) show slightly higher delinquency rates than older consumers, although younger consumers, especially those aged 23 to 25, perform better than the industry average. This indicates that lender type influences delinquency outcomes, and that younger borrowers may respond differently to the structure, support, or perception of a lender’s credit.

“Younger consumers are effectively managing their loans when compared to industry averages across most products,” said Hatea. “They’re not broadly higher risk, but they may be more vulnerable in certain lending contexts, particularly non-bank personal loans, where product design, support, or affordability may not be well aligned to their needs. Higher delinquency rates on non-bank personal loans can be addressed through early default detection tools.

“By focusing on education, wallet growth, loyalty, alternative data to measure risk, and proactive risk management, lenders can support younger consumers and drive long-term, sustainable growth among these consumers and in the broader credit market,” she said. “Well-managed credit can also be a catalyst for broader economic growth in South Africa.”


[1] TransUnion South Africa conducted a focused study to test lenders’ perceptions of consumers aged 18 to 30, analysing participation, engagement and repayment behaviour among the country’s credit-active population in this age group. Data was studied across four time frames (September in 2018, 2022, 2023 and 2024), and included age, risk score, open products in wallet, credit lines, average balances by product and credit utilisation at commencement of the study, new products opened, line assignments and opening loan amounts for six months, and delinquency rates on newly opened products for 12 months. These were compared to overall market averages to evaluate gaps and opportunities.

[2] According to TransUnion’s Q2 2025 Consumer Pulse Survey of 922 adults aged 18 or older, residing in South Africa conducted May 5–25, 2025 by TransUnion in partnership with third-party research provider, Dynata.

Read moreCreditworthy and Misunderstood: New Data Challenges Lender Assumptions About Young Consumers
28 November 2025

Tshwane Metro’s Water Partnership May Be Doomed to Failure

Location: News

The Freedom Front Plus (VF Plus) notes the Tshwane Metro’s recent partnership with the Strategic Water Partners Network (SWPN), announced on 17 October 2025. This partnership entails rolling out a digital “water balance dashboard” designed to reduce water losses, detect leakages and improve demand management. While the initiative is commendable on paper, the Freedom Front […]

The post Tshwane Metro’s water partnership may be doomed to fail appeared first on Freedom Front Plus.

Read moreTshwane Metro’s Water Partnership May Be Doomed to Failure
28 November 2025

More Than R200-Million Spent on Unused Sports Stadiums by Limpopo Municipalities

Location: News

We know of at least eight stadiums that are currently serving no purpose

Read moreMore Than R200-Million Spent on Unused Sports Stadiums by Limpopo Municipalities
26 November 2025

Lesotho and South African Organisations at Loggerheads After USAID Funding Cuts

Location: News

The Mosepele Foundation Development Forum has accused Mothers2Mothers South Africa of withholding funds but the latter says it has no choice

Read moreLesotho and South African Organisations at Loggerheads After USAID Funding Cuts
25 November 2025

Suspected Digital Fraud Most Frequent at Account Login in South Africa, TransUnion Reports

Location: Business
  • Money or gift card scams were the most prevalent fraud type from February to May 2025, reported by one-third (33%) of South Africans who said they were targeted with fraud
  • Transactions with video gaming companies, where the consumer was in South Africa, were most suspected of digital fraud in the first half of 2025 among industries analysed
  • Insurance sector experienced the largest increase in the volume of suspected digital fraud among industries analysed, over the study period

According to the newly released TransUnion® (NYSE: TRU) H2 2025 Update to the Top Fraud Trends Report, the rate of suspected digital fraud[1] was the highest in the consumer lifecycle at account login for South Africa with 2.6% of those types of transaction attempts when the consumer was in the country being suspected of digital fraud in the first half (H1) of 2025. This aligns with a global trend of fraud shifting to account takeover attempts which typically occur at login. Globally, 4.3% of account login transactions in H1 2025 were suspected of digital fraud.

The report, which draws on proprietary data from TransUnion’s global intelligence network from billions of transactions from over 40,000 websites and apps and a consumer survey across 18 countries, reveals that fraud is growing.

“South Africa stands at a critical juncture in its digital evolution where opportunity and vulnerability intersect. As the nation embraces rapid digital transformation, the surge in online activity has inadvertently opened new doors for fraudsters, whose tactics are growing more sophisticated by the day. This convergence of accelerated digital adoption, economic strain and criminal innovation has created a complex risk landscape,” said Amritha Reddy, senior director of fraud product management TransUnion Africa.

According to analysis of TransUnion’s customers in its global intelligence network, digital account takeover volume worldwide grew 21% year-over-year (YoY) from H1 2024 to H1 2025, signalling a rapid escalation. The volume of digital account takeovers surged 141% from H1 2021 to H1 2025, underscoring persistent rise of this fraud type over time and reflecting the increasing sophistication of fraudsters who exploit stolen credentials and bypass authentication systems.

"As account takeover fraud surges, businesses can no longer afford solely reactive defences,” said Reddy. “The growing sophistication of fraudsters demands a proactive investment in layered security and identity intelligence. In today’s threat landscape, protecting customer accounts is not just a priority, it’s a business imperative."

Highest Rate of Suspected Digital Fraud in Video Gaming

Among industries analysed globally, the video gaming sector recorded the highest percentage of suspected digital fraud attempts in the first half of 2025, reaching 13.5%. This represents a significant 28% rate increase compared to the same period in 2024, underscoring the growing vulnerability of this sector to fraudulent activity.

For transactions where the consumer was in South Africa, the rate of suspected digital fraud attempts from February to May 2025 was the highest in video gaming at 7.7%. The greatest increase in the volume of digital transactions suspected to be fraudulent over that time was in the insurance industry, with a 154% uptick.

Chart 2: Suspected Digital Fraud Attempts in South Africa, by Sector

Industry

Suspected digital fraud attempt rate H1 2025

Change in volume of suspected digital fraud attempts from H1 2024 to H1 2025

Video gaming

7.7%

-1%

Insurance

6.7%

+154%

Communities (web properties like online forums and dating sites)

3.2%

-45%

Financial services

3.0%

-49%

Logistics

2.1%

-99%

Retail

1.1%

-57%

Telecommunications

0.7%

-96%

Source: TransUnion global intelligence network

“As the risk from consumer scams threatens identity integrity, organisations should rely on a mixture of data, risk signals, technology and tools to prevent fraud,” said Reddy. “The Report highlights that business leaders rank[2] identity verification, device reputation and behavioural biometrics as the leading three fraud prevention technologies.

“Businesses and financial institutions should also invest in sustained education and awareness campaigns to mitigate against schemes like account takeovers. Preventing fraud must by necessity be a multi-pronged strategy, if businesses and consumers are to stay ahead of fraudsters whose strategies continue to evolve too,” she said. “By harnessing advanced technologies, fostering cross-sector collaboration, and prioritising consumer trust, South Africa can chart a path toward a secure and inclusive digital future.”

Consumer-Reported Exposure to Fraud Grows Amid Gaps in Awareness and Prevention

Globally, consumers continue to face a wide range of scams, with tactics often tailored to regional behaviours and vulnerabilities. TransUnion’s survey found that 48% of consumers surveyed globally reported being targeted by email, online, phone call or text messaging fraud from February to May 2025, with 59% of South Africans saying the same thing. Globally, 52% were unaware that they were targeted, as were 42% of South Africans, indicating potential fraud under-recognition and a gap in fraud awareness.

Consumers in five of the six African countries surveyed reported money or gift card scams as the most experienced fraud type. In South Africa money or gift card scams was the most common fraud type – reported by 33% of those who said they were targeted with email, online, phone call or text messaging fraud from February to May 2025. Among those South Africans who said they were targeted, the next most frequently reported scams were phishing (31%), smishing (30%), and vishing (29%), with these three designed to deceive individuals into giving up their valuable personal or financial information.

South Africa Saw the Greatest Percentage of Respondents in Africa Indicating They Fell Victim to Fraud from February to May 2025

Country Targeted and fell victim Targeted but didn’t fall victim Not targeted Most reported fraud scheme
South Africa 13% 46% 42% Money/gift card
Kenya 10% 71% 19% Vishing
Zambia 9% 76% 15% Money/gift card
Rwanda 9% 49% 42% Money/gift card
Namibia 8% 57% 35% Money/gift card
Botswana 6% 68% 26% Money/gift card

Source: TransUnion consumer survey

“As scammers continue to evolve their tactics to enrich themselves, it’s more important than ever for consumers to regularly review their credit reports to ensure all listed information is accurate,” said Reddy.”

TransUnion came to its conclusions about digital fraud and data breaches based on intelligence from its array of TransUnion fraud prevention solutions. To learn more about how TransUnion fraud prevention solutions can help businesses avoid fraud and prevent fraud losses, click here.

Specific country and regional data in the report includes South Africa, Botswana, Brazil, Canada, Chile, Colombia, Costa Rica, the Dominican Republic, El Salvador, Guatemala, Honduras, Hong Kong, India, Kenya, Mexico, Namibia, Nicaragua, the Philippines, Puerto Rico, Rwanda, Spain, the United Kingdom, the United States and Zambia. Download the TransUnion H2 2025 Update to the Top Fraud Trends Report for more information and insights about the global fraud trends.


[1] Suspected digital fraud attempts reflect those which TransUnion customers determined met one of the following conditions: 1) denial in real time due to fraudulent indicators, 2) denial in real time for corporate policy violations, 3) fraudulent upon customer investigation, or 4) a corporate policy violation upon customer investigation.

[2] As found by TransUnion’s online business survey conducted from 29 May to 6 June 2025 in partnership with third-party research provider, Dynata. Findings were included in TransUnion’s H2 2025 Update to the Top Fraud Trends Report

Read moreSuspected Digital Fraud Most Frequent at Account Login in South Africa, TransUnion Reports
21 November 2025

Domestic Violence Against Women: More Cases Are Being Reported to Police

Location: News

Women might be more likely to report cases than before, or violence is actually increasing.

Read moreDomestic Violence Against Women: More Cases Are Being Reported to Police
19 November 2025

US and Lesotho Strike 5-Year Health Funding Pact

Location: News

Abrupt US aid cuts earlier this year caused havoc in the nation’s health system

Read moreUS and Lesotho Strike 5-Year Health Funding Pact
14 November 2025

Tender for Operating Krugersdorp Game Reserve Issued

Location: News

Constant pressure from the Freedom Front Plus (VF Plus) on the Mogale City Local Municipality (Krugersdorp, Magaliesburg, Muldersdrift) has been key in setting things in motion to reopen the Krugersdorp Game Reserve. After years of making promises during State of the City addresses, Integrated Development Plan meetings and numerous council sessions, the Municipality has finally […]

The post Tender for operating Krugersdorp Game Reserve issued appeared first on Freedom Front Plus.

Read moreTender for Operating Krugersdorp Game Reserve Issued
14 November 2025

How South Africa’s Job Market Has Changed

Location: News

There are 2.6-million more jobs than in 2008, but 10.4-million more people who need them

Read moreHow South Africa’s Job Market Has Changed
5 November 2025

Official Implicated in Corruption Appointed Head of KZN Social Development

Location: News

Onkemetse Edwin Kabasia is implicated by multiple forensic investigations into procurement irregularities in Gauteng

Read moreOfficial Implicated in Corruption Appointed Head of KZN Social Development
4 November 2025

Child Support Grant Must Be Increased to End Child Hunger, Report Says

Location: News

The grant has reduced child hunger, but 1.2-million more children are short of food than in 2019

Read moreChild Support Grant Must Be Increased to End Child Hunger, Report Says
3 November 2025

Soccer Field Offers Hope to Johannesburg’s Children

Location: News

Field of Dreams project aims to counter the neglect of the city’s public parks

Read moreSoccer Field Offers Hope to Johannesburg’s Children
31 October 2025

More Than 10-Million Consumers Cannot Repay Their Debt

Location: News

But there is a silver lining

Read moreMore Than 10-Million Consumers Cannot Repay Their Debt
28 October 2025

How Johannesburg Residents Are Protecting Their Power Lines

Location: News

“Secure infrastructure should be covered by our rates. We’d much rather spend the extra money on beautifying our local park.”

Read moreHow Johannesburg Residents Are Protecting Their Power Lines
27 October 2025

District Six Claimants Wonder if They Will Be Alive by the Time Government Redevelops the Historic Site

Location: News

“Hopefully, the next generation will perhaps benefit,” says 77-year-old claimant

Read moreDistrict Six Claimants Wonder if They Will Be Alive by the Time Government Redevelops the Historic Site
24 October 2025

Child Support Grant Cannot Feed a Child

Location: News

Cost of meeting a child’s nutritional needs exceeds R560 grant

Read moreChild Support Grant Cannot Feed a Child
17 October 2025

African Languages for AI: The Project That’s Gathering a Huge New Dataset

Location: News

When a language isn’t in the data, its speakers aren’t in the product – and AI cannot be safe, useful, or fair for them.

Read moreAfrican Languages for AI: The Project That’s Gathering a Huge New Dataset
10 October 2025

How the Size of South Africa’s Police Force Compares to Other Countries

Location: News

The country has a growing shortage of detectives

Read moreHow the Size of South Africa’s Police Force Compares to Other Countries
  • Previous
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Page 5
  • Interim pages omitted …
  • Page 24
  • Next

Copyright © 2026 · MyZA · All Rights Reserved · Powered by Stratlec Online