• Skip to main content
  • Skip to header right navigation
  • Skip to after header navigation
  • Skip to site footer
MyZA

MyZA

News, Directory, Events and Other Stuff

  • Social Media
  • Sport
  • World News
  • Home
  • Submit News
  • Directory
  • Events
  • Stratlec
  • TFSA
  • News
    • APO
    • Today’s Sport News
    • Todays Social Media and Tech Headlines
    • Today’s World News
    • Today’s SA Financial News
  • Contact
You are here: Home / News / Innovative Financing and Policy Support: Accelerating Renewable Energy Development in Africa (By Ana Hajduka)

Innovative Financing and Policy Support: Accelerating Renewable Energy Development in Africa (By Ana Hajduka)

15 August 2024 by Guest
AOW: Investing in African Energy

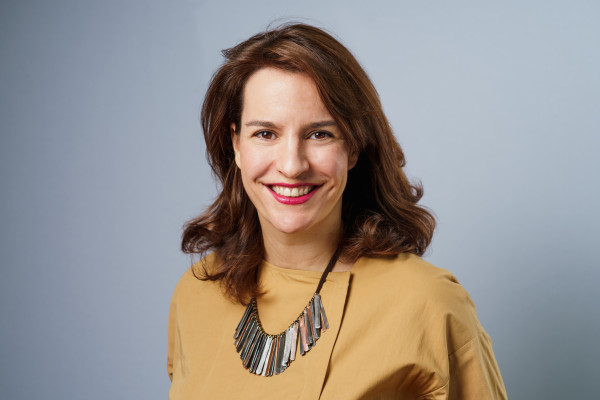
By Ana Hajduka, founder and CEO of Africa GreenCo (www.AfricaGreenCo.com).

As Africa’s energy sector deregulates, exciting opportunities open up for financial innovation to benefit consumers. Private-sector buyers and traders can mitigate default risk and provide certified green energy at lower cost, writes Ana Hajduka, founder and CEO of Africa GreenCo.

Africa's renewable energy potential is undeniable, but it remains largely untapped. The problem is that the financing landscape for renewable energy and other projects in Africa was previously reliant on state utilities as buyers.

The scale of projects that could be financed in a country were then limited by the fiscal capabilities of that country and the sovereign guarantees it could provide.

This traditional model of relying on countries to provide such guarantees has faced recent challenges, because of increasing debt burdens, and shifting economic priorities.

Opportunities have therefore emerged for innovative financial approaches that will ensure more guarantees can be acquired from other sources and that risk can be diversified across a portfolio of suppliers and customers.  This would see more projects achieving financial close, to ultimately provide more African people with clean energy.

There is also room to not only grow new renewable energy supply, but to create new renewable energy markets on the continent, where that supply can be sold.

As a consequence, the market is opening up to allow alternative buyers of new renewable energy, which can utilize existing regional competitive energy markets to diversify its risks – buyers such as GreenCo.

This is extremely relevant at the moment. Legislation like South Africa’s Electricity Regulation Amendment Bill, is set to open up the electricity sector to new supply and trading models. This foreshadows the opening of a competitive spot market for electricity trade in South Africa – linking in the future the South African spot market with that of the Southern African Power Pool.

Namibia did something similar a couple of years ago, as did Zambia.

These regulatory market developments are important as they facilitate innovation and new private sector business models through which there can be a scale up of bankable offtake agreements for new supply. The problem in the region is not lack of projects. It's not lack of funding. It’s earning enough lender trust to lend on the back of a  20-25 year power purchase agreement backed by a private sector buyer without state fiscal support.  

Transmission capacity

Transmission constraints are another factor in this emerging scenario. The development of the electricity sector across the region effectively has a ceiling, determined by the available transmission network for new generation.

Previously, development finance institutions would only fund state utilities, and then only when it was proved that sufficient generation would be coming on board to utilize any new transmission infrastructure.

Now, thanks to the growing liberalisation focus in the region, allowing new private sector participants to buy and trade power, these transmission funding inflows can be facilitated. This new supply will be critical to making new transmission investments bankable.

If the private sector can sufficiently guarantee that any proposed new capacity coming on board will utilise the necessary transmission infrastructure, that new capacity effectively backs the viability of the new transmission investing – bringing a direct value add to the state utilities in South Africa and the rest of the SADC region.

Regulatory readiness

But for all of this to fall into place, we need a convergence of the relevant regulatory readiness – and we are already seeing this across the region. In many SADC countries, new legislation is providing the regulatory clarity that the private sector requires to venture into supply, transmission and trade.

The entire ecosystem must work for new entrants, and lenders. Until now, lenders have seldom considered state utilities to be creditworthy, and they have required significant fiscal guarantees to cover the power-purchase obligations of those utilities.

That model is a double whammy. Not only does it encumber utilities with debt for new generation, but it hits the national fiscus as well.

In South Africa, for example, the widely respected REIPPP process has brought online a significant amount of new generation. However, once the South African government started reporting on the process in accordance with IMF fiscal transparency regulations, this added an additional 36% to the contingent liabilities of the national treasury – almost $15 billion – overnight. That is money that can no longer be channeled into education, health and other key infrastructure development (water, transmission etc).

The REIPPP model has been extremely successful in the electricity sector, but it has perhaps outlived its usefulness. There are other priorities, and the private sector should be sufficiently capable to deliver on its own, with the lending community partnering accordingly.

The REIPPP model can be replicated in cases such as storage tenders, and in the transmission space. While transmission is usually considered a government function, it would certainly be possible to incentivize the private sector – and lenders – to enter the space.

New licensees

Across the region, markets are liberalising rapidly. South Africa has shown it can happen almost overnight, as in the case of the country’s generation regulations. This has allowed third-party wheeled projects, from generators directly to customers, and facilitated new license applicants in the market such – such as GreenCo.

This shows how market thinking about the development of the electricity sector has fundamentally changed. There is collaboration like never before.

For GreenCo, events like the forthcoming AOW event offer opportunities to align with mining, commercial and industrial offtakers, as well as suppliers and IPPs. For an entity like ours, it’s also a chance to show potential customers and suppliers the bankability of our own offtake; that lenders have confidence in our power purchase agreements.

Financial innovation must happen in a way that makes lenders comfortable. What that looks like in our case is that all our payment obligations are backed by an internationally AA- credit rated guarantee provider GuarantCo.

We are entering the South African market operationally ready to supply customers within South Africa and outside; and with financial readiness in the form of innovative guarantee structures to be considered bankable in the market.

The ultimate beneficiaries of this financial innovation must be the consumers. Many are looking to decarbonise their operations – for climate change reasons, and to make their products competitive on international markets.

Affordability is another key consideration. In our case, by being able to provide sufficient operational and financial risk mitigation to the lenders of the generators that supply to us, we can supply electricity far more affordably.

Around 70% of the costs of a generation or renewable energy project is from the cost of debt. Therefore, the more bankable an offtaker is, the lower the debt costs, and the cheaper the electricity – a clear demonstration of the benefits of financial innovation for the end consumer.

  • AOW: Investing in African Energy unites industry leaders to develop policy, share discoveries, secure investment, and shape Africa’s energy future. The event runs from October 7 – 11 at the CTICC.

Distributed by APO Group on behalf of AOW: Investing in African Energy.

About GreenCo: 
GreenCo is a renewable energy buyer and trader operating in Southern Africa (Zambia, South Africa, Zimbabwe and Namibia); purchasing power from renewable energy generators and selling that electricity to utilities, private sector offtakers (i.e. commercial and industrial users), national power trading markets and to the competitive markets of the Southern African Power Pool (SAPP). GreenCo is an active trader on SAPP and holds a number of applicable licenses covering its operations within the Southern African region. Through its activities, GreenCo will increase the supply of, and demand for, finance for energy projects, and mobilise private sector capital more quickly towards critical and transformative capacity addition. For more information please see: www.AfricaGreenCo.com

Media files
AOW: Investing in African Energy
Download logo

By Ana Hajduka, founder and CEO of Africa GreenCo.

As Africa’s energy sector deregulates, exciting opportunities open up for financial innovation to benefit consumers. Private-sector buyers and traders can mitigate default risk and provide certified green energy at lower cost, writes Ana Hajduka, founder and CEO of Africa GreenCo.

Africa’s renewable energy potential is undeniable, but it remains largely untapped. The problem is that the financing landscape for renewable energy and other projects in Africa was previously reliant on state utilities as buyers.

The scale of projects that could be financed in a country were then limited by the fiscal capabilities of that country and the sovereign guarantees it could provide.

This traditional model of relying on countries to provide such guarantees has faced recent challenges, because of increasing debt burdens, and shifting economic priorities.

Opportunities have therefore emerged for innovative financial approaches that will ensure more guarantees can be acquired from other sources and that risk can be diversified across a portfolio of suppliers and customers.  This would see more projects achieving financial close, to ultimately provide more African people with clean energy.

There is also room to not only grow new renewable energy supply, but to create new renewable energy markets on the continent, where that supply can be sold.

As a consequence, the market is opening up to allow alternative buyers of new renewable energy, which can utilize existing regional competitive energy markets to diversify its risks – buyers such as GreenCo.

This is extremely relevant at the moment. Legislation like South Africa‘s Electricity Regulation Amendment Bill, is set to open up the electricity sector to new supply and trading models. This foreshadows the opening of a competitive spot market for electricity trade in South Africa – linking in the future the South African spot market with that of the Southern African Power Pool.

Namibia did something similar a couple of years ago, as did Zambia.

These regulatory market developments are important as they facilitate innovation and new private sector business models through which there can be a scale up of bankable offtake agreements for new supply. The problem in the region is not lack of projects. It’s not lack of funding. It’s earning enough lender trust to lend on the back of a  20-25 year power purchase agreement backed by a private sector buyer without state fiscal support.

Transmission capacity

Transmission constraints are another factor in this emerging scenario. The development of the electricity sector across the region effectively has a ceiling, determined by the available transmission network for new generation.

Previously, development finance institutions would only fund state utilities, and then only when it was proved that sufficient generation would be coming on board to utilize any new transmission infrastructure.

Now, thanks to the growing liberalisation focus in the region, allowing new private sector participants to buy and trade power, these transmission funding inflows can be facilitated. This new supply will be critical to making new transmission investments bankable.

If the private sector can sufficiently guarantee that any proposed new capacity coming on board will utilise the necessary transmission infrastructure, that new capacity effectively backs the viability of the new transmission investing – bringing a direct value add to the state utilities in South Africa and the rest of the SADC region.

Regulatory readiness

But for all of this to fall into place, we need a convergence of the relevant regulatory readiness – and we are already seeing this across the region. In many SADC countries, new legislation is providing the regulatory clarity that the private sector requires to venture into supply, transmission and trade.

The entire ecosystem must work for new entrants, and lenders. Until now, lenders have seldom considered state utilities to be creditworthy, and they have required significant fiscal guarantees to cover the power-purchase obligations of those utilities.

That model is a double whammy. Not only does it encumber utilities with debt for new generation, but it hits the national fiscus as well.

In South Africa, for example, the widely respected REIPPP process has brought online a significant amount of new generation. However, once the South African government started reporting on the process in accordance with IMF fiscal transparency regulations, this added an additional 36% to the contingent liabilities of the national treasury – almost $15 billion – overnight. That is money that can no longer be channeled into education, health and other key infrastructure development (water, transmission etc).

The REIPPP model has been extremely successful in the electricity sector, but it has perhaps outlived its usefulness. There are other priorities, and the private sector should be sufficiently capable to deliver on its own, with the lending community partnering accordingly.

The REIPPP model can be replicated in cases such as storage tenders, and in the transmission space. While transmission is usually considered a government function, it would certainly be possible to incentivize the private sector – and lenders – to enter the space.

New licensees

Across the region, markets are liberalising rapidly. South Africa has shown it can happen almost overnight, as in the case of the country’s generation regulations. This has allowed third-party wheeled projects, from generators directly to customers, and facilitated new license applicants in the market such – such as GreenCo.

This shows how market thinking about the development of the electricity sector has fundamentally changed. There is collaboration like never before.

For GreenCo, events like the forthcoming AOW event offer opportunities to align with mining, commercial and industrial offtakers, as well as suppliers and IPPs. For an entity like ours, it’s also a chance to show potential customers and suppliers the bankability of our own offtake; that lenders have confidence in our power purchase agreements.

Financial innovation must happen in a way that makes lenders comfortable. What that looks like in our case is that all our payment obligations are backed by an internationally AA- credit rated guarantee provider GuarantCo.

We are entering the South African market operationally ready to supply customers within South Africa and outside; and with financial readiness in the form of innovative guarantee structures to be considered bankable in the market.

The ultimate beneficiaries of this financial innovation must be the consumers. Many are looking to decarbonise their operations – for climate change reasons, and to make their products competitive on international markets.

Affordability is another key consideration. In our case, by being able to provide sufficient operational and financial risk mitigation to the lenders of the generators that supply to us, we can supply electricity far more affordably.

Around 70% of the costs of a generation or renewable energy project is from the cost of debt. Therefore, the more bankable an offtaker is, the lower the debt costs, and the cheaper the electricity – a clear demonstration of the benefits of financial innovation for the end consumer.

  • AOW: Investing in African Energy unites industry leaders to develop policy, share discoveries, secure investment, and shape Africa’s energy future. The event runs from October 7 – 11 at the CTICC.

Press Release Source

Share this:

  • Share on X (Opens in new window) X
  • Share on Facebook (Opens in new window) Facebook
  • Print (Opens in new window) Print
  • Email a link to a friend (Opens in new window) Email
  • Share on LinkedIn (Opens in new window) LinkedIn
  • Share on Tumblr (Opens in new window) Tumblr
  • Share on WhatsApp (Opens in new window) WhatsApp
  • Share on Mastodon (Opens in new window) Mastodon
Category: NewsTag: Africa, African, agreement, APO, business, critical, Education, Energy, Event, Events, Exciting, Government, green, green energy, health, infrastructure, Investing, Market, mining, Namibia, new, provider, Renewable, South Africa, Water, Zambia, Zimbabwe

If you feel strongly about this article then feel free to send MyZA a ‘Letter to the Editor’ using the submission form below:


Letter to the Editor

This field is for validation purposes and should be left unchanged.
If this is in response to an article please include that article title here or as the lead in for the first paragraph of your Letter below.

Separate tags with commas

Localise your letter by naming the city your words are about. Add relevant words describing your subject. Single comma separated words of no more than 5
Your Name(Required)
Your Name will be linked to the website below.
Your personal, business or social media web site
Choose NO to not set up a user account on MyZA. User Accounts will allow you to submit letters under your own Author Name

3 Latest Letters to the Editor:

  • Older Persons Grants Land Today — No Need to Queue at Dawn

    Dear Editor, Older Persons grants are paid today, 30 October, under SASSA’s revised November payment schedule — with disability grants on Monday 2 November, children’s grants on Tuesday 3 November, and grants under review on Thursday 5 November. Two things every beneficiary should know. First, grant money does not expire on payment day. It stays…

    30 October 2026
  • November Grants Pay Early – No Need to Queue at Dawn

    Dear Editor, I run SAGrant (sagrant.co.za), a free resource helping South Africans navigate SASSA grants. November grants pay earlier than usual. Older Persons grants are paid on Friday 30 October, Disability grants on 2 November, and Child Support and other grants on 3 November. Grants still under review are paid on 5 November. The money…

    27 October 2026
  • NSFAS 2027 applications close on 31 October — SASSA households, apply now

    Dear Editor, I run SAGrant (sagrant.co.za), a free resource helping South Africans navigate SASSA grants. NSFAS applications for the 2027 academic year close on Friday 31 October 2026, and no extension is expected. If your household receives a SASSA grant, your child already passes the NSFAS financial eligibility test — but they still have to…

    25 October 2026

About Guest

Previous Post:Scaling up response to curb growing mpox outbreak in African region
Next Post:President Museveni And King Mswati III Call For A Unified African Market And Political Federation

Reader Interactions

Comments

  1. Drop Stone

    11 September 2026 at 9:05 pm

    Ja, Nee – Yes, NoOften used in succession, these two words are used to express agreement or confirmation with someone or something.Example: “Ja, Nee, I’m fine thanks.”

  2. Sw33Per

    31 August 2026 at 11:28 am

    Fun South African Fact: The oldest remains of modern humans were found in South Africa and are well over 160,000 years old.

Copyright © 2026 · MyZA · All Rights Reserved · Powered by Stratlec Online